
Mortgage Score Commitment Might Change The Case For Investing In FICO Stock
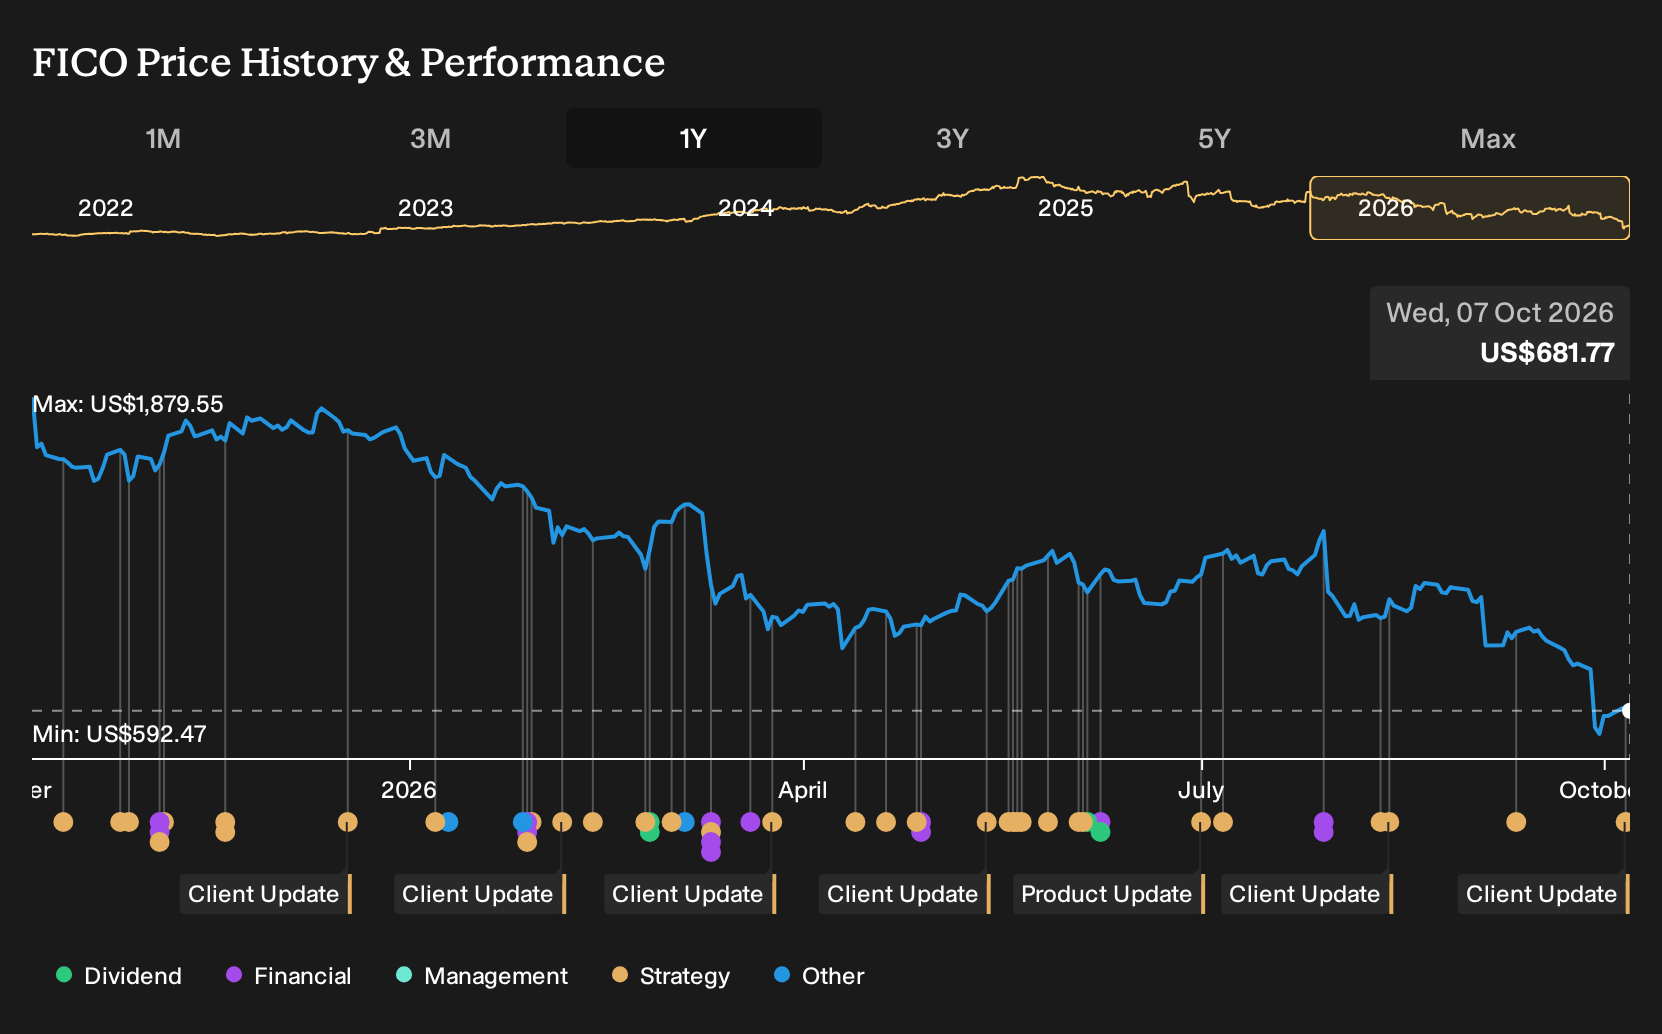
- On 6 October 2026, United Wholesale Mortgage confirmed it will continue using FICO Scores on every broker credit pull, incorporating FICO Score 10T alongside Classic scores for mortgage decisions.
- This commitment reinforces Fair Isaac's role in mortgage credit assessment, keeping its scoring models embedded in UWM's pricing, risk evaluation, and borrower financing terms.
- We will now explore how Fair Isaac's investment narrative intersects with UWM's renewed reliance on FICO Scores for broker lending decisions.
Scan how Fair Isaac's reaffirmed role in mortgage credit scoring compares with other high quality, resilient financials by reviewing the curated 31 resilient stocks with low risk scores that is shaping the next wave of risk-aware opportunities.
Fair Isaac Investment Narrative Recap
To own Fair Isaac, you need to believe its mix of FICO Scores and software can keep compounding even as mortgage rules allow rival models. The UWM decision to keep using FICO Scores on every broker pull supports that thesis but does not eliminate the regulatory overhang around score choice and pricing pressure.
The short term swing factor remains how quickly lenders adopt newer models like FICO Score 10T and expand use of FICO Platform to offset any mortgage volume or pricing strain. The biggest risk is still execution against that plan while carrying multi billion dollar debt that relies on solid cash generation.
The most relevant update here is FICO Score 10T being offered to lenders in a free dual processing program alongside Classic FICO Scores. That arrangement makes it easier for mortgage players such as UWM to compare outcomes and operationalize newer scores inside existing workflows without extra licensing cost from Fair Isaac.
For investors, this matters because wider 10T usage can influence both volumes and resilience of Scores revenue if regulators and lenders keep promoting multi score grids. The operational question is whether Fair Isaac can convert this free access into broad, paying adoption while continuing to fund FICO Platform, fraud tools and AI work within its current leverage profile.
Fair Isaac's narrative projects US$3.4b revenue and US$1.3b earnings by 2029. This implies 12.5% yearly revenue growth and an earnings increase of about US$485m from current earnings of US$815.0m.
Discover why Fair Isaac's fair value indicates an 84% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
One alternate angle focuses on concentration risk. Before this UWM news, the most cautious analysts were already assuming slower revenue growth of 6.3% a year and a lower 2029 P/E of 12.1x for Fair Isaac. That view reflects concern that if even one major partner shifts away, earnings of about US$1.3b look fragile. You can treat today’s announcement as a fresh data point and compare how your own expectations stack up against both the bullish and the bearish cases.
Explore 4 other Fair Isaac fair value estimates, including one that suggests it could be worth just $1113!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Fair Isaac research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Fair Isaac. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fair Isaac's overall financial health at a glance.
Looking For More Ideas Beyond Fair Isaac?
Once you have a view on Fair Isaac, it can help to cross check that thesis against other businesses with different risk and return profiles using the Simply Wall St Screener.
- For investors who want quality at a reasonable entry point, scan a curated set of companies trading below estimated value through the 29 high quality undervalued stocks.
- If capital preservation comes first for you, focus on resilient businesses with conservative financial profiles by reviewing the 31 resilient stocks with low risk scores.
- For those hunting for under-the-radar potential, widen your opportunity set with a hand picked collection of 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com