
Unum Group (UNM) Could Be 9% Undervalued As Earnings Near
Unum Group earnings event in focus
Unum Group (UNM) has set November 3, 2026, for its third quarter results release, with senior management hosting an earnings call the following morning to walk investors through the numbers.
Unum Group heads into this earnings release with some momentum, as the share price has risen 6.24% over the past week and 5.38% over 90 days. The 1 year total shareholder return of 21.41% and 5 year total shareholder return of about 4x highlight how strongly long term holders have been rewarded overall, despite a 2.76% decline in the 1 month share price return.
Scan other insurers that are showing similar momentum and long-term compounding potential to Unum Group with a curated list of 29 high quality undervalued stocks.
The recent jump in Unum Group, combined with only a slight pullback over the past month, raises a timing question. Is the current valuation already generous, or does it still leave room to buy without waiting for a dip?
Most Popular Narrative: 8.5% Undervalued
On the most followed view of Unum Group, the fair value sits at $101.85, compared with a last close of $93.20. This puts the stock on the cheaper side of that narrative.
Unum Group’s ongoing work to shrink and reinsure its long term care block, including the additional US$3.8b of statutory reserves ceded and the reaffirmation that the remaining block is self supporting, keeps more capital and management focus available for employee benefits, which can support earnings stability and reduce pressure on net margins.
See why 22 investors see Unum Group as 8% undervalued.
Result: Fair Value of $101.85 (UNDERVALUED)
Still, the Unum Group story can change quickly if benefit ratios in group disability or life worsen, or if long term care reserves face fresh pressure.
Find out about the key risks to this Unum Group narrative.
Another View on Unum Group’s Valuation
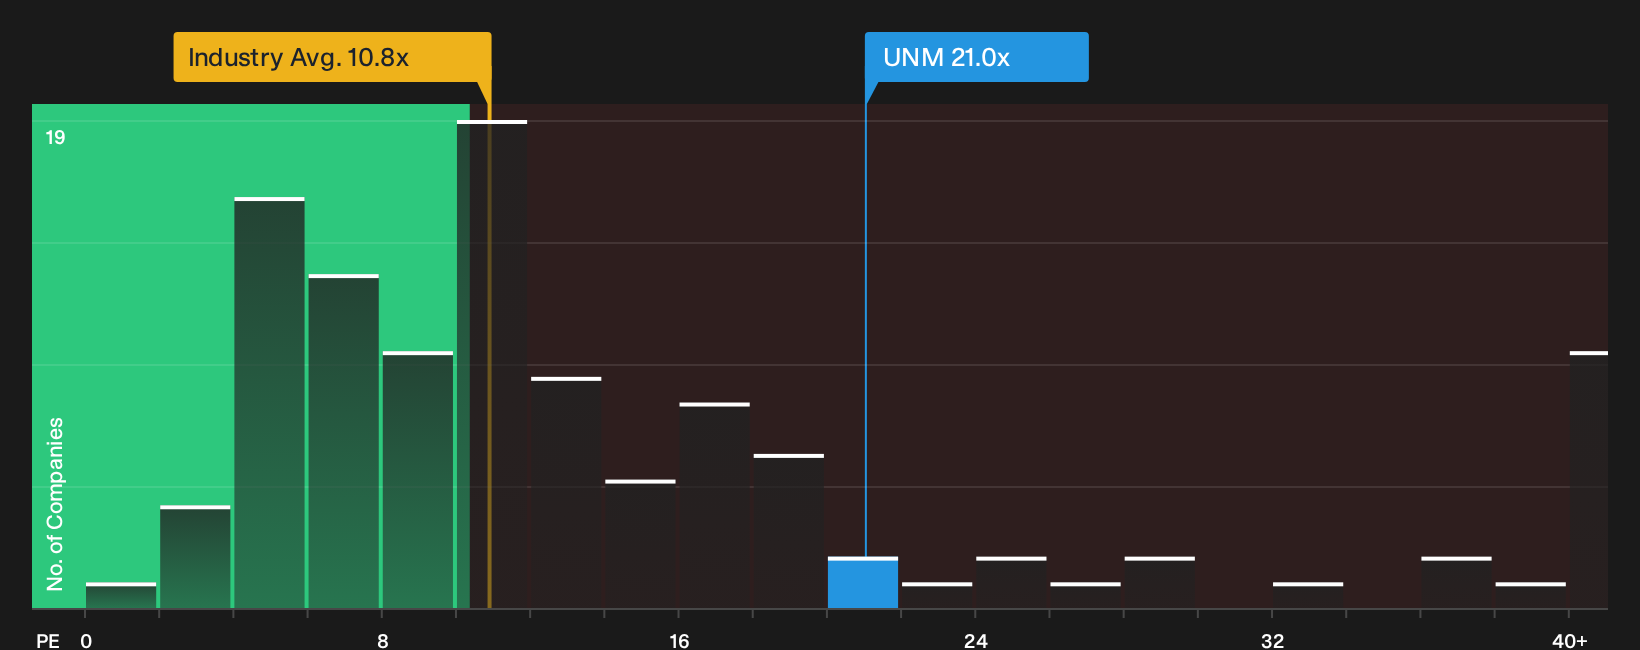
On the flip side of the fair value narrative, Unum Group trades on a P/E of 21x. That is richer than the US Insurance industry at 10.8x and above the fair ratio of 13.8x, even though it screens cheaper than peers at 35.4x. Is the premium multiple a comfort or a margin of error if expectations slip?
For investors weighing which signal to trust most, our valuation breakdown based on this P/E framework can help frame how much multiple risk you are really taking on. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Unum Group’s value and risk profile can leave the picture feeling blurred. Move quickly to review the full data and stress test your own thesis against the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Unum Group?
Do not stop with Unum Group alone. Broaden your watchlist using focused screeners that surface different types of opportunities before the crowd pays attention.
- Target steady income potential by reviewing companies in the 8 dividend fortresses that may appeal if you prioritize yield and consistency.
- Hunt for quality at a sensible price by scanning the 20 high quality undiscovered gems that pair solid fundamentals with lower market attention.
- Prioritize resilience and capital protection by filtering for the 31 resilient stocks with low risk scores so you can focus on businesses with more measured risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com