
Hulic (TSE:3003) Could Be Cheap Following A 10.6x P E Valuation Case
Recent performance snapshot for Hulic
Hulic (TSE:3003) has moved lower in recent trading, with the share price down 0.5% at the latest close and declining over the past week, month and past 3 months.
Recent softness in Hulic’s share price sits against a firmer long-run picture, with the stock down over the past quarter but supported by a 1-year total shareholder return of 8.93% and a 5-year total shareholder return of 71.69%. This suggests shorter term momentum has been fading, while longer term holders have still seen positive compounding.
Spot opportunities with similar long term compounding potential by scanning our hand picked 15 high quality undervalued stocks alongside Hulic.Bulls view Hulic’s recent dip as an opportunity to support a potential long-term compounding story, while bears question whether expectations already appear fully reflected in the price. Which side do the current valuation signals appear to support?
Preferred P/E of 10.6x for Hulic: Is it justified?
Hulic trades on a P/E of 10.6x, which sits below the broader JP market multiple while the latest close comes in at ¥1,663.5. That mix points to investors paying a lower price for each yen of earnings than the market average, even after the recent share price pullback.
The P/E ratio compares the current share price to earnings per share, so it effectively shows what investors are willing to pay for Hulic’s profit stream. For a real estate focused business with ¥843,962 in revenue and ¥119,419 in net income, this kind of lens helps you weigh the current earnings profile against expectations for future profit growth.
On one side, Hulic’s earnings growth over the past year of 15.8% exceeded both its own 5 year earnings growth rate of 10.7% per year and the Real Estate industry’s 12.7%. On the other side, earnings are forecast to grow 5.51% per year, which is slower than the JP market forecast of 9.5% per year. That combination suggests the market could be assigning a lower multiple because future profit expansion is expected to trail the wider market, even though recent growth has been solid.
Compared with direct peers, the picture is more nuanced. Hulic’s P/E of 10.6x is described as good value versus the peer average of 18.3x and below the estimated fair P/E of 15.8x that the market could move towards, yet it is considered expensive relative to the JP Real Estate industry average multiple of 9.6x. That contrast signals investors might be granting Hulic a modest premium to its sector while still pricing it at a discount to a broader peer set and to the fair ratio estimate.
Explore the SWS fair ratio for Hulic.
Result: Preferred multiple of Price-to-Earnings of 10.6x (UNDERVALUED)
Still, a weaker share price trend year to date and a value score of 2 could signal pressure if sentiment on Hulic or real estate shifts quickly.
Find out about the key risks to this Hulic narrative.
Another view on Hulic’s value
The P/E workup paints Hulic as undervalued, yet the SWS DCF model points the other way. On that cash flow lens, an estimated value of ¥158.01 per share sits far below the current ¥1,663.5, which frames the stock as heavily overvalued rather than cheap.
For readers who want to see how this cash flow based result is built step by step, Look into how the SWS DCF model arrives at its fair value.
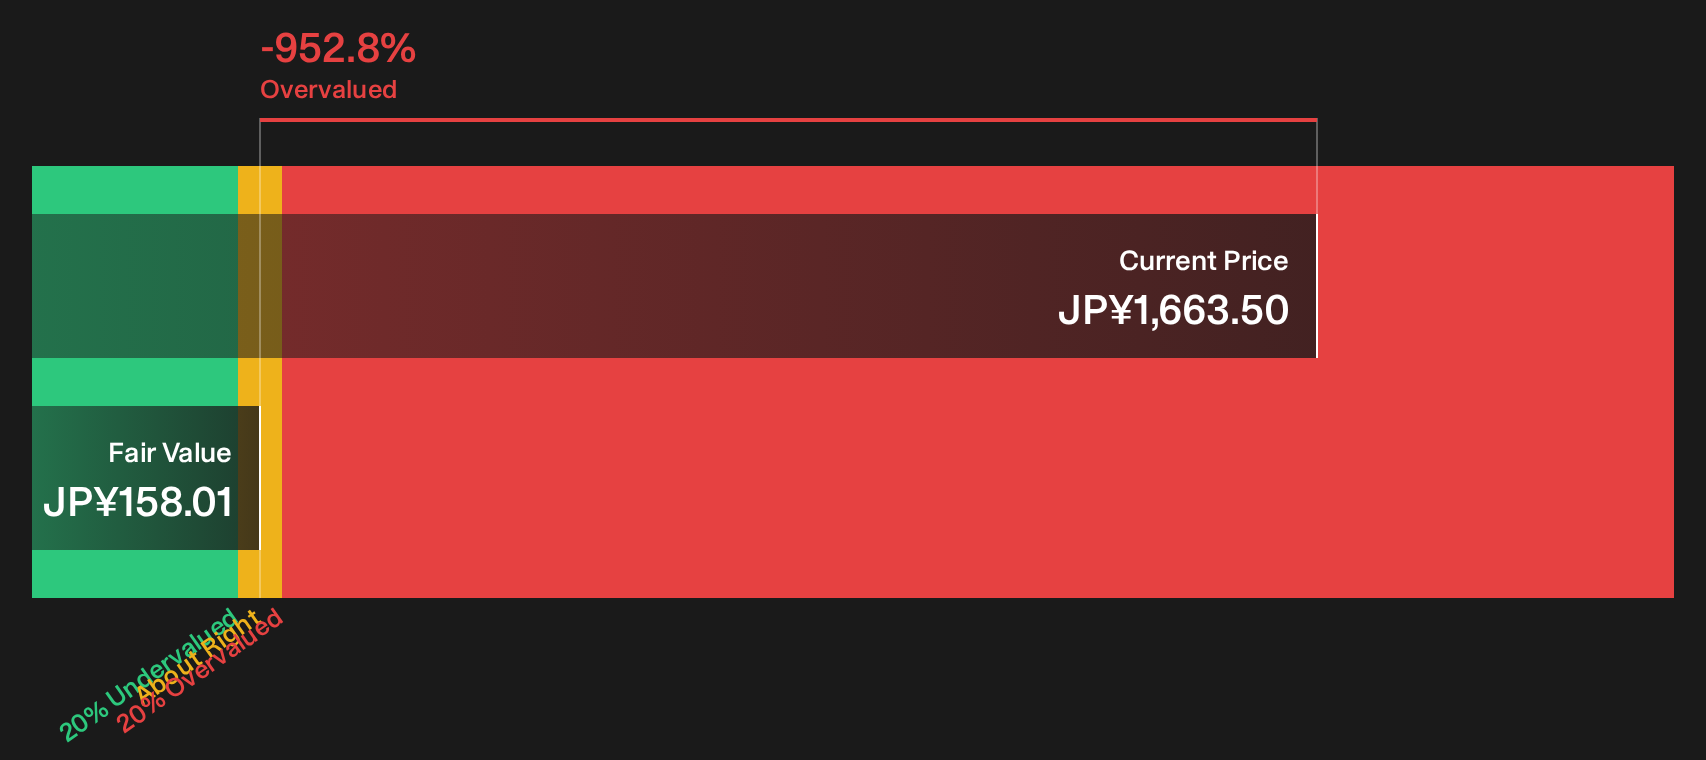
Two very different answers from one company raise a simple question for investors. Which lens do you trust more when the earnings multiple suggests opportunity but the cash flow model signals caution?
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hulic for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Hulic’s valuation and outlook do not have to leave you stuck on the fence. Move quickly, review the underlying data, and weigh both the 3 key rewards and 2 important warning signs
Ready for more ideas beyond Hulic?
If Hulic has you thinking harder about value, do not stop there. Use the Simply Wall St screener to pressure test fresh opportunities before the crowd moves.
- Target resilience first and sidestep unnecessary shocks by scanning a curated group of 22 resilient stocks with low risk scores built around steadier risk profiles.
- Hunt for hidden quality that the market may be overlooking by reviewing a focused set of 75 high quality undiscovered gems with solid fundamentals.
- Anchor your watchlist in financial strength by starting with a list of solid balance sheet and fundamentals (23 results) that highlights companies with cleaner debt and healthier cushions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com