
Verisk Analytics (VRSK) Could Be 41% Below Fair Value After Claims Tech Deals
Recent collaborations put Verisk Analytics (VRSK) squarely in the flow of digital insurance claims, as Solera and Truepic plug into its platforms to streamline repair decisions and tighten fraud checks for carriers.
Set against these new partnerships, Verisk Analytics’ share price tells a different story. The stock closed at US$168.68 and recorded a 1 day share price return of 2.11%, yet it is sitting on a year to date share price decline of 23.68% and a 1 year total shareholder return down 30.02%, signalling pressure that recent deals have not yet offset in the longer trend.
Scan beyond Verisk Analytics and see how other insurers and data platforms are positioned by reviewing our curated list of 31 resilient stocks with low risk scores.
Verisk Analytics now trades well below both analyst targets and an estimated fair value, even after the recent bounce. Is this a clear discount, or is it a warning that the market’s caution has a point?
Most Popular Narrative: 119.5% Overvalued
On Esteban’s narrative, Verisk Analytics screens as very expensive, with a fair value of $76.85 against the recent close at $168.68. That gap reflects a view that the market is paying a premium for what is seen as a slower growing but highly durable cash generator.
Verisk Analytics is a regulatory-grade data toll on the US property & casualty insurance industry, monetized through ~83% subscription revenue with ~92% client retention. VRSK's narrow-moat franchise produces FCF with an unusually high degree of predictability, durable enough to justify a 15× exit multiple at a 35% margin of safety. The 2022 to 2025 portfolio simplification (Energy, Argus, 3E, Marketing Solutions all divested) has produced a cleaner pure-play with structurally higher margins (Adj EBITDA 56.2% in 2025 vs. 53.5% in 2023) and a shrinking share count (~19% reduction since 2019). What the investor is paying for here is a regulatory annuity with an embedded MSD price-and-volume escalator, and walking away from any thesis premised on this becoming a HSD-to-DD revenue compounder.
See why 7 investors see Verisk Analytics as 119% overvalued.
Result: Fair Value of $76.85 (OVERVALUED)
Still, Verisk Analytics faces clear pressure if insurance clients push back on pricing or if regulators change how core data services are used and shared.
Find out about the key risks to this Verisk Analytics narrative.
Another View on Verisk Analytics’ Value
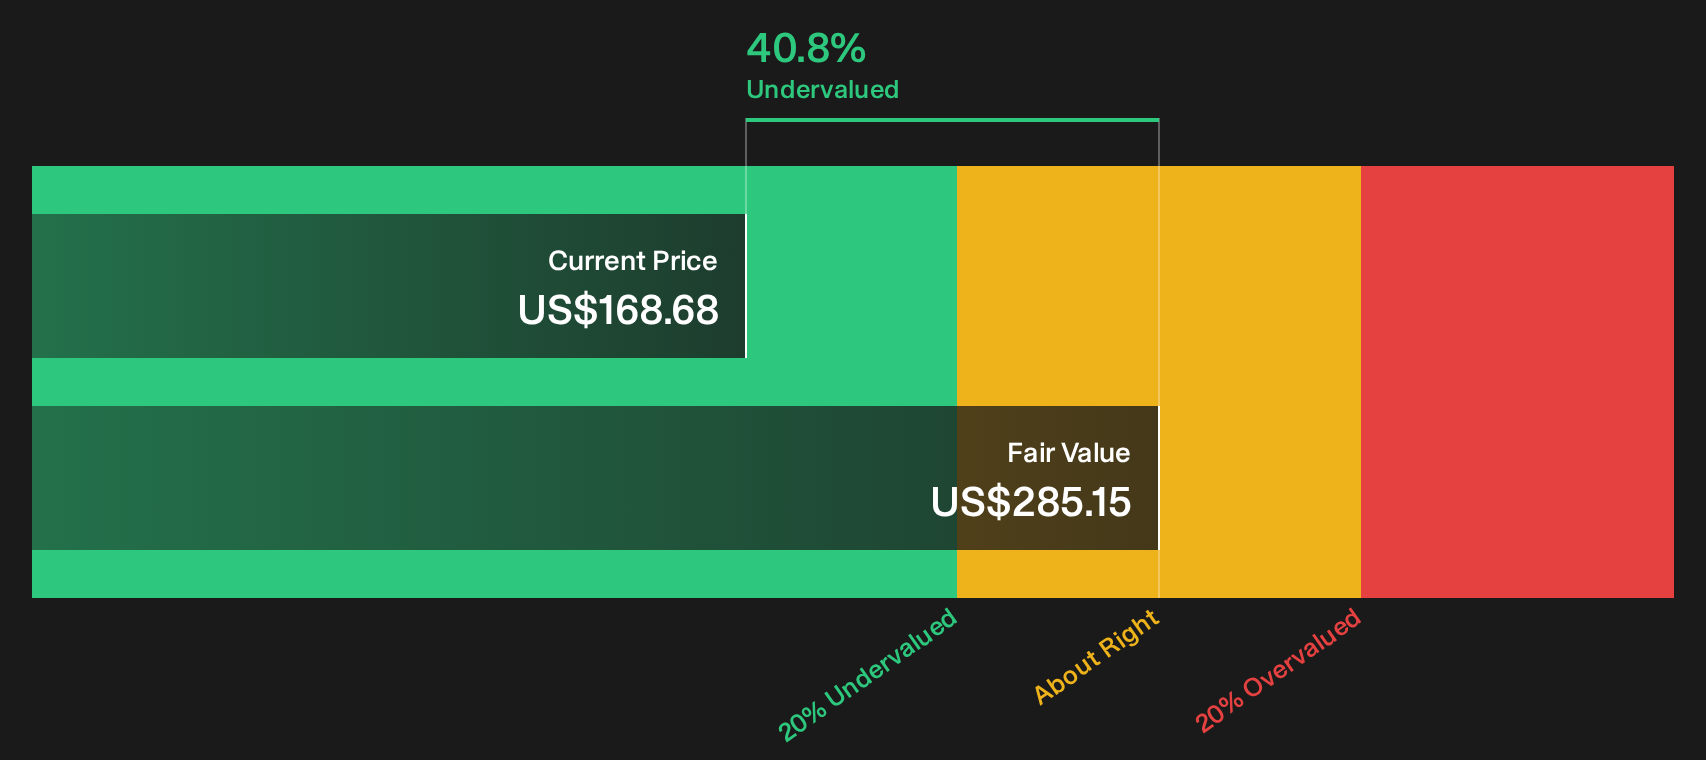
Esteban’s narrative calls Verisk Analytics overvalued at a fair value of $76.85, yet our DCF model points in the opposite direction. On that framework, VRSK at $168.68 is trading 40.8% below an estimated future cash flow value of $285.15 and screens as undervalued. Which story do you trust more: the cash flows or the cautious narrative?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Verisk Analytics can feel uncomfortable, especially when risk and reward are both on the table. If you want to move quickly and ground your own judgment in the numbers, start with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Verisk Analytics?
Do not stop at Verisk Analytics alone. Put a wider watchlist to work so you can compare quality, risk and income potential across different corners of the market.
- Target reliable income streams by checking out 8 dividend fortresses built around companies offering higher yields with a focus on sustainability and consistency.
- Hunt for mispriced opportunities through the 29 high quality undervalued stocks that highlight businesses where fundamentals and current prices look out of sync.
- Strengthen your defense by scanning the list of solid balance sheet and fundamentals (25 results) so you can concentrate on businesses with resilient finances and less fragile capital structures.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com