
Is Prologis (PLD) Cheap Or Fairly Valued On Its Latest Institutional Moves?
Prologis (PLD) has drawn fresh attention after a series of institutional filings revealed new and adjusted positions in the stock. This gives investors a clearer picture of how large asset managers are currently exposed.
Recent trading tells a mixed story for Prologis. The share price has slipped around 7% over the past month and roughly 10% over the last quarter, yet the 1 year total shareholder return of about 13% and 3 year figure near 25% point to momentum that has not fully faded.
That softer near term share price performance around US$127.30 comes as Prologis appears in a string of institutional disclosures and participates in sector events, such as its recent appearance at the 2026 North American Marketing Leadership Summit and its role in the Skybox Datacenters Project Sequel partnership in Texas. Together these developments keep attention on both growth opportunities and changing risk perceptions.
Scan how fund managers are repositioning around Prologis, then benchmark it against our curated list of list of solid balance sheet and fundamentals (25 results) to see what else is drawing institutional attention.
After a 10% slide over three months, Prologis now trades about 24% below the average analyst target, while modelled fair value sits roughly in line with the price. Is the market’s caution still too harsh, or already fair?
Most Popular Narrative: 20% Undervalued
The most followed narrative on Prologis pegs fair value at about $158 per share using an 8.7% discount rate, which sits well above the recent $127.30 close. That gap frames the current pullback as a pricing debate around future cash flows rather than a simple reaction to the latest quarter.
The build out of value added services, including a dedicated data center development platform with 5.8 GW of power pipeline and an expanding on site solar and storage business of roughly 1.3 to 1.4 GW, creates additional fee and rental streams that can support higher consolidated revenue and margins as projects are delivered.
See why 110 investors see Prologis as 20% undervalued.
Result: Fair Value of $158.23 (UNDERVALUED)
Still, the Prologis story can be knocked off course if further equity raises dilute per share earnings or if the large SEGRO deal fails to progress as planned.
Find out about the key risks to this Prologis narrative.
Another View: Prologis Through The Fair Ratio Lens
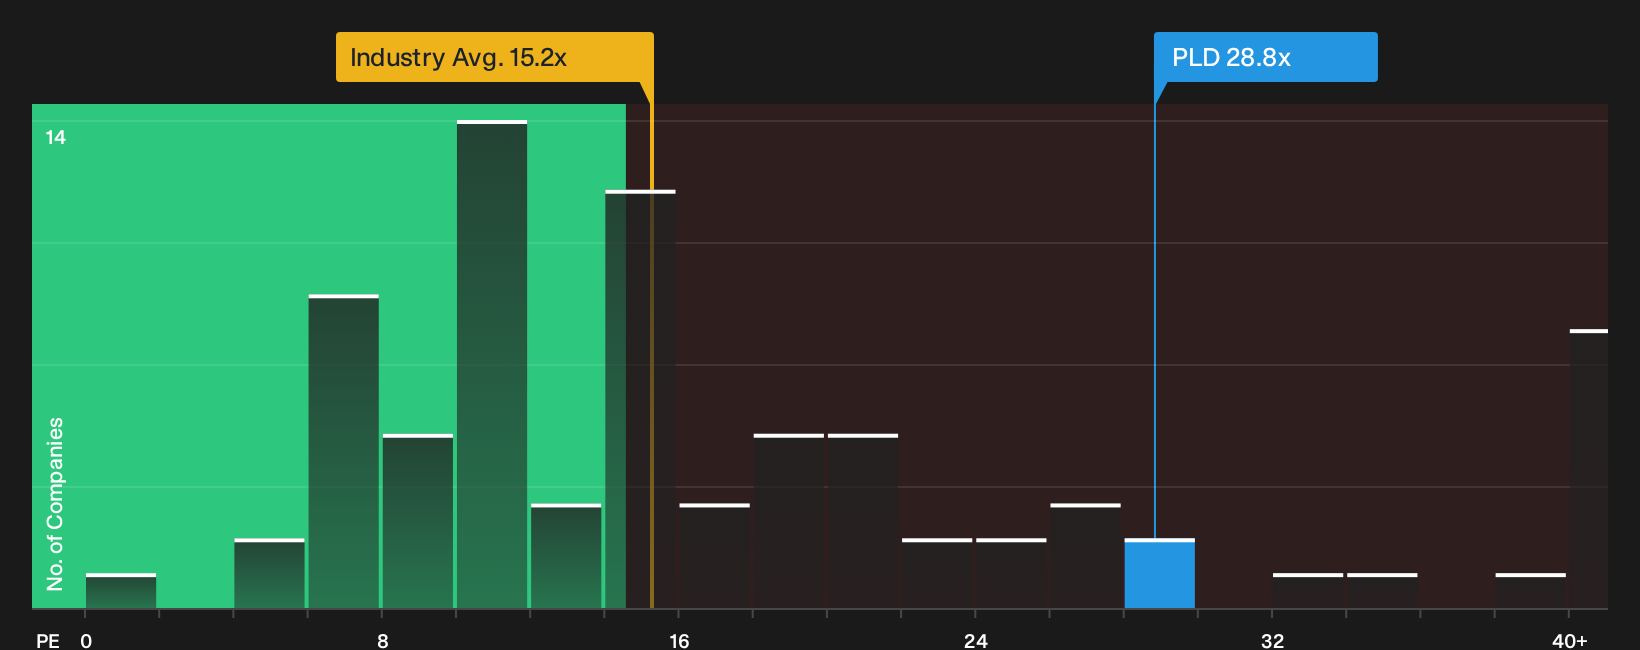
While one narrative treats Prologis as undervalued, the current P/E of 28.8x creates a different picture. It is above both the Global Industrial REITs average of 15.2x and the 25x peer average, yet below the fair ratio of 30.5x. Is that a comfort zone or a valuation squeeze waiting to happen?
For investors weighing that trade off, it helps to see how current pricing compares against detailed earnings multiples across the sector, then judge whether the premium feels justified for Prologis or not. See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Prologis for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Prologis can create as much opportunity as anxiety, especially when both risks and potential rewards are in play. Act while sentiment is still forming and weigh both sides of the story with 3 key rewards and 3 important warning signs
Looking for more ideas beyond Prologis?
Do not stop at Prologis. Use the Simply Wall Street screener to surface fresh opportunities that fit how you like to invest and manage risk.
- Target potential upside by scanning a curated set of companies that screen as 29 high quality undervalued stocks based on quality and pricing signals.
- Focus on resilience by filtering for businesses that show up in the 31 resilient stocks with low risk scores and may better match a capital preservation mindset.
- Get ahead of the crowd by tracking smaller companies highlighted as 20 high quality undiscovered gems before they attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com