
Top 3 Canadian Lithium Stocks To Watch In October 2026
High energy prices are back on the agenda, with the IMF warning that a prolonged energy shock and record public debt are now pressing on global growth. That pushes investors to look harder at real assets, including producers of key battery metals. Canadian lithium miners and processors sit directly in that conversation. This article highlights three stocks from a curated lithium mining screener that merit a closer look.
The three lithium stocks below are only a sample, and the full lithium mining screen surfaced 15 more companies with equally compelling narratives that are not covered here. To size up that wider field and quickly identify which global lithium miners and processors best fit your own thesis, go straight to the Lithium Mining screener.
Foraco International (TSX:FAR)
Foraco International is a global drilling contractor. Its Mining division generated about US$240 million, compared with roughly US$45 million from Water, and supplies the exploration and large diameter core work lithium miners rely on. The stock is valued at about CA$245 million.
For lithium investors, Foraco International offers a picks and shovels angle, with its drilling and sampling crews involved in the exploration and development spending that determines where the next projects get built.
"Tightening resource demand, water scarcity, and onshoring trends favor Foraco's specialized drilling and water segments, powering higher margins and recurring revenue growth beyond consensus."
What happens to that thesis depends heavily on how one quiet pressure in its contracts and pricing power plays out over the next few years.
That quiet contract pressure is exactly what sits at the center of the full narrative for Foraco International, revealing how pricing power could either accelerate or stall Foraco International's drilling story.

Altius Minerals (TSX:ALS)
Altius Minerals is a royalty and streaming specialist with exposure to lithium production through its Mineral Royalties segment, alongside broader interests in base metals, potash, iron ore and renewables. The company generates about CA$79 million from Mineral Royalties and CA$20 million from Renewable Royalties and holds a market value near CA$3.9b.
For lithium focused investors, Altius Minerals offers a different angle on the theme by taking royalty interests on operating projects rather than owning and running mines directly. This structure makes the timing and volume of partner production especially important.
"Growing global adoption of lithium ion batteries for EVs and grid storage, along with commentary that lithium battery shipments and energy storage shipments are increasing, points to a larger addressable market for Altius Minerals lithium royalty portfolio."
The real swing factor is how one key assumption about future royalty volumes plays through into cash generation and profit margins.
That royalty swing factor is exactly what animates the full narrative for Altius Minerals, where the full story maps how volume risk could be masking an accelerating cash flow runway.

Lithium Americas (TSX:LAC)
Lithium Americas focuses on developing the Thacker Pass lithium deposit and related processing facilities in Nevada, giving it a direct tie to global lithium mining and processing. The business is still pre revenue and has a market value of about CA$1.3b.
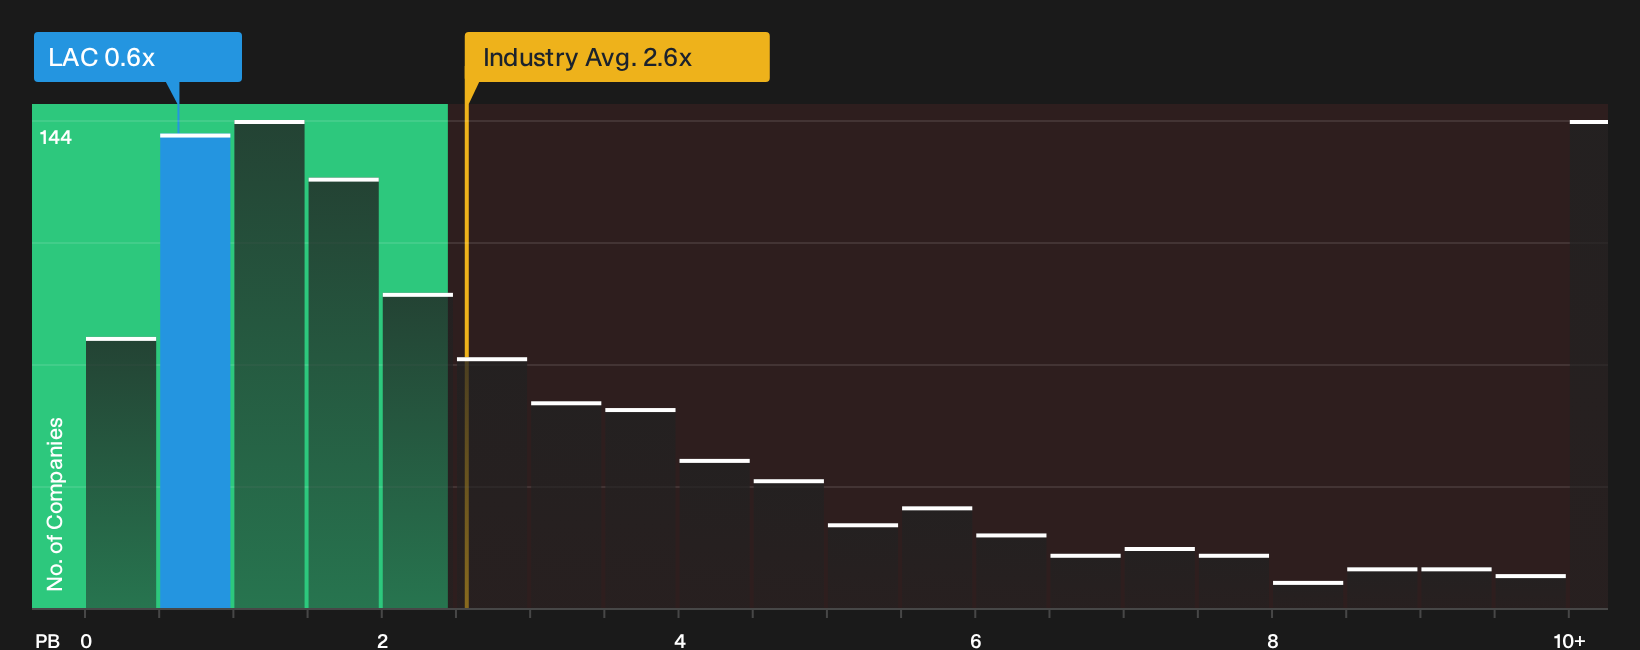
Thacker Pass provides Lithium Americas with focused exposure to lithium mining and processing. It is backed by analyst forecasts for earnings growth and a P/B near 0.6x that points to discounted book value. However, the outcome depends on how a capital-intensive funding path aligns with future project cash flows.
If that funding equation is what matters most for you, go straight to the analyst forecasts for Lithium Americas to see how projections line up against future project risk.
Curious About Fresh Investing Alternatives
Markets move fast. Breakout ideas may be identified early while laggards can remain under the radar for now. Scan fresh stock sets before the crowd and consider acting sooner rather than later.
- Spot income ideas that keep cash flowing by screening for 3 dividend fortresses that aim to balance payout strength with resilience.
- Hunt for companies quietly building durable advantages with a curated list of solid balance sheet and fundamentals (7 results) that helps you focus on financial staying power while it still matters.
- Look for early trend leaders using a targeted 92 AI infrastructure stocks designed to highlight potential candidates behind the hardware and power supporting AI momentum.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com