
Is Board Chair Exit Altering The Investment Case For Sodexo (ENXTPA:SW)?
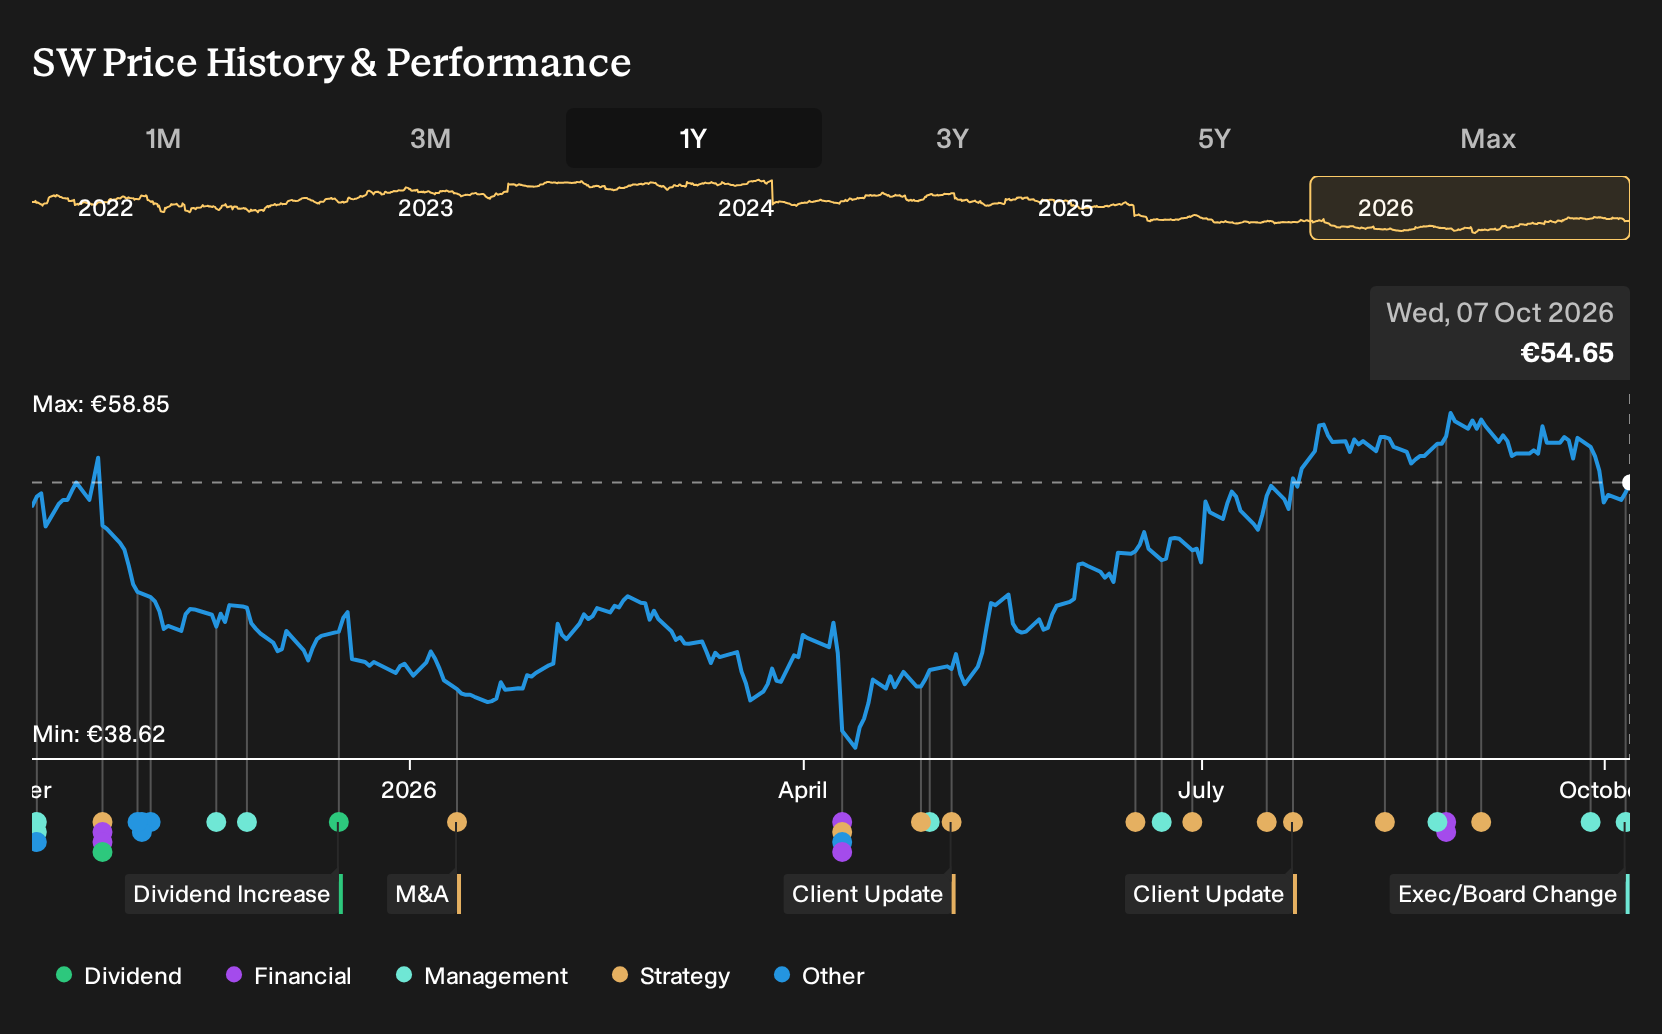
- Sodexo confirmed that Sophie Bellon will not seek renewal of her mandate as Chairwoman of the Board after December 16, 2026, following a decade of board leadership that included the spin off of Pluxee and the sale of the Sofinsod stake.
- Her decision marks a shift in governance at a time when Sodexo continues to refine its portfolio and execution. This makes board oversight and succession planning a key watchpoint for how the business pursues its operational and growth objectives.
- The discussion will now examine how Sodexo's investment narrative could be affected by Sophie Bellon stepping away from the chair.
Sodexo Investment Narrative Recap
To hold Sodexo over the next stretch, you need to believe management can translate a large global contract base into steadier earnings despite patchy recent execution. The main near term swing factor remains how quickly delayed Healthcare contracts and weaker North America growth stabilise. The latest governance headlines do not directly change those operational levers.
The bigger short term risk is that net new wins stay soft just as cost pressure and debt remain in focus. Board succession and leadership changes add some uncertainty, but the core question for you as a shareholder stays simple: Does Sodexo convert its current pipeline into profitable, on time ramp ups?
The appointment of Sarabjeet Ghadiok as Head of Marketing looks most relevant here. Marketing can influence how effectively Sodexo positions its offers in North America Education and Healthcare, where future contract ramps are expected to matter most for revenue and margins from fiscal 2026 onward.
If execution on sales and retention improves under this refreshed marketing leadership, that could support the existing catalysts around better contract wins and healthier working capital. If it does not move the needle on signings or pricing discipline, then the appointment will likely be operationally neutral for the current risk reward balance.
Sodexo's current analyst narrative points to revenues of €26.0b and earnings of €551.6m by 2029, based on forecasts that assume 3.2% yearly top line growth and an earnings increase of about €102.6m from earnings today of €449.0m.
Uncover why Sodexo's fair value is essentially aligned with its current price.
Exploring Other Perspectives
You can also look at a very different angle. The most optimistic analysts emphasize Sodexo’s healthcare and digital catalyst, expecting revenues of about €26.7b and earnings of roughly €660.9m by 2029. Their view on new leadership and marketing is much brighter, and today’s governance headlines could eventually push those projections either higher or lower.
Explore 4 other Sodexo fair value estimates, including one that suggests there may be as much as 24% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Sodexo research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Sodexo. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sodexo's overall financial health at a glance.
Looking For More Ideas Beyond Sodexo?
Once you have a view on Sodexo, it can help to line it up against other opportunities that fit your risk, income, and quality preferences. The Simply Wall St Screener gives you a filterable set of stocks so you can quickly see which businesses match the profile you care about most.
- If you want a sharper focus on quality at a reasonable entry point, scan a curated set of 185 high quality undervalued stocks that combine stronger fundamentals with more modest pricing.
- For investors who put capital preservation first, narrow your search to a 225 resilient stocks with low risk scores that screens for companies with steadier profiles and lower overall risk scores.
- If balance sheet strength matters most to you, start with a list of solid balance sheet and fundamentals (207 results) to highlight businesses carrying healthier financial foundations and more robust fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com