
Is Calix (CALX) Undervalued On Client Wins And 50G PON Trial News?
Calix (CALX) has been back in focus after Astound completed a trial of the Calix 50G PON access solution, validating high-capacity fiber speeds, while Chariton Valley Telephone adopted Calix Agent Workforce Cloud on the Calix One platform.
Despite the fresh headlines, Calix shares at US$35.54 remain under pressure, with the year-to-date share price return down 33.68% and the 1-year total shareholder return down 40.72%, even as the 7-day share price return of 3.43% hints at short-term momentum picking up again.
Scan beyond Calix and see how other broadband and AI infrastructure players are positioned with our curated list of 92 AI infrastructure stocks.
Calix now trades well below recent analyst targets, even after the latest product and client news nudged the price higher. This raises an important question: is the current momentum enough to justify taking a position today, or is it more prudent to wait for a deeper pullback?
Most Popular Narrative: 43% Undervalued
Set against a narrative fair value of $62.33 and a last close of $35.54, Calix screens as heavily discounted. The gap rests on whether its software heavy model and wider market reach can translate into the earnings path analysts outline.
The rollout of the AI native Calix One platform and Agent Workforce Cloud to roughly 1,200 migrated customers, supported by around $2b of historical platform investment and more than 0.5 billion workflows processed annually, points to further monetisation of agentic workflows that can support higher software and services revenue and improving gross margin quality.
See why 19 investors see Calix as 43% undervalued.
Result: Fair Value of $62.33 (UNDERVALUED)
Still, the Calix story can be knocked off course if memory cost inflation keeps squeezing appliance margins or if the current shareholder investigations escalate into costly litigation.
Find out about the key risks to this Calix narrative.
Another View On Calix Valuation
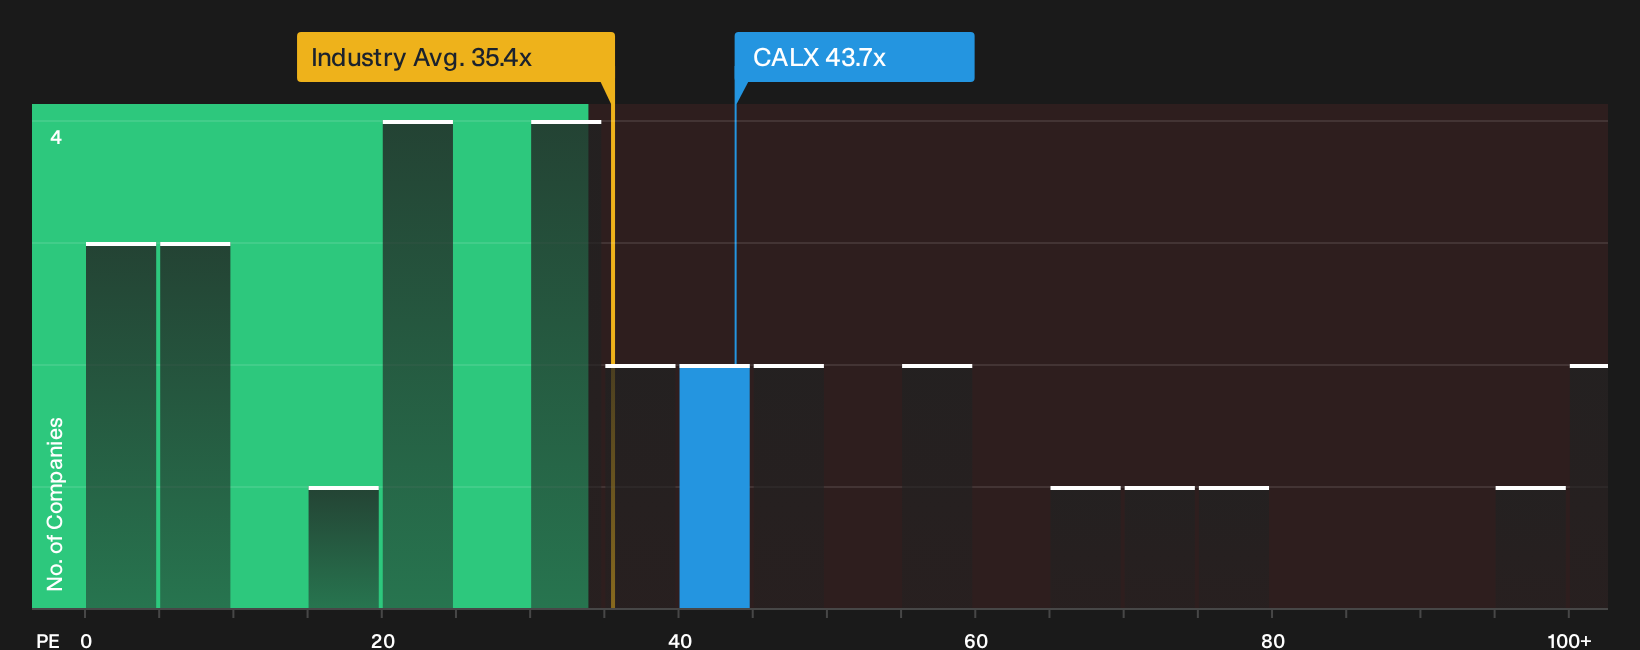
On earnings multiples, Calix screens less generous. The stock trades on a P/E of 43.7x, which is higher than both the US Communications sector at 35.4x and the fair ratio of 42.7x. This gap points to less margin for error if growth or profitability disappoint.
Compared with peers on the same metric, Calix sits roughly in line at 43.7x, which softens the signal but still leaves you asking how much upside is really left if sentiment cools.
For a closer look at how that earnings based view stacks up against other valuation angles, including the fair ratio the market could move towards, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the cautious tone around Calix really fits the full picture? Act while sentiment is still divided and weigh the potential by reviewing the 3 key rewards
Looking For More Investment Ideas Beyond Calix?
If Calix has you rethinking where the real upside might be, do not stop here. Broaden your watchlist and let data driven ideas do the heavy lifting.
- Target potential mispricing by scanning a tightly filtered set of companies that score well on quality and valuation with the 29 high quality undervalued stocks.
- Prioritise resilience and capital strength by reviewing a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions without constant refinancing worries.
- Hunt for under-followed opportunities by checking a focused pool of 20 high quality undiscovered gems that combine fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com