
Is Nektar Therapeutics (NKTR) Cheap As Rezpegaldesleukin Data Supports Phase 3 Plans?
Nektar Therapeutics (NKTR) recently presented new long-term rezpegaldesleukin data to dermatology specialists at the EADV Congress in Vienna, highlighting sustained clinical responses and detailed biomarker findings across two Phase 2b programs.
Despite the fresh rezpegaldesleukin data and Phase 3 preparations, Nektar Therapeutics has seen pressure on its shares recently, with a 7-day share price return of down 33.5% and a 30-day share price return of down 45.7% from a last close of $40.26.
The setback in shorter term share price performance, including a 90-day share price return of down 44.8%, sits alongside a very large 3-year total shareholder return. This contrasts sharply with the 1-year total shareholder return of down 28.8% and the 5-year total shareholder return of down 84.3%, suggesting that market optimism has cooled after an earlier surge.
Scan beyond Nektar Therapeutics and this rezpegaldesleukin update by reviewing a curated group of autoimmune and chronic condition players with the 35 healthcare AI stocks.
The sharp pullback in Nektar Therapeutics after upbeat rezpegaldesleukin data raises a simple question: Are investors reassessing the pipeline itself, or just resetting sentiment after an aggressive run up, before considering what the valuation now implies?
Most Popular Narrative: 72% Undervalued
The most followed narrative on Nektar Therapeutics places fair value at $144.40 per share, far above the recent close at $40.26. This frames the latest rezpegaldesleukin update against a valuation story that already assumed a lot would need to go right.
Strong initial Phase IIb and ongoing data for REZPEG in atopic dermatitis, combined with a large and growing addressable market (expected to reach nearly $30B by 2033), position Nektar to access significant new revenue streams and improve long-term earnings as the population ages and chronic inflammatory diseases rise globally.
See why 13 investors see Nektar Therapeutics as 72% undervalued.
Using a 7.24% discount rate, this narrative backs into that $144.40 figure by assuming Nektar Therapeutics can eventually reach $40.0 million of revenue and $8.8 million of earnings by around 2029. It then attaches a very large future P/E multiple of 832.97x to those profits despite analysts not expecting profitability within the next 3 years.
The same storyline leans heavily on rezpegaldesleukin advancing through Phase 3 in atopic dermatitis and into alopecia areata. It also accepts that current losses of $157.1 million and an unprofitable outlook create a long bridge between today’s cash burn and the earnings level used to justify the fair value.
Analyst targets span from $65.00 to $192.00, and the narrative effectively sits toward the top half of that range. Anyone using it as a reference point needs to decide whether a very high implied future multiple and revenue decline assumptions of 9.87% square with their own expectations for trial execution, competition and future dilution.
Result: Fair Value of $144.40 (UNDERVALUED)
Still, the entire Nektar Therapeutics story leans heavily on rezpegaldesleukin. Any trial delay or weaker than expected data could quickly challenge that 72% undervalued narrative.
Find out about the key risks to this Nektar Therapeutics narrative.
Another View On Nektar Therapeutics Valuation
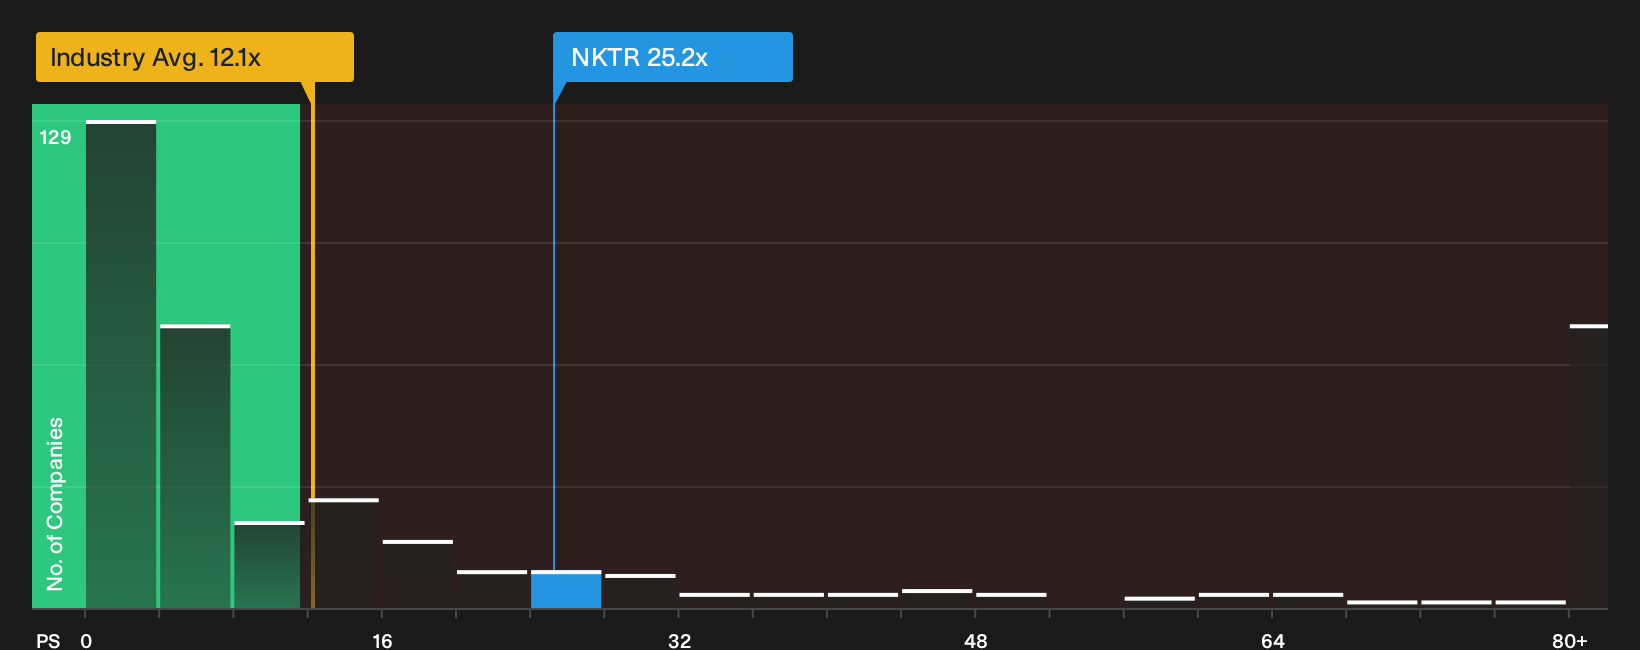
The earlier fair value of $144.40 for Nektar Therapeutics leans heavily on long term earnings assumptions and future multiples. On a simple P/S basis, the picture looks very different. NKTR trades around 25.2x sales, versus 12.1x for the US Biotechs industry and a fair ratio of 10x. This suggests investors are already paying a steep premium that could compress if sentiment cools further.
That gap between today’s P/S and the 10x fair ratio raises a clear question: Is rezpegaldesleukin, in your view, strong enough to justify paying more than both peers and the level the market could move toward over time, or is this where valuation risk starts to matter more than the upside story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Nektar Therapeutics is clearly split, and that kind of tension is usually when it pays to look at the numbers yourself and move quickly. To weigh the potential upside against the concerns that other investors are flagging, take a close look at the 1 key reward and 3 important warning signs.
Looking For More Investment Ideas Beyond Nektar Therapeutics?
Do not stop with a single story. Fresh opportunities often show up where capital has not crowded in yet, and that is where thoughtful research can really count.
- Target potentially overlooked quality by scanning through 20 high quality undiscovered gems that pair strong fundamentals with limited market attention.
- Strengthen the defensive side of your portfolio and stress test your risk tolerance with a focused look at 31 resilient stocks with low risk scores.
- Prioritize balance sheet resilience and durable business models by reviewing the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com