
Agilysys (AGYS) Could Be 24% Undervalued On 7 Cedars Expansion
Why Agilysys Stock Is Back On Investors’ Radar
Agilysys (AGYS) just expanded its relationship with 7 Cedars Resort Properties, rolling out a broad set of hospitality systems across the casino, hotel, golf and food and beverage operations.
The move gives investors a fresh real world reference point for how the company’s property management, point of sale and booking tools work together inside a complex resort environment.
Agilysys shares have picked up in the very short term, with a 1 day share price return of 3.2% and a 7 day gain of 5%, even though the 30 day share price return is down 8.5% and year to date the share price is down 11.8%. That pullback sits against a mixed picture where the 1 year total shareholder return is down 7.5%, yet holders who stayed in over three years have seen total shareholder returns of 44.3% and over five years about 89.9%. This suggests that momentum has faded recently even as longer term investors still sit on sizeable gains.
Scan beyond Agilysys and see how other hospitality and software specialists are positioning for their next move with the curated 20 high quality undiscovered gems.
Agilysys continues to gain deeper wallet share at complex resorts like 7 Cedars, yet the share price has slipped this year. Is that a healthy business temporarily marked down, or is the premium still too rich?
Most Popular Narrative: 24% Undervalued
On the numbers, the prevailing narrative pegs Agilysys at a fair value of about $133.67, compared with the recent $101.92 close. This implies the market is pricing the hospitality software specialist well below that framework while its recurring revenue story keeps building.
Rapid adoption of cloud-native, subscription-based hospitality software and the company's shift toward a SaaS revenue model is creating significantly higher and more predictable recurring revenue streams, positioning Agilysys for ongoing improvements in earnings and margin expansion as legacy perpetual license sales decline.
See why 7 investors see Agilysys as 24% undervalued.
Result: Fair Value of $133.67 (UNDERVALUED)
Still, the Agilysys story can break if hospitality spending weakens, or if aggressive point of sale and subscription targets prove harder to hit than analysts assume.
Find out about the key risks to this Agilysys narrative.
Another View On Agilysys Valuation
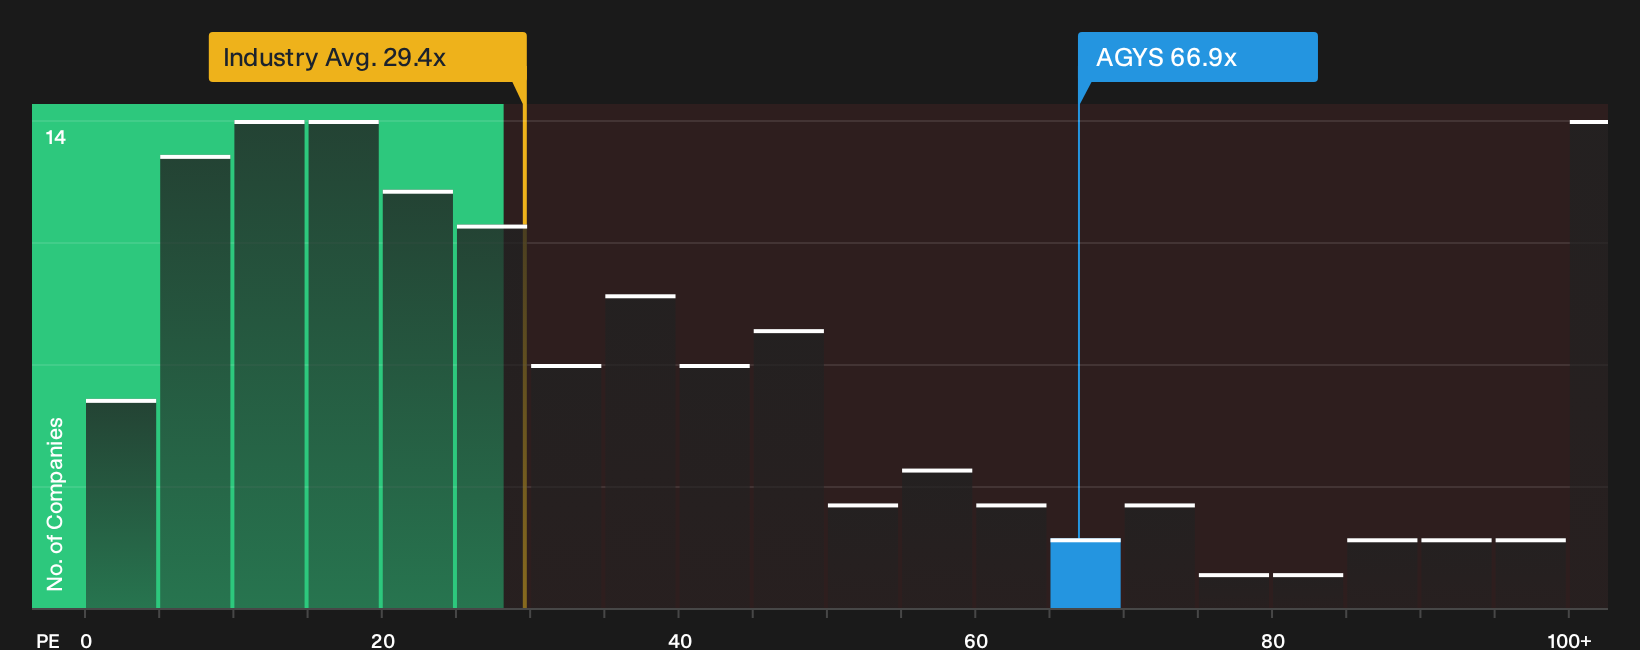
On earnings multiples, Agilysys tells a very different story. The stock trades on a P/E of 66.9x versus 42.6x for peers and 29.4x for the wider US Software group, while the fair ratio sits at 32.1x. That is around double the level the market could move toward, so is this a quality premium or valuation risk building up?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Agilysys can feel messy, yet the data is all there for you to weigh both sides and move fast on your own view. To balance the optimism against the concerns in a single snapshot, start with 4 key rewards and 1 important warning sign.
Looking For More Agilysys-Sized Ideas?
Do not stop with Agilysys when the next wave of opportunities could already be lining up on your screen. Use focused stock lists to quickly pressure test fresh ideas, compare quality signals and sharpen where your capital goes next.
- Search for potentially attractive opportunities by scanning a curated set of underpriced quality stocks through 29 high quality undervalued stocks that meet strict cash flow and balance sheet checks.
- Build a core of income-focused positions by reviewing a focused group of high yield opportunities using 8 dividend fortresses that pair income with financial resilience.
- Reduce the risk of negative surprises by filtering for financially robust businesses via the list of solid balance sheet and fundamentals (25 results) so sudden shocks are less likely to catch you off guard.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com