
Is Rollins (ROL) Fully Valued As Its Share Price Slide Sparks A Debate?
Rollins (ROL) has been drawing attention after a period of weaker share performance, with the stock down 14% over the past month and 31% in the past 3 months.
That short-term slide comes after a much tougher run for Rollins, with the share price return down sharply over the year and long-term total shareholder returns also under pressure. This points to momentum that has clearly faded rather than built lately.
Scan for other Rollins style service businesses under pressure and ready for a potential sentiment shift with our curated list of 29 high quality undervalued stocks.
Rollins has seen share price weakness while revenue and net income figures remain positive, which puts the recent slide in a different light. Is this about business fundamentals falling short, or sentiment resetting and pulling valuation back?
Most Popular Narrative: 90.6% Overvalued
Rollins closed at $30.87, while the most followed valuation story on Simply Wall St pins fair value at $16.20, which frames the recent share price weakness very differently from a pure momentum story.
Rollins is the dominant pure-play compounder in global pest control, a structurally necessary, recession-resistant service business that has grown revenue for 24 consecutive years and delivered ROIC of 23 to 31% for 12 consecutive years, without a single year of ROIC below 21% even through COVID-19. The investment thesis rests on three mutually reinforcing pillars: (1) a Wide Moat rooted in switching costs, commercial customers cannot switch providers without triggering compliance risk, and residential customers renew habitually at annual price increases of 3 to 4% above CPI without meaningful churn; (2) a proven M&A flywheel that converts a fragmented industry of 34,000+ U.S. operators into compounding route density and FCF, completing 30 to 45 bolt-on acquisitions annually at disciplined multiples with zero reported impairments; and (3) a capital-light business model with minimal reinvestment needs, generating FCF of $678M in FY2025 on $3.76B of revenue.
See why 10 investors see Rollins as 91% overvalued.
Result: Fair Value of $16.20 (OVERVALUED)
Still, the Rollins story could be knocked off course if acquisition returns weaken or if pricing power in pest and termite control encounters more pushback than bullish investors currently anticipate.
Find out about the key risks to this Rollins narrative.
Another View On Rollins Valuation
The user narrative tags Rollins as 90.6% overvalued at $30.87 versus a $16.20 fair value. Our DCF model tells a very different story. On that view, the stock trades below an estimated future cash flow value of $59.09, which raises a simple question: Which valuation lens do you trust more for a service business like this?
Look into how the SWS DCF model arrives at its fair value.
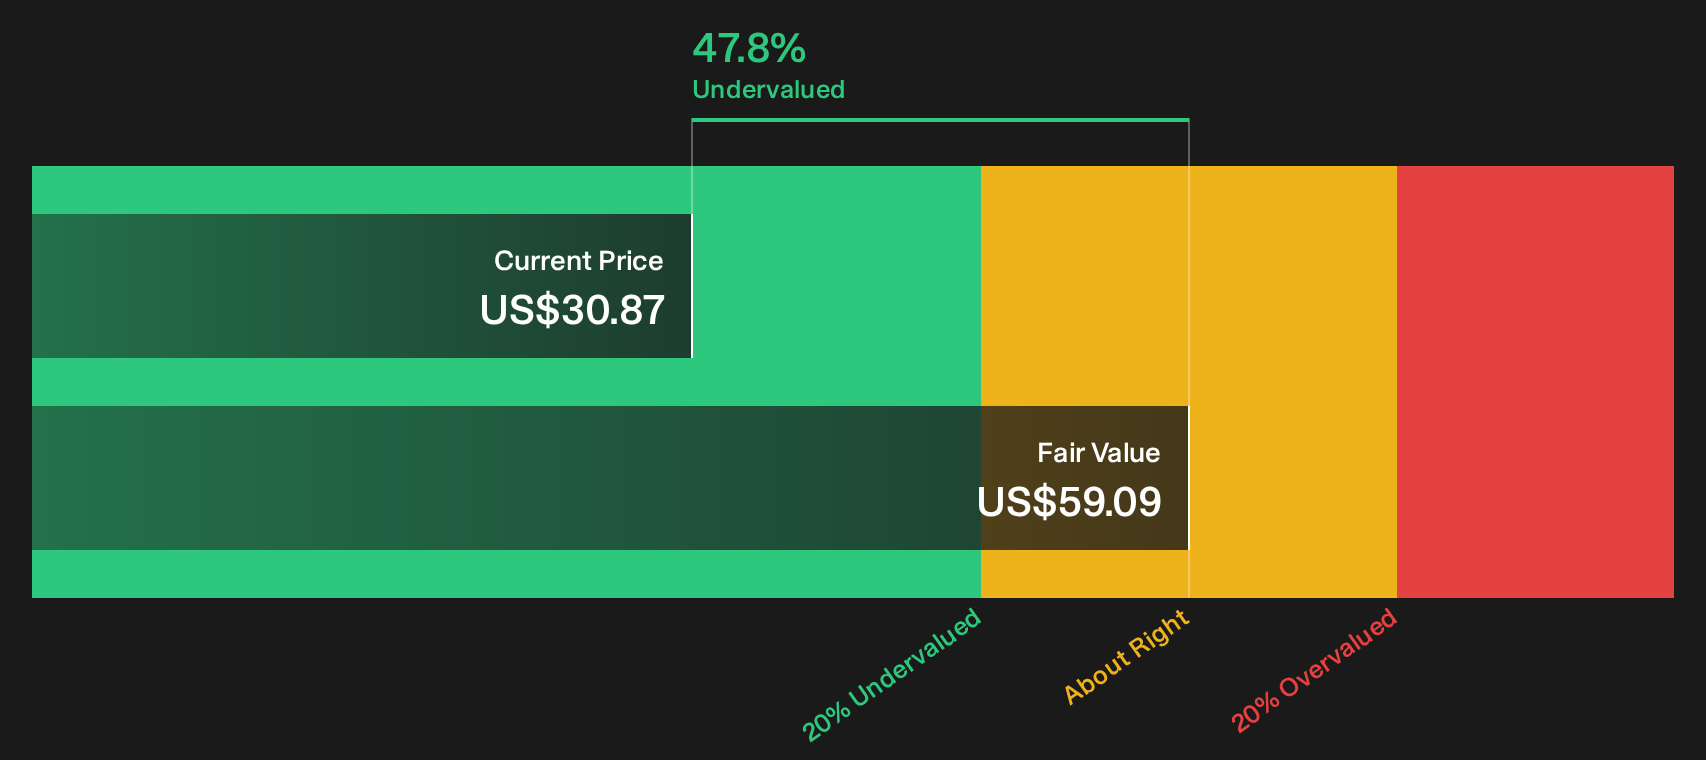
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Rollins for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed about the tone of this Rollins story so far or already leaning one way? Act now, review the full picture, and weigh both sides with 3 key rewards and 2 important warning signs.
Looking for more Rollins style investment ideas?
If Rollins has sharpened your focus on pricing power and quality, do not stop here. Broader context from other businesses can help your judgment stay grounded and balanced.
- Target steady potential by reviewing a 7 dividend fortresses that may appeal if you value income alongside stability.
- Hunt for rock solid finances through a list of solid balance sheet and fundamentals (25 results) so you are not caught holding fragile businesses when conditions turn.
- Spot the overlooked opportunities hiding in plain sight using a 20 high quality undiscovered gems before attention and pricing move on without you.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com