
Is Valvoline (VVV) Fully Priced With $500 Million In Buybacks?
Valvoline shares have been choppy over the past few years, and that uneven return profile puts a spotlight on a basic question for investors who care about earnings. Is the current US$30.73 price adequately explained by what the business is earning today and what those profits may plausibly support over time?
- Over the past 5 years the stock has fallen 11.3%, which puts pressure on the idea that long term earnings power is the main anchor for valuation.
- The board's decision to lift the share repurchase authorization to US$500 million can support per share earnings if buybacks reduce the share count meaningfully.
- There is a second opinion on Valvoline worth weighing. See what analysts think Valvoline's shares could be worth.
The stock's next move may depend on whether its current earnings profile gives enough support to the market price you see today.
To see how Valvoline's earnings story compares with other companies built on profitability, it can help to line it up against 29 high quality undervalued stocks.
Where Does Valvoline Sit on Earnings?
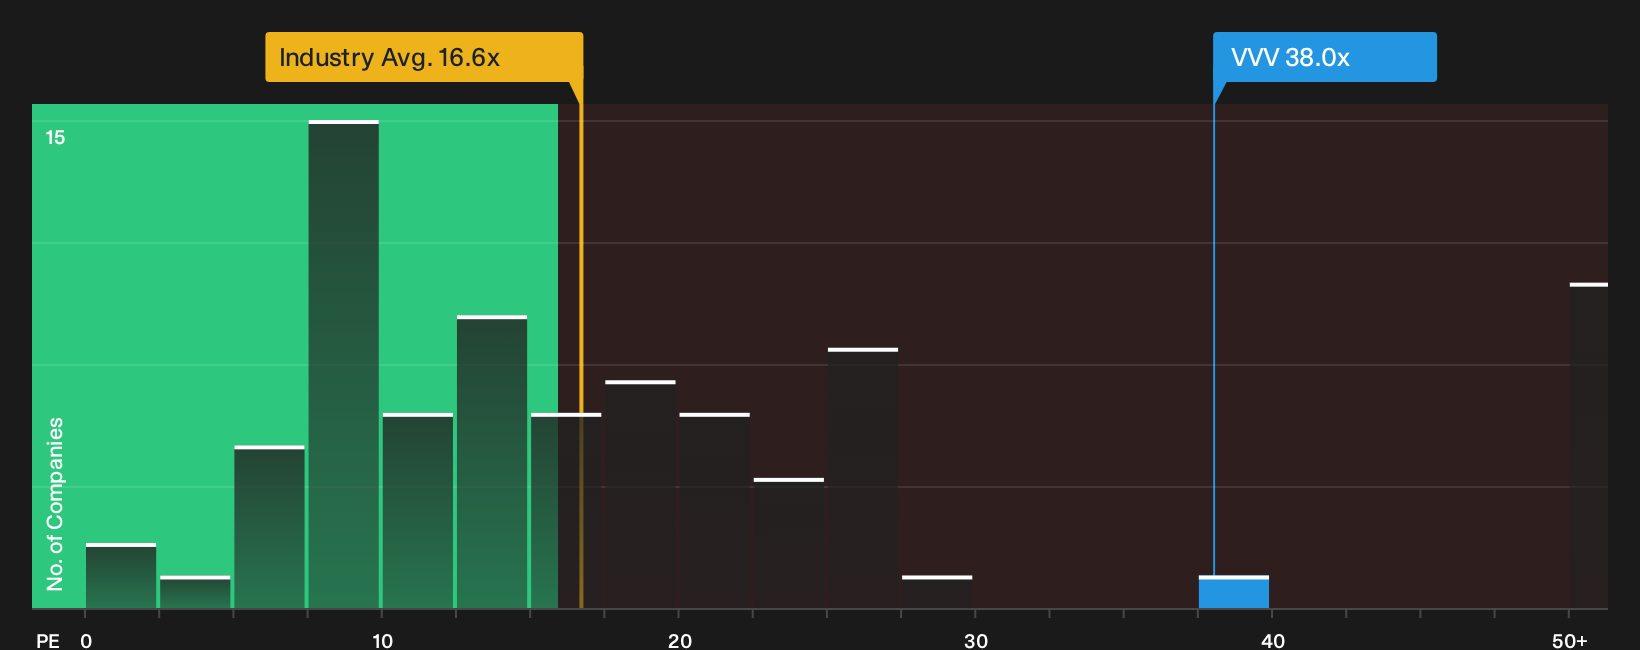
The P/E ratio suits Valvoline because earnings are now the main lens after the separation of its legacy businesses. On this metric, the stock trades on about 37.8x earnings, compared with a Specialty Retail sector average of roughly 16.6x and a peer group nearer 7.8x. That means buyers today are paying a much richer price for each dollar of Valvoline earnings than the typical competitor or sector peer.
The fair multiple implied by the model sits slightly below the current 37.8x, which points to a valuation that is about right on this framework rather than clearly cheap or clearly expensive. Because the board recently expanded the share repurchase authorization to US$500 million, the market may be treating that capital return plan as support for this elevated earnings multiple. Explore the numbers behind Valvoline's P/E valuation.
The Valvoline Narrative: What Would Justify Today's Price?
Narratives on Valvoline pick up where the P/E puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the share price to look meaningfully higher or lower than it does today, and they sit on Simply Wall St's Community page. Each one treats fair value as a hypothesis about how the business could develop so you can see over time whether that story is holding up or breaking down.
One of the top community narratives on Valvoline: 29% undervalued
"Analysts expect Valvoline to keep leaning on store expansion, premium service mix, and franchise partner growth to compound system-wide sales over time..."
Discover why this Narrative puts Valvoline at 29% undervalued.
Before you act on Valvoline's valuation, there is one more piece to examine
Numbers only tell part of the story for Valvoline, because the people setting priorities and their pay structures can shape how those earnings are pursued and shared with shareholders. See who runs Valvoline and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com