
Is Parker Hannifin (PH) Stock Cheap Or Already Priced Right?
Parker-Hannifin has been a powerful performer over the past few years, which now puts the spotlight squarely on whether the current share price lines up with the cash the business can generate. With the stock recently closing at US$952.79, the question is how that market tag compares with what its future cash flows may be worth today.
- Over the past 5 years the stock has returned 255.0%. This makes it important to test whether those gains are grounded in cash flows that can support this kind of market value.
- The company’s ability to convert its engineering and motion control operations into steady cash generation can influence how much headroom it has for investment, debt reduction, and shareholder returns. All of these factors shape any intrinsic value estimate based on its cash flows.
- What if you looked at Parker-Hannifin through its earnings instead? See why Parker-Hannifin's 32.9x P/E tells a different valuation story.
The issue now is whether Parker-Hannifin’s current share price is in line with what a Discounted Cash Flow (DCF) view of its cash streams suggests.
If you are weighing Parker-Hannifin through the lens of its cash flows and long-term share price performance, it can help to compare that story with companies surfaced by 29 high quality undervalued stocks
Is Parker-Hannifin Fairly Priced on Cash Flow?
The Discounted Cash Flow (DCF) approach here is built around how much cash Parker-Hannifin can return to shareholders over time. Over the last twelve months the group generated roughly $3.9b in free cash flow, and the model then assumes those cash profits continue to grow rather than shrink, using analyst forecasts through 2030 and longer term estimates beyond that.
Those projections show free cash flow rising into the $6.1b area by 2030, with later years stepping up more gradually, which is typical of a mature industrial business rather than an early stage story. When those future cash streams are discounted back to today, the DCF output suggests an intrinsic worth broadly in line with the current share price of $952.79. This implies the recent share performance is roughly matched by the cash the business is expected to produce. Find out what Parker-Hannifin could be worth using our Discounted Cash Flow (DCF) estimate.
The Parker-Hannifin Narrative: What Would Justify Today's Price?
Simply Wall St Narratives build on the DCF puzzle for Parker-Hannifin and outline which combinations of growth, margins and earnings paths would need to hold for the stock to appear materially richer or cheaper than today's market price, all on the Community page. Each Narrative links a specific fair value view to a clear storyline about Parker-Hannifin's potential catalysts and key risks so you can observe which version gradually aligns with reality over time.
The Parker-Hannifin community splits between those who see more runway in the current order book and cash generation, and those who think expectations already look demanding.
Bull case: 30% undervalued
"Total company orders at the end of FY26 were up 19% on a 3 month basis and 12% on a rolling 12 month basis, with backlog up 16% to US$12.8b. This gives Parker-Hannifin scope to load higher margin capacity, refine pricing and mix, and potentially sustain net margin and EPS strength for longer than current models that treat this order momentum as transitory…"
Discover why this Narrative puts Parker-Hannifin at 30% undervalued.
Bear case: 10% overvalued
"The accelerating global shift to electrification and digital solutions threatens to reduce long-term demand for Parker-Hannifin's core hydraulic and pneumatic components. This could undermine its core industrial businesses and result in ongoing revenue headwinds that persist as the market structure evolves…"
Explore why this Narrative puts Parker-Hannifin at 10% overvalued.
One more Parker-Hannifin signal to check before relying on the valuation
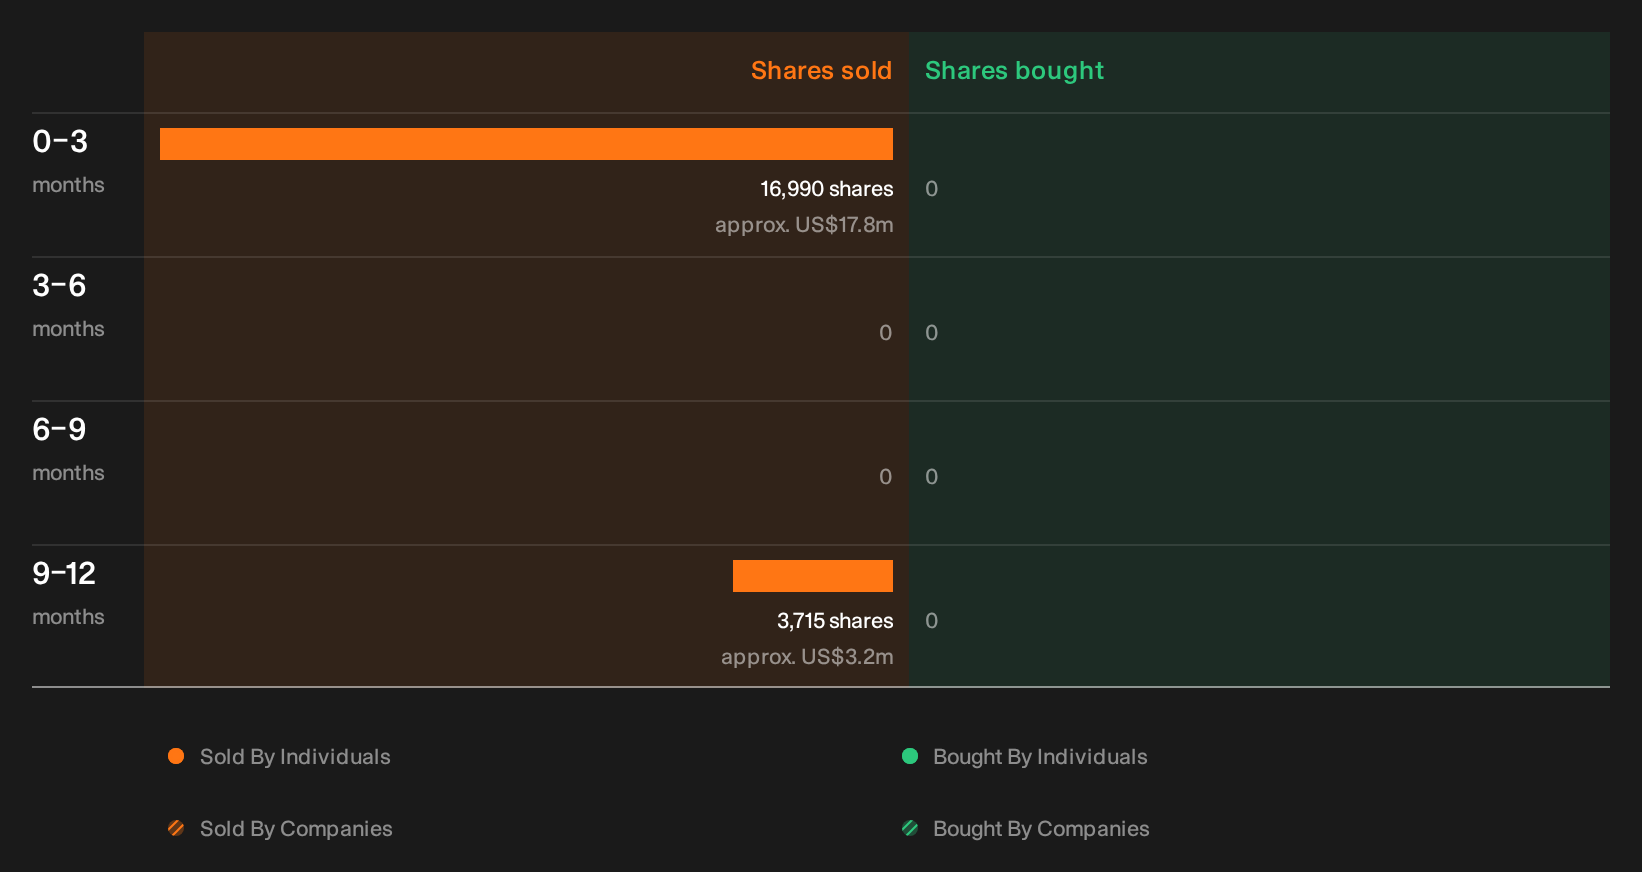
Before you lean too heavily on cash flow models and market pricing, it is worth knowing that recent insider share sales have been flagged, with the individuals, transaction sizes and possible read throughs left for you to review. See the recent insider selling flagged for Parker-Hannifin.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com