
Ultra Deep Core Sample Could Be A Key Test For Sinopec Stock
- China Petroleum & Chemical reported that the Hade-Fuman oil field in Xinjiang has already produced more than 26 million tonnes of oil and gas from deep reservoirs, supported by a recent ultra deep core sample taken from 8,080 meters in the Tarim Basin.
- This ultra deep drilling milestone gives China Petroleum & Chemical fresh geological data that can inform future development choices, capital allocation and technical risk management for similar high pressure reservoirs.
- We will now look at how this ultra deep drilling progress at Hade Fuman could influence China Petroleum & Chemical's broader investment narrative.
Review how China Petroleum & Chemical's ultra deep push compares with other energy producers tapping hard to reach resources by exploring our hand picked 17 top copper producer stocks in resource intensive sectors.
China Petroleum & Chemical Investment Narrative Recap
To own China Petroleum & Chemical, an investor needs to accept a story where shrinking gasoline and diesel demand is gradually balanced by chemicals, aviation fuels and lower carbon projects. The Hade Fuman ultra deep progress mostly reinforces that the upstream unit still matters for feedstock security. It does not materially change the near term focus on refining economics, fuel demand softness or earnings mix.
The more pressing short term swing factor remains how well utilization and margins hold up if domestic fuel demand stays weak and export controls remain tight. The biggest operational risk is heavy capital going into sustainable aviation fuel, CCUS and new energy while revenues are expected to drift lower, which could keep returns subdued if those markets take time to scale.
With no fresh market moving announcements tied directly to the Hade Fuman update, the most relevant reference point is still management’s broader push into chemicals and low carbon businesses described in recent analyst summaries. That shift matters because earnings forecasts point to profit growth despite revenue expected to edge lower, helped in part by higher value products and efficiency gains.
Against that backdrop, the ultra deep drilling milestone slots in as an operational proof point rather than a new financial driver. It helps resource access, which supports refinery flexibility and chemical feedstock supply, but investors are still likely to keep watching how projects like sustainable aviation fuel, specialty PVA capacity and CCUS cooperation convert into steadier margins while the dividend is flagged as not well covered by free cash flow.
China Petroleum & Chemical’s analyst narrative points to CN¥2,770.4b in revenue and CN¥53.5b in earnings by 2029, based on an assumption of a fairly flat top line. This implies consensus earnings moving up from CN¥35.3b today by about CN¥18.2b over that period.
Uncover why China Petroleum & Chemical's fair value indicates a 15% potential upside to its current price that may not last much longer.
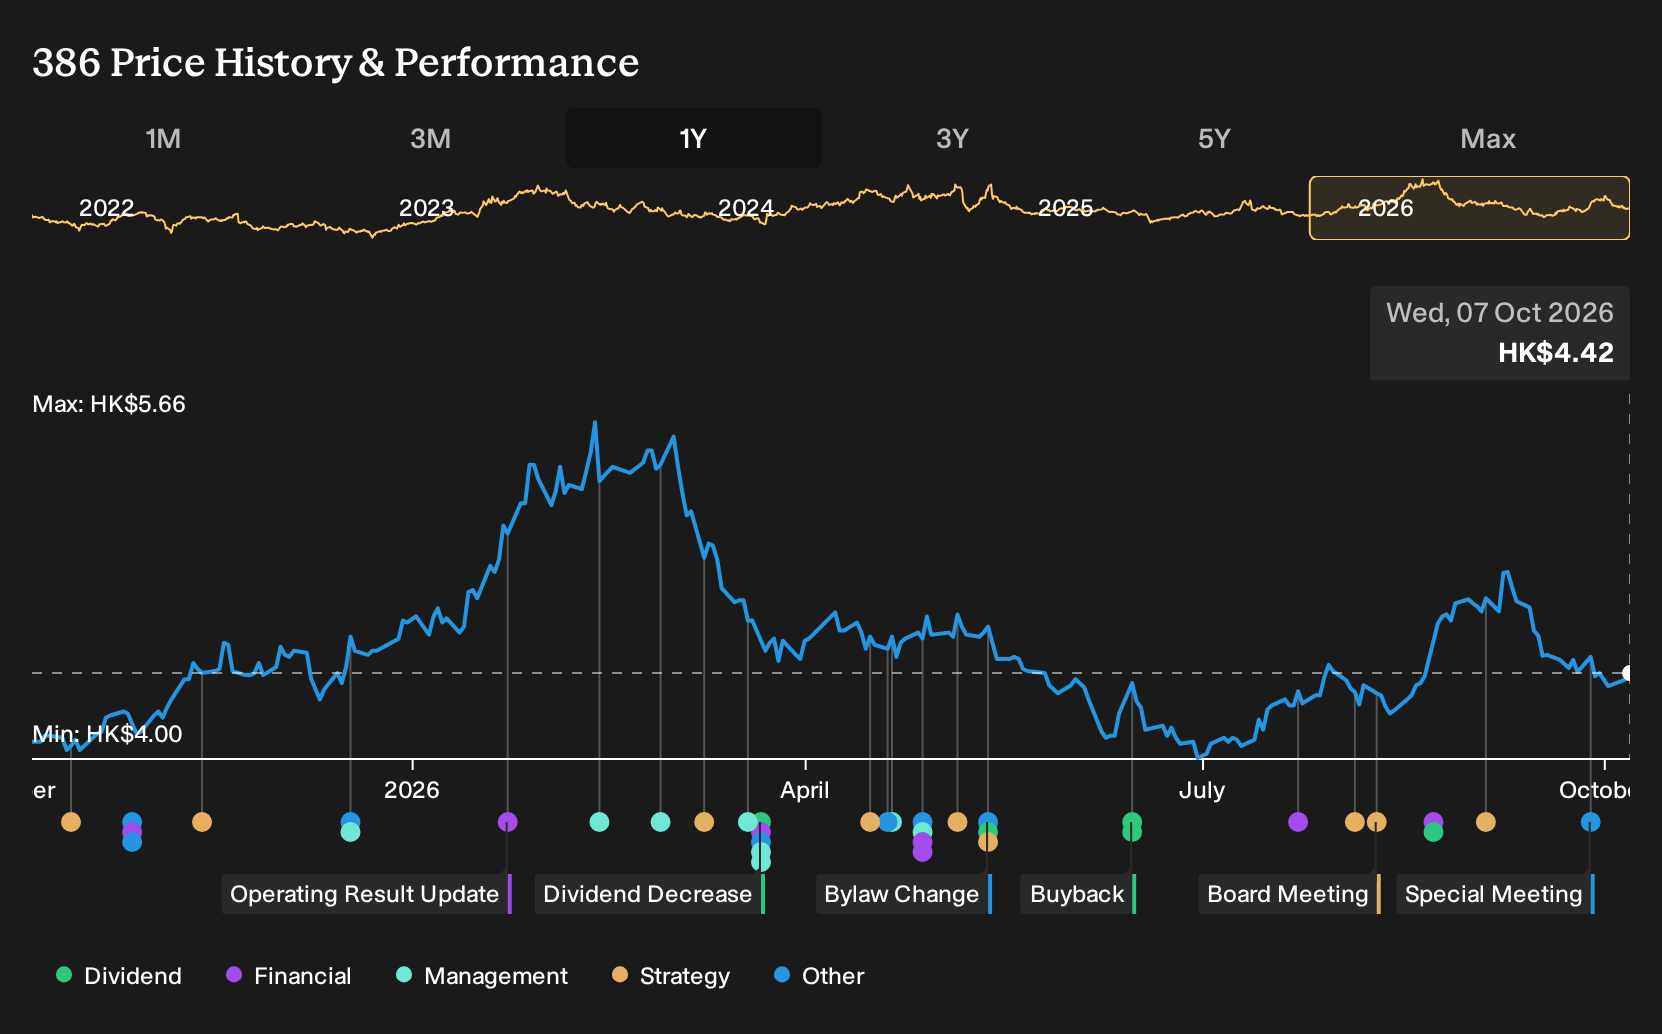
Exploring Other Perspectives
Some of the most optimistic analysts on China Petroleum & Chemical focus on a different catalyst. They lean into the potential scale of low carbon and aviation projects, which underpins their pre news forecasts of CN¥3,185.4b in revenue and CN¥90.0b in earnings by 2029. You can compare that brighter scenario with more cautious views and decide which assumptions feel reasonable to you.
Explore 4 other China Petroleum & Chemical fair value estimates, including one that suggests as much as 3475075599255% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your China Petroleum & Chemical research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for China Petroleum & Chemical. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate China Petroleum & Chemical's overall financial health at a glance.
Looking for more investment ideas beyond China Petroleum & Chemical?
If the China Petroleum & Chemical story has sharpened your thinking but you want a broader watchlist, the Simply Wall St Screener can help you quickly sort through thousands of companies using the same kind of fundamentals driven lens used here.
- If capital preservation is high on your list, start with a group of 227 resilient stocks with low risk scores that score well on resilience and risk controls.
- If you are hunting for quality at a measured price, filter for companies in the 620 high quality undiscovered gems that pair solid fundamentals with less crowded ownership.
- If balance sheet strength matters most to you, build a shortlist from the list of solid balance sheet and fundamentals (206 results) and compare how they stack up against China Petroleum & Chemical on leverage and funding flexibility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com