
Does Carnival (CCL) Look Undervalued After Its New Funding Flexibility?
Carnival has delivered a very strong 3 year share price recovery, yet the real question for investors now is whether that move is matched by the company’s earnings power. With new funding options on the table and fresh product initiatives in the cruise brands, the current US$26.15 price invites a closer look at what buyers today are actually paying for in terms of profits.
- The stock has gained 110.0% over 3 years, which puts more weight on whether the current valuation is adequately backed by Carnival’s earnings profile.
- The broad new shelf registration and ongoing fleet and technology projects can influence future interest costs, cash flow timing and the level of earnings needed to support any additional capital raising.
- There is a second opinion on Carnival worth weighing. See what analysts think Carnival's shares could be worth.
The issue now is whether Carnival’s recent share price level is justified by what the business is earning today and is expected to earn over time.
If you are weighing whether Carnival's US$26.15 price fits its earnings profile, it can help to compare that same question across 29 high quality undervalued stocks.
Does Carnival Look Undervalued on Earnings?
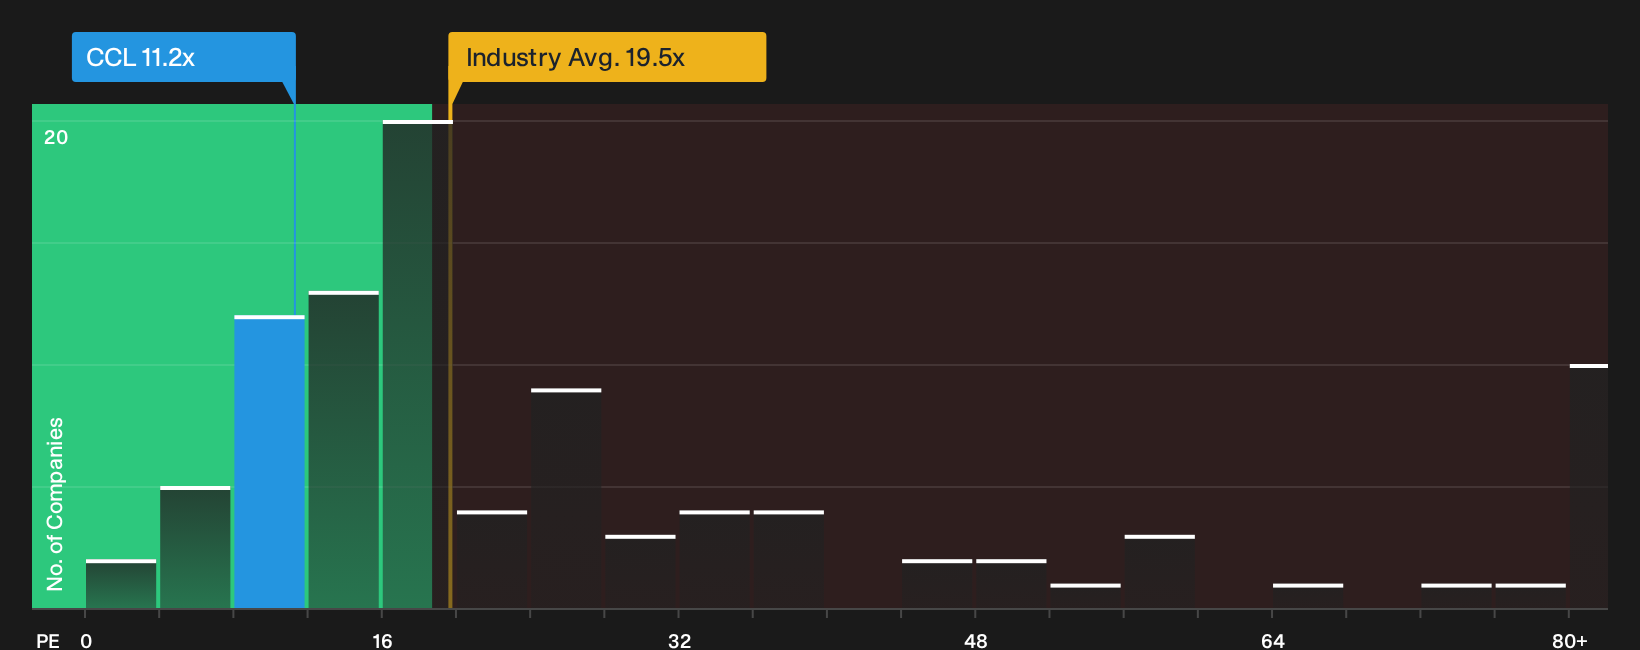
The P/E ratio is a useful lens for Carnival because earnings are now a key driver of how the market weighs its recovery story. At a P/E of 11.2x, the stock trades well below both the hospitality industry average of 19.5x and the peer group on about 23.6x. That gap means buyers today are paying a lower price for each dollar of reported profit compared with many listed travel and leisure companies.
Because the Fair Ratio incorporates Carnival’s margins, growth profile, size and risk into a single benchmark, the current 11.2x sits under where that model would expect the shares to trade. Despite the new omnibus shelf registration giving Carnival more room to issue equity or debt when needed, the P/E still points to a discounted earnings multiple against both peers and this tailored yardstick. Explore the numbers behind Carnival's P/E valuation.
The Carnival Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Carnival's valuation puzzle leaves off by spelling out what would need to happen to future growth, margins and earnings for the stock to be worth significantly more or meaningfully less than today’s price, using the Community page as the home for those scenarios. Each narrative treats fair value as a concrete, trackable idea about how Carnival's business might develop, rather than a one-off snapshot that never gets revisited.
One of the top community narratives on Carnival: 23% undervalued
"Expansion of unique private destinations, innovative loyalty programs, and modernized ships strengthens guest experience, pricing power, and supports sustained revenue and margin growth..."
Discover why this Narrative puts Carnival at 23% undervalued.
One more Carnival question before you act on the valuation
Analyst projections give you a different lens on where earnings and cash generation might head over the next few years, which you can set against today’s pricing before making any move. Explore where analysts expect Carnival to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com