
Domino's Pizza (DPZ) Could Be 26% Undervalued As Earnings Optimism Builds
Growing optimism around Domino's Pizza (DPZ) ahead of its September 2026 quarterly report has become the main story for this stock, with expectations centered on higher earnings and revenue.
Recent trading reflects that optimism colliding with a tougher year. Domino's Pizza has a 1-day share price return of 1.88% and a 7-day gain of 1.09%, yet the 30-day share price return is down 11.20% and the year-to-date share price return is down 28.78%. The 1-year total shareholder return has declined 25.17%, so short-term momentum is perking up against a weaker longer-term picture as investors weigh the upcoming earnings report against those past drawdowns.
Capitalize on the renewed focus around Domino's Pizza earnings by lining up your next ideas from a hand-picked group of 27 high quality undervalued stocks.That recent slide against bullish analyst targets leaves Domino's Pizza trading at a discount to consensus fair value. Is that gap a genuine opportunity, or is the market correctly pricing in risk ahead of earnings?
Most Popular Narrative: 26% Undervalued
On the latest narrative view, Domino's Pizza carries an estimated fair value of $408.07 against a last close of $302.87, which frames the current optimism as investors wait to see whether the upcoming earnings report narrows that gap or challenges it.
Domino's Pizza is a great brand, enjoying a wide moat that results in an operating margin of around ~20%. Given the maturity of the business, its revenue growth is below 10% but still modestly above the economy growth rate. Its franchise business model and disciplined capital allocation decisions also result in a stellar ROIC around 10 times its cost of capital. The reduction in shares outstanding over the last five years has also increased each shareholder's ownership stake ("pizza slice") in the company.
See why 12 investors see Domino's Pizza as 26% undervalued.
Result: Fair Value of $408.07 (UNDERVALUED)
Still, the Domino's Pizza story can break if franchise health weakens or if consumer demand softens, which could pressure margins and challenge these valuation assumptions.
Find out about the key risks to this Domino's Pizza narrative.
Another View On Domino's Pizza Valuation
That 26% undervalued narrative leans on user assumptions and blended methods. Our DCF model paints a cooler picture, with a future cash flow value of $281.96 against the current $302.87 price, which points to Domino's Pizza trading above that estimate and raises the possibility that optimism is already baked in.
Investors can use this gap between user-driven fair value and the SWS DCF model as a prompt to stress test their own assumptions on margins, growth and discount rates. They can then decide which framework feels more realistic for Domino's Pizza over the next decade, or whether both are missing something important in the story.Look into how the SWS DCF model arrives at its fair value.
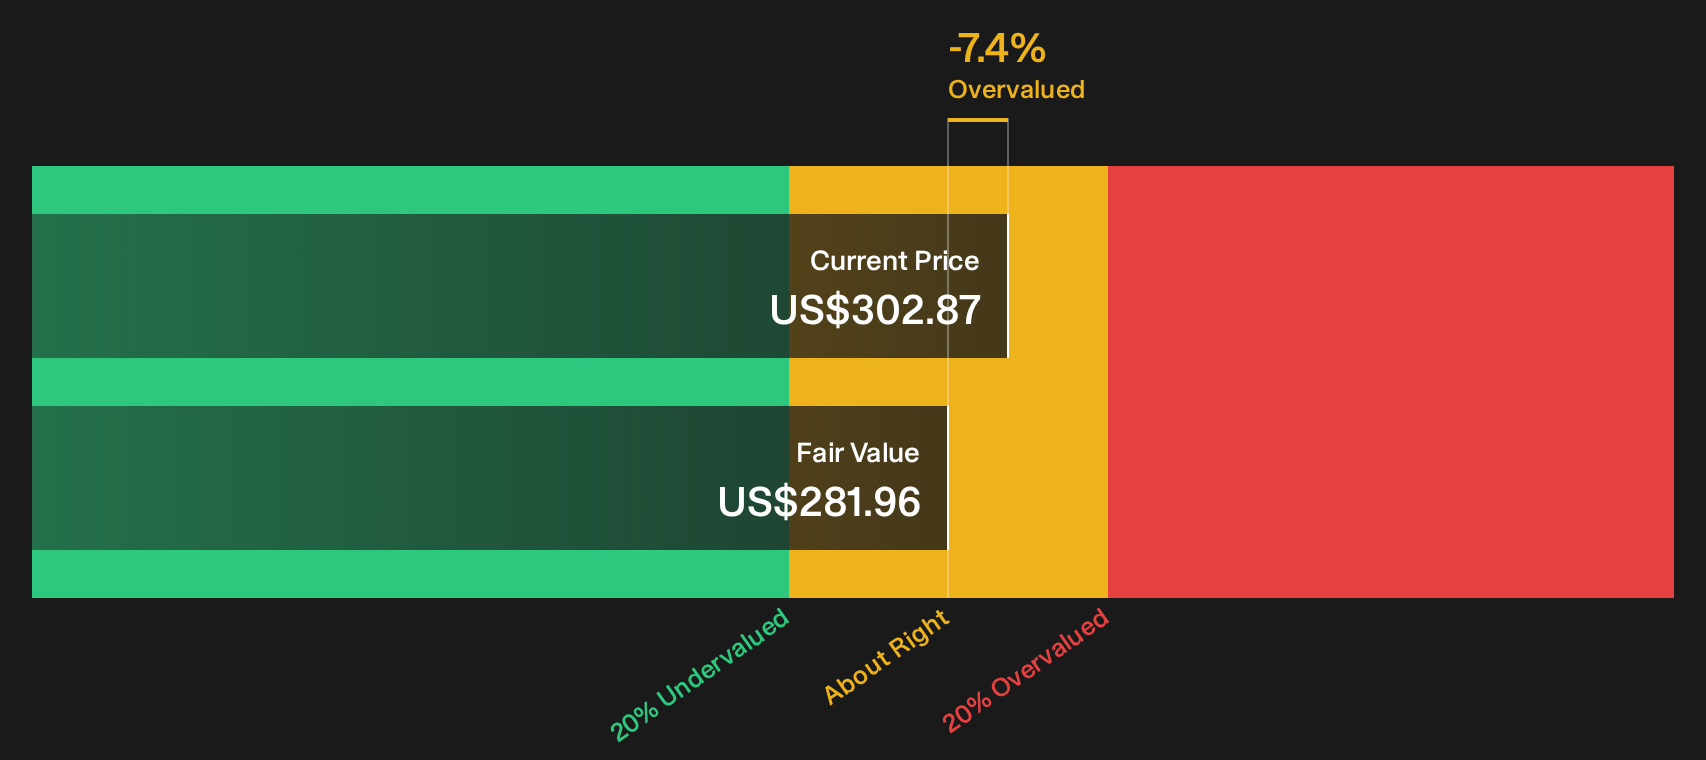
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Domino's Pizza for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling the crosscurrents in sentiment around Domino's Pizza earnings and valuation and want your own read rather than the crowd's mood? Move quickly through the underlying data, then weigh up the 5 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Domino's Pizza?
If Domino's Pizza has your attention, broaden your watchlist with fresh ideas so you are not relying on a single story to carry your portfolio.
- Spot potential turnaround stories early by reviewing the 11 elite penny stocks with strong financials that already show stronger financial footing than many investors expect.
- Strengthen your core holdings by scanning the list of solid balance sheet and fundamentals (25 results) that can add more financial resilience to your overall mix.
- Hunt for future leaders by checking the 19 high quality undiscovered gems before a wider crowd starts paying attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com