
Tyler Technologies (TYL) Could Be 39% Below Fair Value After South Carolina DMV Deal
Why Tyler Technologies’ new South Carolina DMV deal matters for shareholders
Tyler Technologies (TYL) just extended its 21 year relationship with the South Carolina Department of Motor Vehicles, as the agency moves vehicle titling onto Tyler’s fully digital workflow under the state’s existing Digital Government Services contract.
The rollout shifts a paper heavy process into an electronic system that can handle titles in about 24 hours, deepening Tyler Technologies’ role in day to day transactions between SCDMV, auto dealers and lenders.
Despite this fresh South Carolina win, Tyler Technologies’ share price has fallen 24.07% year to date and the 1-year total shareholder return is down 31.87%, even though the 90-day share price return of 5.29% hints at some rebuilding momentum.
Spot under pressure like Tyler Technologies and scan a curated group of 27 high quality undervalued stocks with solid cash flows and balance sheets that could be setting up for a rebound.Tyler Technologies now pairs a long running DMV contract with a share price that has pulled back hard, then started to flicker higher. Does that mix of contract depth and recent volatility still tilt the risk reward toward buyers, once valuation is on the table?
Most Popular Narrative: 128.3% Overvalued
Tyler Technologies last closed at $330.91, while the most followed valuation story on Simply Wall St pegs fair value at $144.97, which frames the current share price as rich relative to that estimate and puts extra weight on how durable the underlying cash flows really are.
Tyler Technologies is the dominant software platform for U.S. state and local government, a market defined by mission-critical workflows, 12–24 month implementation cycles and a procurement environment that structurally protects incumbents. The investment thesis is built on three compounding forces: (1) a largely complete SaaS cloud transition that is converting a high-gross-margin subscription base from flat to accelerating, with ARR already at $2.06B and growing 11% annually; (2) a payments platform (NIC) that turns Tyler’s 40,000+ client relationships into a recurring transaction revenue stream now generating $808M per year and growing at double digits; and (3) a Tyler 2030 strategic roadmap that articulates a credible path to 30%+ non-GAAP operating margins by the end of the decade.
See why 8 investors see Tyler Technologies as 128% overvalued.
Result: Fair Value of $144.97 (OVERVALUED)
Still, the Tyler Technologies story can break if the on premises to cloud migration stalls or if stock based compensation continues to erode the quality of free cash flow.
Find out about the key risks to this Tyler Technologies narrative.
Another view on Tyler Technologies’ valuation
The user narrative frames Tyler Technologies as 128.3% overvalued at $330.91 versus a $144.97 estimate. Our DCF model tells a different story. It values the stock at $538.89, which implies the current quote trades about 38.6% below that future cash flow estimate. Which lens should carry more weight for you?
Before leaning on either story too heavily, it is worth understanding how the cash flow inputs and discount rates work inside the SWS DCF model, and where they might be more fragile or more conservative than they look at first glance. Look into how the SWS DCF model arrives at its fair value.
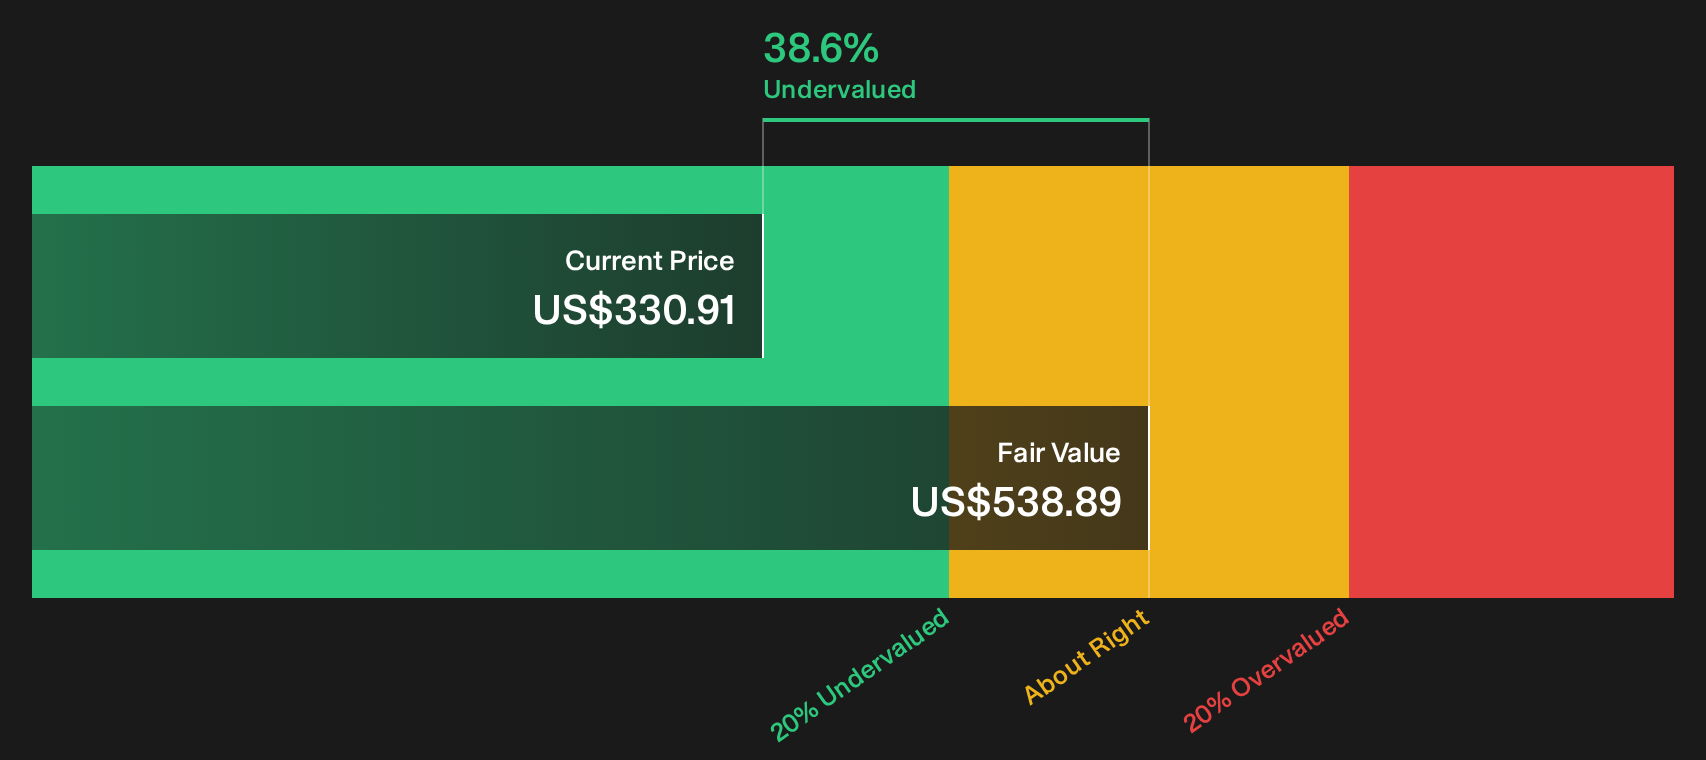
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Tyler Technologies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed views like these only matter if you test them against your own reading of the facts. Move quickly, review the details and weigh the 4 key rewards.
Looking for more Tyler Technologies sized investing ideas?
If you only focus on Tyler Technologies, you could miss other opportunities that match your risk, income, and quality preferences across the wider market.
- Target potential rebound candidates by scanning a curated group of beaten down quality stocks through the 27 high quality undervalued stocks.
- Strengthen the defensive side of your portfolio by reviewing a list of solid balance sheet and fundamentals (25 results) that can better handle financial shocks.
- Hunt for future standouts before they hit headlines by checking a focused set of 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com