
Hope Bancorp (HOPE), What Is Behind The Fresh Attention Now?
Hope Bancorp (HOPE) has drawn fresh attention after Zacks raised its rating to Rank #2, reflecting higher earnings estimates and renewed interest in how the regional lender is being valued.
Recent news has landed on top of a strong run for Hope Bancorp, with the share price at US$13.48 and a year-to-date share price return of 22.77%. The 1-year total shareholder return of 27.93% points to momentum that has been building rather than fading.
Scan how Hope Bancorp compares with other regional lenders that show strong fundamentals and momentum by reviewing the hand-picked 19 high quality undiscovered gems in this corner of the market.
The recent climb in Hope Bancorp shares puts investors at a simple decision point. Is the current price already fair for the progress so far, or does the valuation still leave enough cushion to justify buying now instead of waiting?
Most Popular Narrative: 13% Undervalued
Hope Bancorp is priced at $13.48 while the most followed narrative framework points to a fair value of $15.50. This puts the focus firmly on whether recent earnings momentum and bank acquisitions can justify that gap.
The valuation suggests that the market remains cautious about Hope Bancorp’s ability to turn current loan, revenue, and efficiency progress into stronger long term shareholder value, given its historically flat net interest income, declining EPS, and plateaued tangible book value per share.
See why 8 investors see Hope Bancorp as 13% undervalued.
Result: Fair Value of $15.50 (UNDERVALUED)
Still, the story around Hope Bancorp can change quickly if commercial real estate credit issues escalate or regional shocks in California and Hawaii affect earnings expectations.
Find out about the key risks to this Hope Bancorp narrative.
Another View On Hope Bancorp’s Valuation
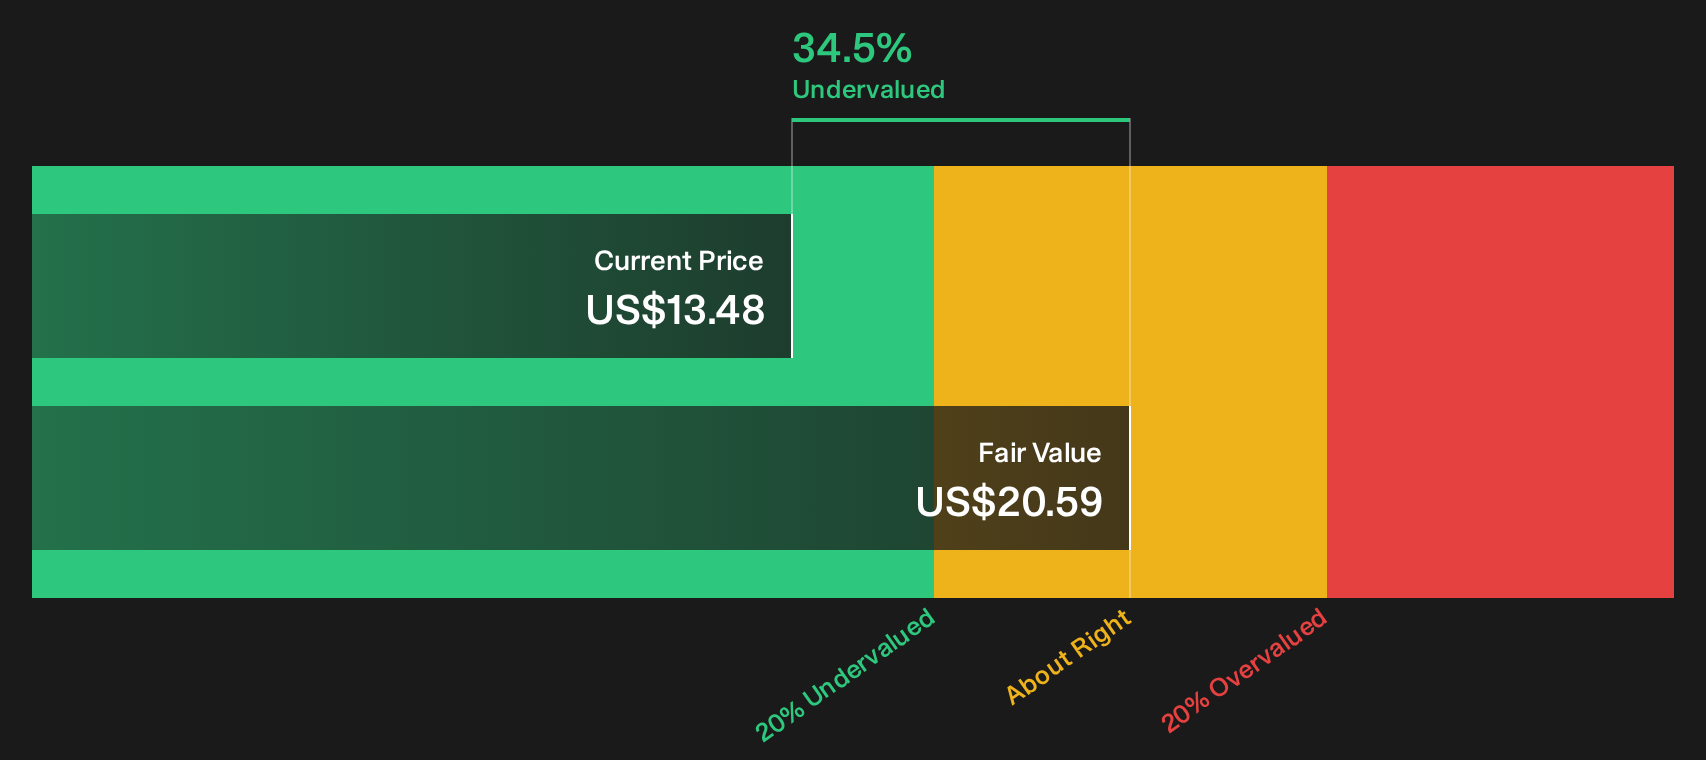
On earnings power and fair value, Hope Bancorp looks inexpensive, with the stock at $13.48 and Simply Wall St estimating future cash flows at $20.59. That implies the SWS DCF model also points to an undervalued share price. The question is whether you trust the cash flow path that sits underneath that gap.
To see how that cash flow based view is built and stress test the inputs against your own expectations, start with the Look into how the SWS DCF model arrives at its fair value..
Next Steps
Mixed messages on Hope Bancorp’s valuation and risk profile can feel uncomfortable, so act while the data is fresh and decide where you stand. To weigh both the upside potential and the issues flagged by the market, start with the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Hope Bancorp?
Do not stop with Hope Bancorp if you want a broader watchlist. Use the Simply Wall St screener tools to surface fresh ideas that match your style.
- Target higher potential upside by reviewing the 27 high quality undervalued stocks that combine strong fundamentals with prices that may not fully reflect their financial profile.
- Strengthen your income stream by scanning the 8 dividend fortresses that focus on companies offering higher yields backed by real business cash flows.
- Prioritise resilience by filtering for the 31 resilient stocks with low risk scores that place balance sheet strength and lower risk scores at the centre of the selection.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com