
Bank of Hawaii (BOH) Could Be 22% Undervalued Following Preferred Dividend Declaration
Bank of Hawaii (BOH) has put fresh attention on its capital structure after the board declared quarterly dividends on its Series A and Series B preferred shares, both payable on November 2, 2026.
At a share price of US$67.30, Bank of Hawaii has seen its short-term share price momentum fade, with the stock down 12.81% over the past month and 16.84% over the past quarter. This contrasts with the 1-year total shareholder return of 6.91% and 3-year total shareholder return of 52.76%, which point to a much stronger longer-term outcome.
Compare Bank of Hawaii's recent pullback and income profile against a hand picked 8 dividend fortresses that also pair meaningful yields with established businesses.
The question for Bank of Hawaii now is whether this pullback already reflects the risk around its income profile, or if patience could offer a clearer entry based on valuation.
Most Popular Narrative: 22% Undervalued
Compared with the latest fair value estimate of $86.67, Bank of Hawaii at $67.30 screens as materially cheaper on this narrative view. This frames the recent pullback against longer term earnings power and capital returns.
Deepening customer relationships and expansion in wealth management and trust services are leveraging the aging and increasingly affluent population, resulting in steady growth of non-interest (fee) income and greater revenue diversification. Ongoing digital transformation and sustained investments in digital banking platforms are expected to enhance operational efficiency, improve customer acquisition and retention, and support controlled expense growth, boosting long-term net margins.
See why 2 investors see Bank of Hawaii as 22% undervalued.
Result: Fair Value of $86.67 (UNDERVALUED)
Still, the Bank of Hawaii narrative relies heavily on Hawaiian real estate and a concentrated local loan book, so any property downturn or funding cost pressure could quickly challenge it.
Find out about the key risks to this Bank of Hawaii narrative.
Another View on Bank of Hawaii’s Valuation
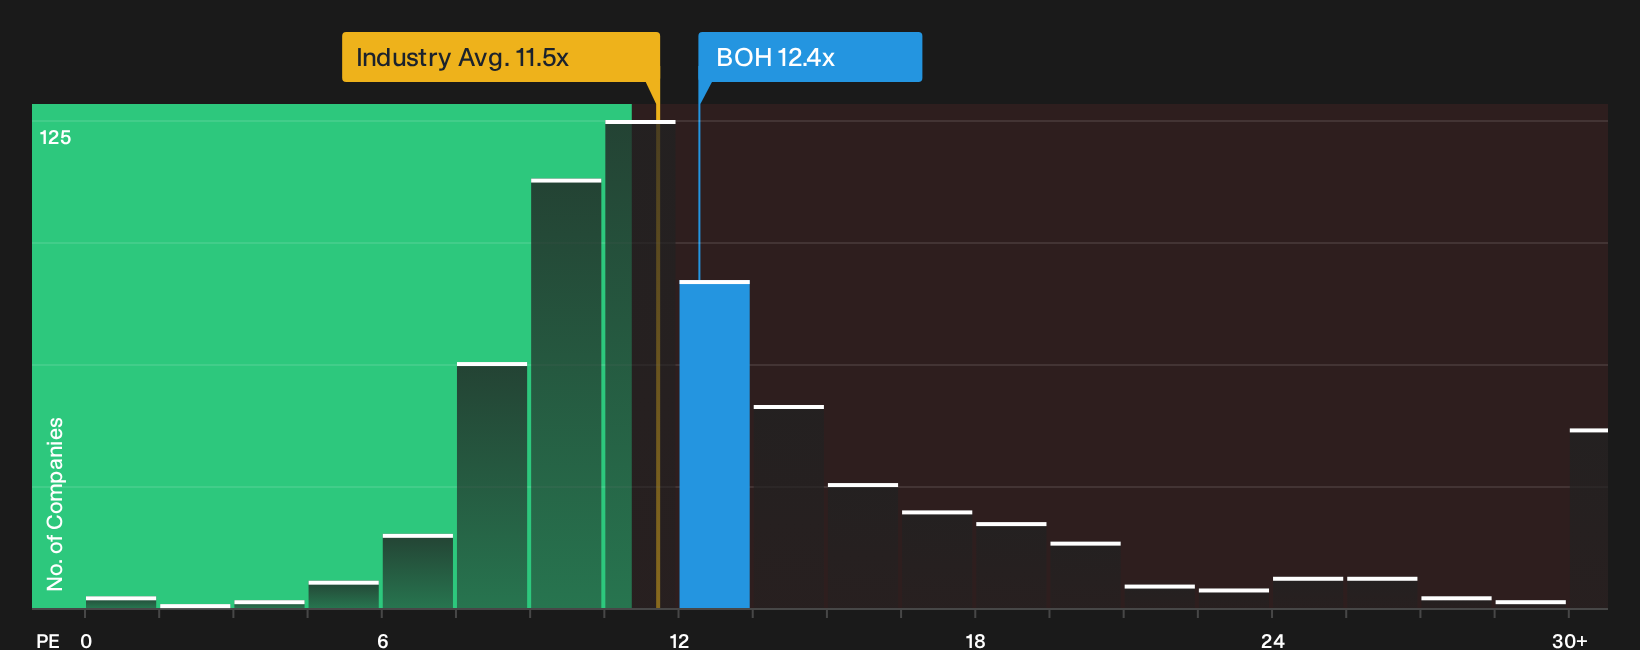
The earlier fair value work leans on detailed earnings forecasts and discounting. A simpler P/E check paints a different picture. Bank of Hawaii trades at 12.4x earnings, above the US Banks industry at 11.5x, yet right in line with its fair ratio of 12.4x. This suggests far less obvious upside baked into this lens.
Against peers on 23.6x, the stock screens much cheaper. The practical question for you is whether that gap indicates mispricing or simply reflects the extra concentration and growth risks already on display.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Bank of Hawaii so far. If you want to act before sentiment settles, weigh the trade off between those risks and rewards using the 5 key rewards and 1 important warning sign.
Ready for more ideas beyond Bank of Hawaii?
If Bank of Hawaii has sharpened your focus on price, income and risk, do not stop here. Broader ideas can help you build a stronger portfolio mix.
- Target resilient income by scanning a curated 8 dividend fortresses that aim to balance payout potential with business durability.
- Hunt for potential mispriced opportunities through a focused 27 high quality undervalued stocks tailored to highlight quality alongside attractive valuations.
- Protect your downside by reviewing a 31 resilient stocks with low risk scores that concentrates on balance sheet strength and more measured risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com