
CrowdStrike (CRWD) Stock May Look Fully Valued Despite AI Security News
CrowdStrike Holdings has delivered very strong share price gains over the past few years, and that kind of run naturally prompts a closer look at whether the current valuation still lines up with what its balance sheet shows. With investors digesting fresh headlines about its AI security push and partnerships, the question now is how much today’s price can be anchored in the company’s book value.
- Over the past 3 years, CrowdStrike’s share price has risen by about 4.9x, which raises the question of how much support its book value provides for the current market valuation.
- Recent news around leadership positions in endpoint security, new AI focused partnerships, and expanded programs with large technology platforms may support expectations for more capital efficient growth, which can influence how investors weigh the stock’s price against its underlying net assets.
- Your read on CrowdStrike Holdings is one view; the desks covering it have another. See what analysts think CrowdStrike Holdings's shares could be worth.
The issue now is whether CrowdStrike’s current market price is adequately supported by its book value when compared with the industry average.
If you want to test the same book value question beyond CrowdStrike Holdings, you can scan a wider set of cybersecurity and AI infrastructure names using 92 AI infrastructure stocks.
Is CrowdStrike Holdings Getting Expensive on Book Value?
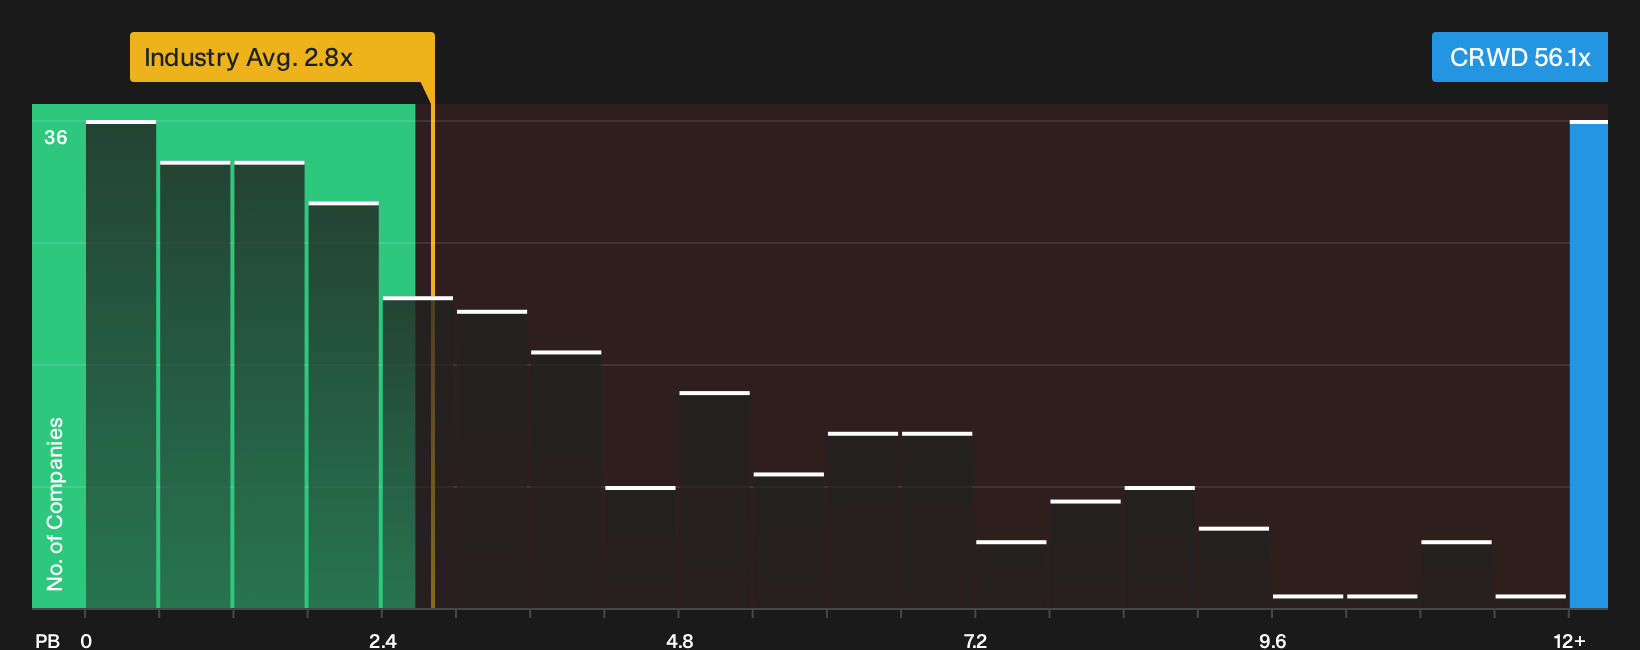
The price to book ratio fits CrowdStrike Holdings reasonably well because much of the debate focuses on how far its market value extends beyond the accounting value of its net assets. On this measure, the stock trades on a P/B of about 56.1x, compared with an industry average near 2.8x and a peer group around 30.4x. That is a big gap, which signals that buyers are paying a very large premium over the company’s book value relative to typical software peers.
Because the IDC MarketScape recognition and a series of AI focused partnerships have lifted expectations around CrowdStrike’s position in security, the market multiple now reflects a broader narrative than the balance sheet alone. At this kind of P/B, any investor weighing the shares is effectively assuming that future returns on the existing equity base will justify a much higher valuation than is common in the sector. This leaves much less room for disappointment. Explore the numbers behind CrowdStrike Holdings's P/B valuation.
The CrowdStrike Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for CrowdStrike Holdings pick up where this valuation puzzle leaves off by spelling out which future growth, margin and earnings paths would need to play out for the stock to be worth materially more or less than today’s price on the Community page. Each one sets out CrowdStrike Holdings' fair value as a thesis about how the business might perform over time so you can see how that view holds up as new information arrives.
Community views on CrowdStrike Holdings are split between AI security opening more upside and today’s price already baking in very high expectations.
Bull case: 7% undervalued
"The earlier view that CrowdStrike Holdings could become the default shield for AI agents now rests on quantified AI security estimates, with management pointing to an expected US$215b opportunity by 2034 and the possibility that a few points of share would translate into several billions of ARR…"
Discover why this Narrative puts CrowdStrike Holdings at 7% undervalued.
Bear case: 18% overvalued
"The current valuation reflects a share price that, according to this narrative, already assumes CrowdStrike achieves multi billion dollar ARR contributions from newer businesses such as AI security, next generation SIEM, identity and cloud security, together with high free cash flow margins, and characterizes the shares as overvalued and bearish…"
Explore why this Narrative puts CrowdStrike Holdings at 18% overvalued.
Before you act on CrowdStrike Holdings’ valuation, there is one more angle to check
Price ratios tell you what the market thinks, but the people actually steering CrowdStrike Holdings and the way their pay is structured can heavily influence how this story plays out. See who runs CrowdStrike Holdings and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com