
Four Corners Property Trust (FCPT) Buys Kentucky Auto Property, Is It Still 24% Undervalued?
Why this new Kentucky deal matters for Four Corners Property Trust
Four Corners Property Trust (FCPT) has moved to acquire an automotive service property in a busy Kentucky corridor for US$3.5 million through a sale leaseback with a national operator.
The site is corporate operated under a long term triple net lease, with a cap rate in line with previous FCPT transactions, which keeps the trust’s latest expansion consistent with its existing acquisition playbook.
Four Corners Property Trust’s latest Kentucky acquisition lands at a time when momentum in its stock has cooled, with a 30 day share price return down 14.56% and a year to date share price return down 8.35% from the latest close of US$21.30.
Over a longer window, investors who include dividends in their view see a different picture, with total shareholder return up 13.76% over three years even though the 1 year total shareholder return has declined 5.91%. This suggests the market has recently become more cautious on the REIT’s pipeline and income profile despite continued portfolio expansion.
Compare Four Corners Property Trust’s latest move with other real estate and income-focused opportunities by scanning our curated list of 27 high quality undervalued stocks.
Four Corners Property Trust is still buying income assets while the share price has pulled back. Is most of the upside now behind the stock, or does the current valuation still leave room for further gains?
Most Popular Narrative: 24% Undervalued
Four Corners Property Trust is priced at $21.30 while the most followed narrative anchors fair value around $28.11, which frames the current pullback as a discount rather than a full rerating.
Four Corners Property Trust is pushing ahead with portfolio diversification so that roughly 41% of rent now comes from non casual dining sectors such as medical retail, auto service and quick service restaurants. This mix can support steadier rental revenue and may help reduce earnings volatility over time.
See why 6 investors see Four Corners Property Trust as 24% undervalued.
Result: Fair Value of $28.11 (UNDERVALUED)
Still, the story can change if restaurant tenants struggle or if higher funding costs squeeze Four Corners Property Trust’s acquisition spreads and per share outcomes.
Find out about the key risks to this Four Corners Property Trust narrative.
Another View on Four Corners Property Trust’s valuation
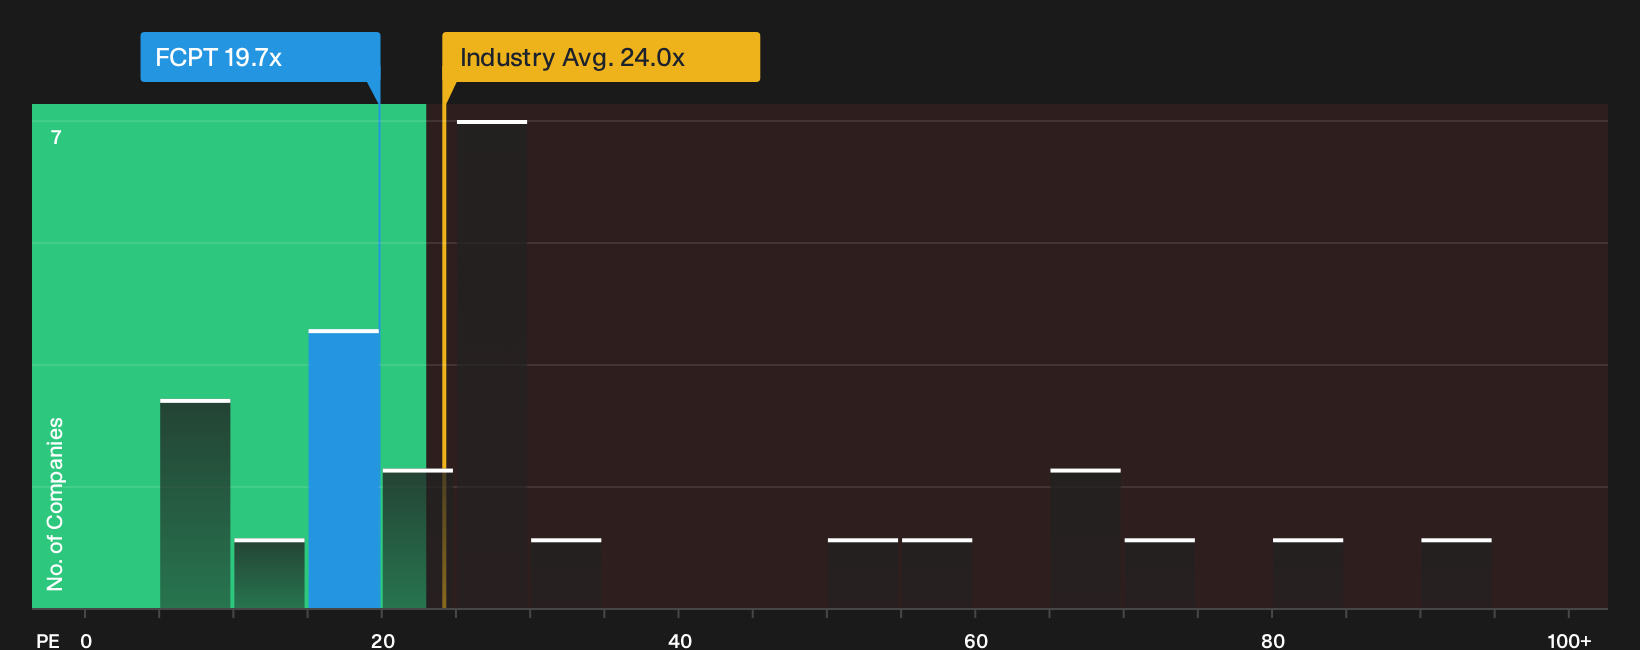
The narrative around Four Corners Property Trust leans heavily on fair value estimates well above the current $21.30 share price. Yet on a simple P/E lens of 19.7x, the stock looks expensive next to direct peers at 13.6x, even if it screens cheaper than the wider Specialized REITs group at 23.6x. With a fair ratio indicated at 31.8x, investors are left weighing whether today’s lower multiple signals room to rerate or a market that is already cautious on future returns.
For a deeper look at how those earnings multiples and the fair ratio fit together for FCPT, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Four Corners Property Trust’s valuation and risk reward profile can feel confusing, so move quickly, review the data for yourself and pressure test the assumptions that matter most to you with 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Four Corners Property Trust?
If Four Corners Property Trust has your attention, do not stop here. Fresh ideas matter. Use focused stock lists to spot opportunities others overlook.
- Target resilient balance sheets and fundamentals that can help steady your portfolio with a curated list of solid balance sheet and fundamentals (25 results).
- Hunt for quality at a potential discount by scanning a focused set of 27 high quality undervalued stocks.
- Build a cash flow focused watchlist and compare yields using a hand picked group of 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com