
Linde (LIN) Could Be 11% Undervalued On Record $8.1b Electronics Backlog
Linde (LIN) just put hard numbers behind its semiconductor ambitions by flagging a record US$8.1b electronics backlog and committing US$1b to two new air separation units tied to new chip fabs.
That semiconductor push landed in a market that has already rewarded Linde, with the share price at US$489.95 after a 1-day share price return of 1.57% and a 7-day gain of 3.50%. Momentum has picked up again following a period where the 90-day share price return declined 7.15%, although the year-to-date share price return of 14.18% and five-year total shareholder return of 77.23% suggest the longer-term performance has remained intact.
Scan beyond Linde and focus on gas suppliers and adjacent players that are participating in the same chip buildout with our curated list of 92 AI infrastructure stocks.
Linde now trades close to record levels while still sitting about 11% below the average analyst target. Is that a genuine margin of safety, or is it the premium the market demands for caution around execution and capital intensity?
Most Popular Narrative: 10% Undervalued
Linde closed at $489.95 while the most followed narrative pegs fair value at $544.40. The story hinges on whether its backlog and capital projects really translate into the cash flows that valuation implies under a 7.93% discount rate.
Linde's position supplying ultra high purity gases to large advanced node semiconductor complexes in Arizona and Taiwan, backed by about US$1.8b of recent investment and strong AI related electronics demand, points to rising project start ups. These can convert the current backlog into higher sale of gas revenue and earnings over time.
See why 116 investors see Linde as 10% undervalued.
Result: Fair Value of $544.40 (UNDERVALUED)
Still, the Linde story can wobble if European industrial demand erodes further or if the U.S. homecare drag persists and keeps Americas margins under pressure.
Find out about the key risks to this Linde narrative.
Another Lens On Linde’s Valuation
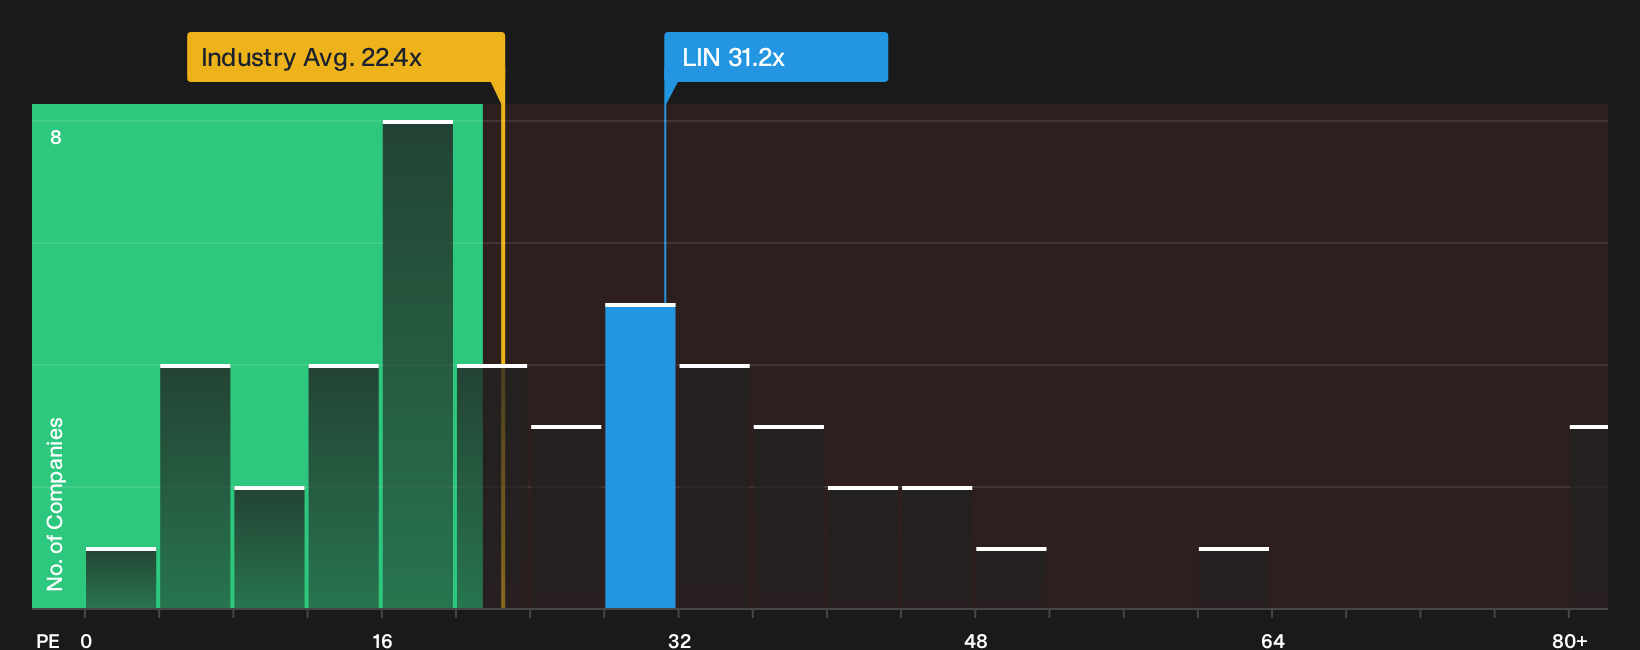
The crowd narrative says Linde is about 10% undervalued at $489.95 versus a fair value of $544.40. The market’s own P/E tells a different story. At 31.2x earnings, the stock trades well above the US Chemicals industry on 22.4x, yet below its peer group near 35.3x and above an estimated fair ratio of 23.1x. That gap points to limited room for disappointment. If growth or margins fall short, does the multiple compress toward that fair ratio or the sector average first?
See what the numbers say about this price, then find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed about whether Linde’s current price fairly reflects those projects and risks, or leaves something on the table? Act quickly, stress test the numbers against your own expectations, and weigh both the 2 key rewards and 1 important warning sign in 2 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Linde?
If Linde has you thinking harder about where capital works best next, do not stop here. Broaden your watchlist now or risk missing stronger setups.
- Target resilient compounding by reviewing a 27 high quality undervalued stocks that marry quality fundamentals with prices the market has not fully rewarded yet.
- Strengthen your income base by scanning 8 dividend fortresses that pair higher yields with balance sheets built to handle tougher conditions.
- Protect your downside first by focusing on 31 resilient stocks with low risk scores that score well on financial strength and volatility control.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com