
Is QUALCOMM (QCOM) Undervalued Following Its Huawei Patent Deal?
QUALCOMM (QCOM) has just signed a broad, multi year patent licensing deal with Huawei that centres on 5G and AI technologies. Investors are now asking how this reshapes Qualcomm’s future cash generation profile.
QUALCOMM’s shares trade at US$181.03, with a 30 day share price return of 7.28% that comes after a mixed quarter and a series of AI focused partnerships with Amazon and others. Over the past year, total shareholder return of 11.69% sits alongside a much stronger 3 year total shareholder return of 71.76%, which indicates that long term holders have fared better than newer entrants, even as recent momentum has been uneven.
Expand your hunt beyond QUALCOMM and see which other AI infrastructure players are getting similar attention with our hand picked 92 AI infrastructure stocks.
QUALCOMM’s recent jump on Huawei, Apple and AI data center news raises a simple question. Has most of the payoff already been captured in the price, or is investors’ upside still ahead?
Most Popular Narrative: 7% Undervalued
QUALCOMM’s most followed thesis pegs fair value at $194.13, modestly above the last close of $181.03. This suggests the recent Huawei and AI data center headlines still leave some room in the valuation that hinges on execution rather than hype.
Execution on the AWS custom silicon and optical connectivity agreement, which could total up to US$60b of product purchases over ten years and is expected to start contributing from the December 2026 quarter, would support Qualcomm’s new data center revenue goals of US$5b in fiscal 2027 and US$15b in fiscal 2029 and could become a key driver of long term revenue growth.
See why 628 investors see QUALCOMM as 7% undervalued.
Result: Fair Value of $194.13 (UNDERVALUED)
Still, QUALCOMM’s story can break if competition from in-house chips at major handset brands bites harder than expected, or if the data center ramp tied to AWS slips materially.
Find out about the key risks to this QUALCOMM narrative.
Another View: QUALCOMM Through The Cash Flow Lens
There is a catch. While the consensus fair value for QUALCOMM sits at $194.13 based on earnings expectations, Simply Wall St’s DCF model points to a lower value of $171.71, which would make the current $181.03 share price look slightly overvalued instead of modestly cheap.
Both approaches use reasonable inputs, yet they tell different stories about upside versus downside room. Which one feels closer to how you think Qualcomm’s Huawei, AWS and broader AI plans will convert into cash over time, and which risk are you more comfortable taking?
Look into how the SWS DCF model arrives at its fair value.
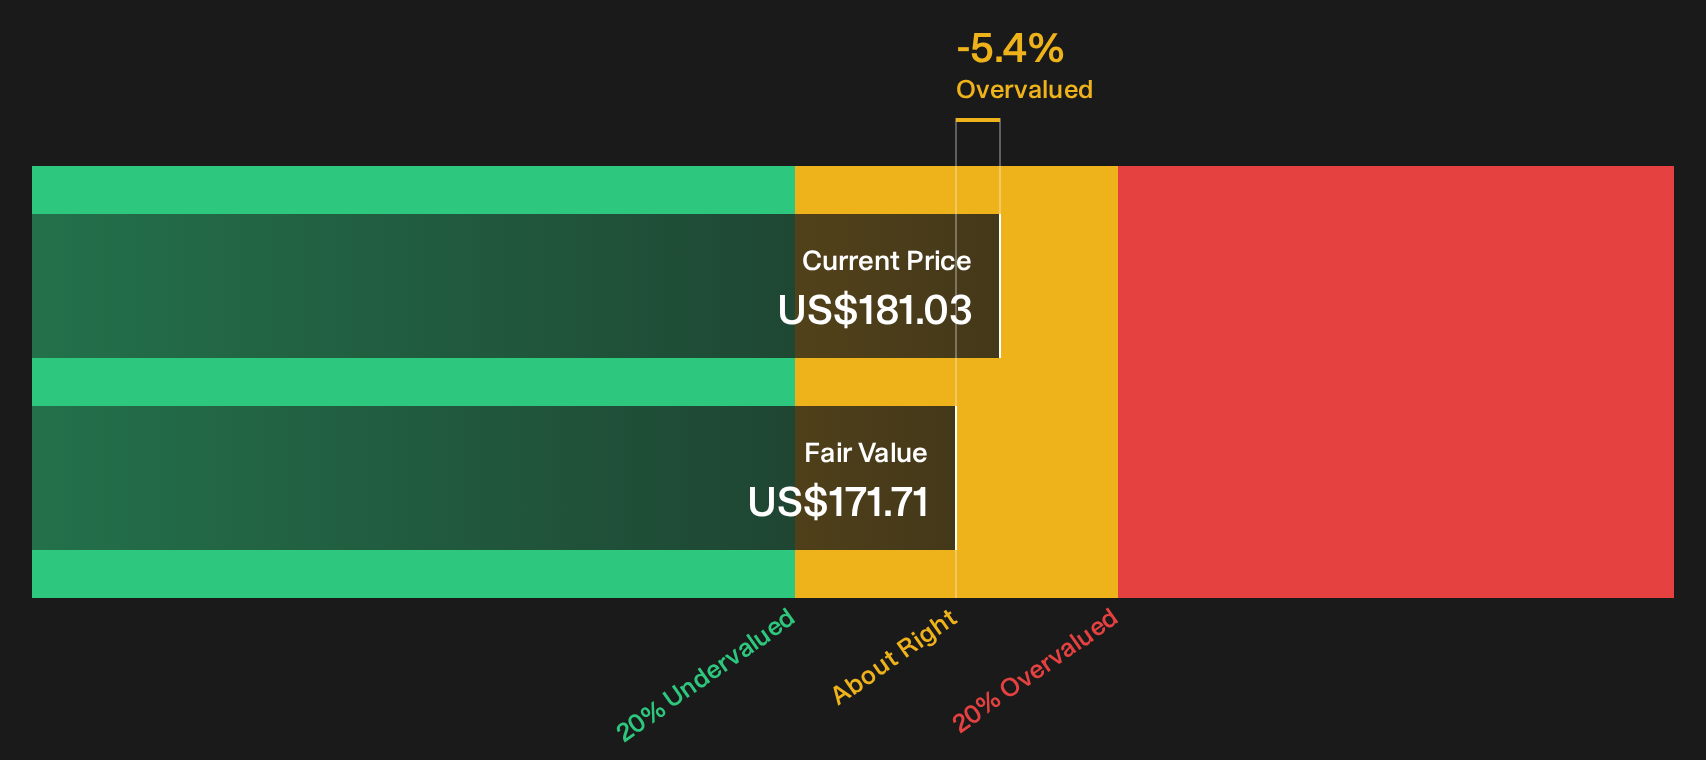
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out QUALCOMM for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on QUALCOMM’s valuation and narrative risk can feel messy, so move quickly, test the numbers yourself, and weigh both sides through 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond QUALCOMM?
If QUALCOMM has sharpened your thinking on AI and cash flows, broaden your watchlist now so you are not chasing opportunities after they move.
- Hunt for mispriced quality by scanning our 27 high quality undervalued stocks that pairs solid fundamentals with room for potential re rating.
- Strengthen your income stream by reviewing the 8 dividend fortresses that focus on higher yields with payment resilience in mind.
- Reduce portfolio stress by filtering for the 31 resilient stocks with low risk scores that score well on financial robustness and volatility control.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com