
HubSpot Just Cut 7% of Its Workforce. How to Play HUBS Stock Here.
A prominent software company that designs marketing, sales, and customer service software, HubSpot (HUBS) is making one of its boldest moves yet.
The company announced on Oct. 6 that it will cut about 7% of its workforce, or nearly 660 employees, as part of a restructuring designed to create a flatter, faster organization. The move comes as HubSpot shifts from building software features toward delivering customer outcomes with AI.
For HUBS stock, that creates a bigger question than the layoffs themselves. Is this a smart reset that can improve execution and margins, or a warning that growth has become difficult enough to force management into a major reorganization? Let's try to find out the answer.
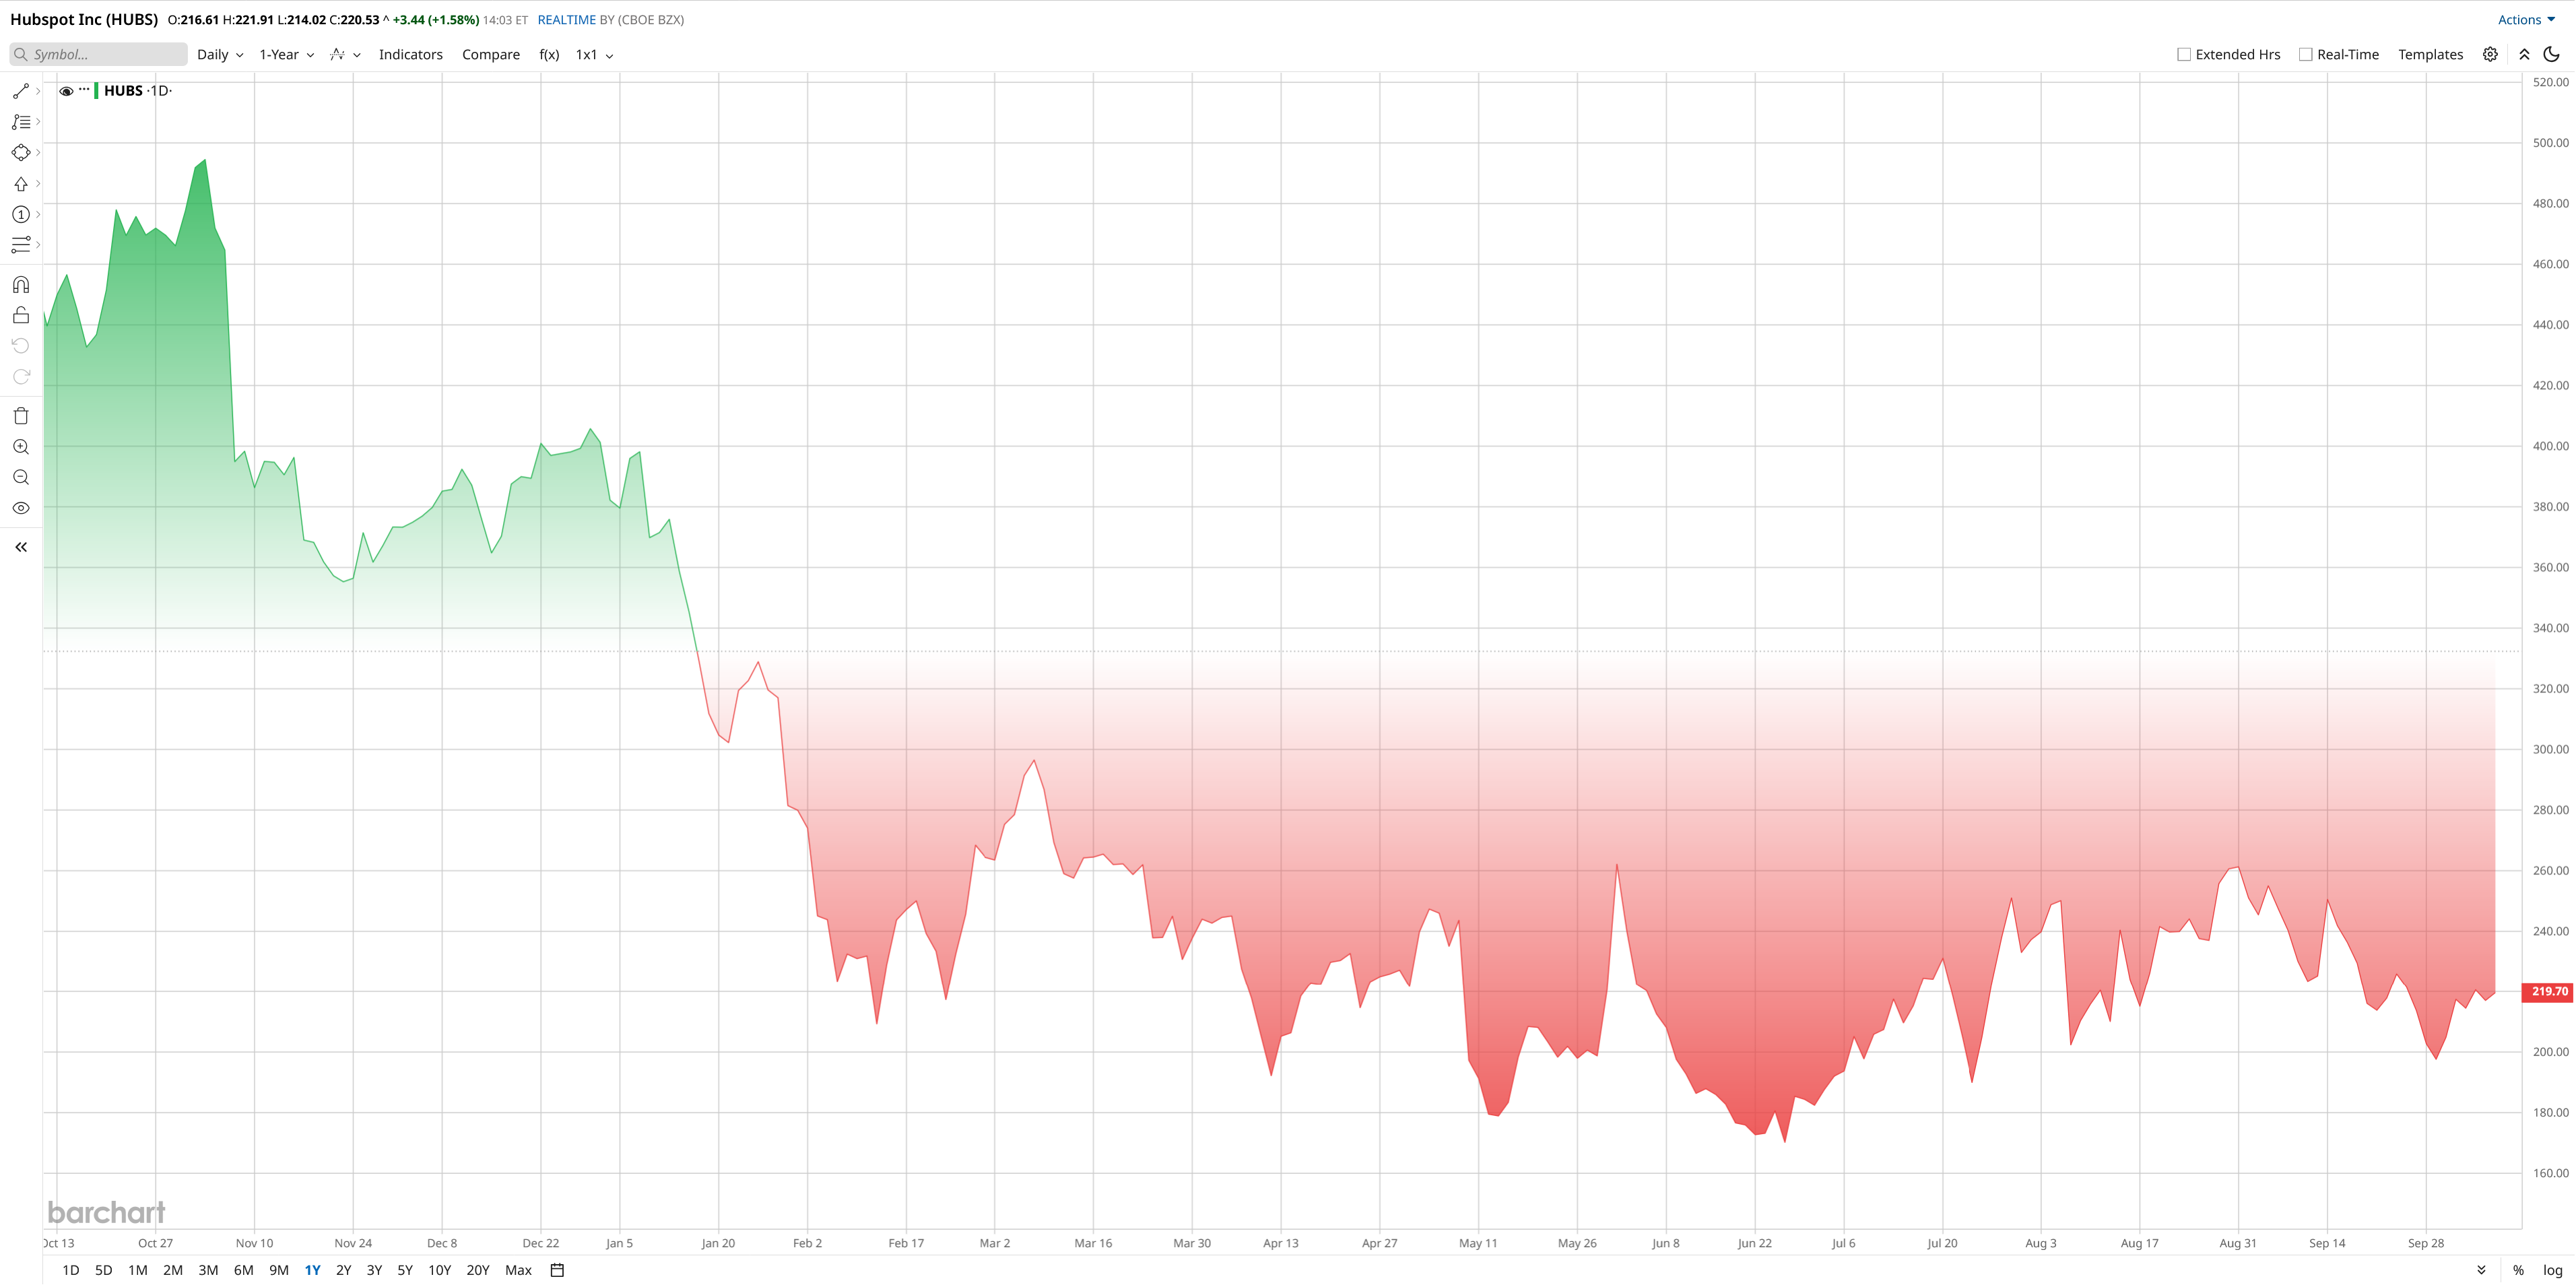
HUBS stock dipped about 1.5% after the news, although it has since bounced back by about the same amount during today's trading. That said, the stock is still down 45% in 2026.
HubSpot Is Betting on a Faster AI-Focused Organization
CEO Yamini Rangan said it changed in the last year, and now AI is transforming HubSpot's products, pricing, and customer service model. The company is set to replace the Hubs with product teams based on customer outcomes and reduce the number of layers in the management hierarchy to ensure that each team feels responsible for the results. “There's more than just a cost-cutting exercise here; this is about taking more of our resources and targeting them to our best chances,” Rangan emphasized.
This is quite meaningful to investors, though. HubSpot isn't claiming that demand has plummeted. Rather, management is admitting that the software industry is shifting toward AI-inspired results and that it must restructure its operations to make it competitive.
The restructuring is estimated to cost $65 million to $75 million, with the bulk of the charges in the fourth quarter of 2026. The cuts should be mostly finished by the end of the first quarter of 2027, the company said.
The Real Problem Is Still Customer Growth
The restructuring comes after a mixed second quarter. HubSpot generated $911.7 million in revenue, which was a solid 20% increase from the same quarter last year, and also reported a net income of $43.3 million. The margin on operating margin came in at 20%. But the company only added 7,000 net customers, which was lower than the 9,000 to 10,000 it was looking for.
Earlier this week, CEO Rangan had spoken about this in terms of getting results from the use of AI before they invest and knowing exactly how much it will actually cost. HubSpot started by providing trials for their AI agents, reducing pricing for several agents, and adding outcome pricing. And those changes might put a strain on the company's numbers in the short term because they could slow down the adoption of purchasing, but management believed they were ready to chase the adoption process in the future.
Where the bull and bear cases meet. Take Suzuki (SZKMY) for example. It will make healthy revenue gains this quarter, but they will come at a slower pace as vehicle sales slow. A combination of disciplined preparation for the next growth cycle, strengthening AI adoption, and restructuring could make the ratio of cuts appear to be the same strategy HubSpot is utlizing to execute faster. If the customers continue to decline, investors will see them as evidence that the company is not continuing its previous trend.
Analysts Remain Cautiously Bullish on HUBS Stock
Wall Street’s view is far more optimistic than HUBS stock’s recent performance.
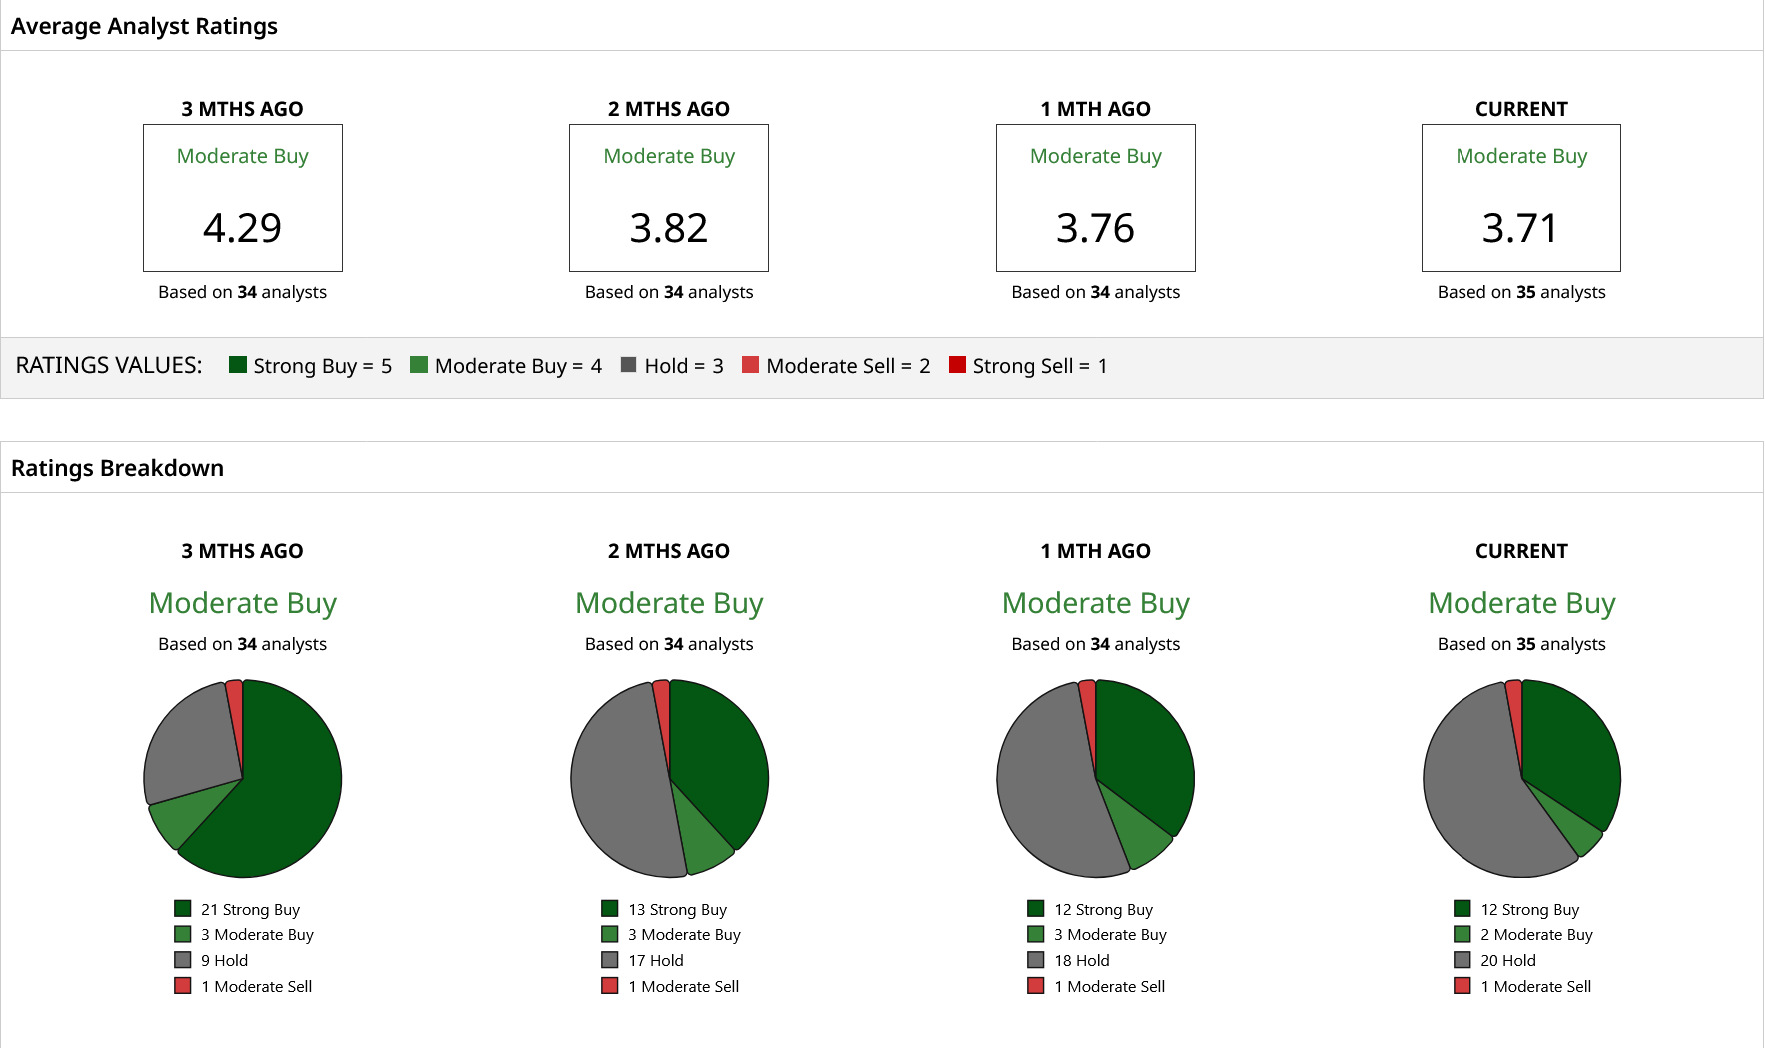
A group of 35 analysts tracked by Barchart rates HubSpot a consensus “Moderate Buy.” With an average target of $251.87, it implies an expected nearly 15% upside potential.
If we separate them out, recent calls are still constructive. Truist raised its target to $275, UBS lifted its target to $290, while RBC and Needham maintained $300 targets. Canaccord reiterated a “Buy” rating and $300 target, arguing that HUBS is “clearly pricing in a permanently impaired growth outlook.” Stifel, meanwhile, kept a more cautious “Hold” rating with a $225 target.
The message for investors is that HubSpot is taking a high-risk shot at the organizational gambit in a pivotal moment. The overhaul isn't a sign that the business is struggling, but another challenge will be to see if AI efforts lead to improved customer gains. Assuming it can, despite the absolute stock valuation for HUBS stock, it could still have significant upside. Otherwise, the cuts could be more of a wake-up call and less of a reset.
On the date of publication, Nauman Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.