
The Bet Digi International Holders Made Before A 108% Jump
If you only glanced at Digi International’s steady stream of product launches and earnings headlines, you might not expect what the share price did in the background. Investors who held Digi International over the past year are up 108.3%, including dividends. If you were weighing the bullish subscription story against worries about tariffs and competition back on 2025-10-06, what exactly in the record would have justified taking that risk?
This theme extends beyond Digi International. See which of 91 AI infrastructure stocks may still merit a closer look.
The Two Competing Stories Around Digi International
The shares cost US$36.76 at the start of the period, and Digi International sat between two very different but reasonable stories about what came next.
On the optimistic side, the subscription driven Narrative put a Fair Value of US$40.5, essentially the price implied if recurring revenue, a profit margin of 14.6% and a future P/E of 26.8x played out over about three years. That view leaned on customers steadily adopting higher margin subscription and cloud connected edge solutions.
The bearish reading pointed to a Fair Value of US$30, reflecting a scenario where geopolitical risk, tariffs and rising compliance costs kept pressuring hardware economics. Under that script, supply chain disruption, tougher regulation and faster product obsolescence were the key threats to Digi International’s margins and cash generation.
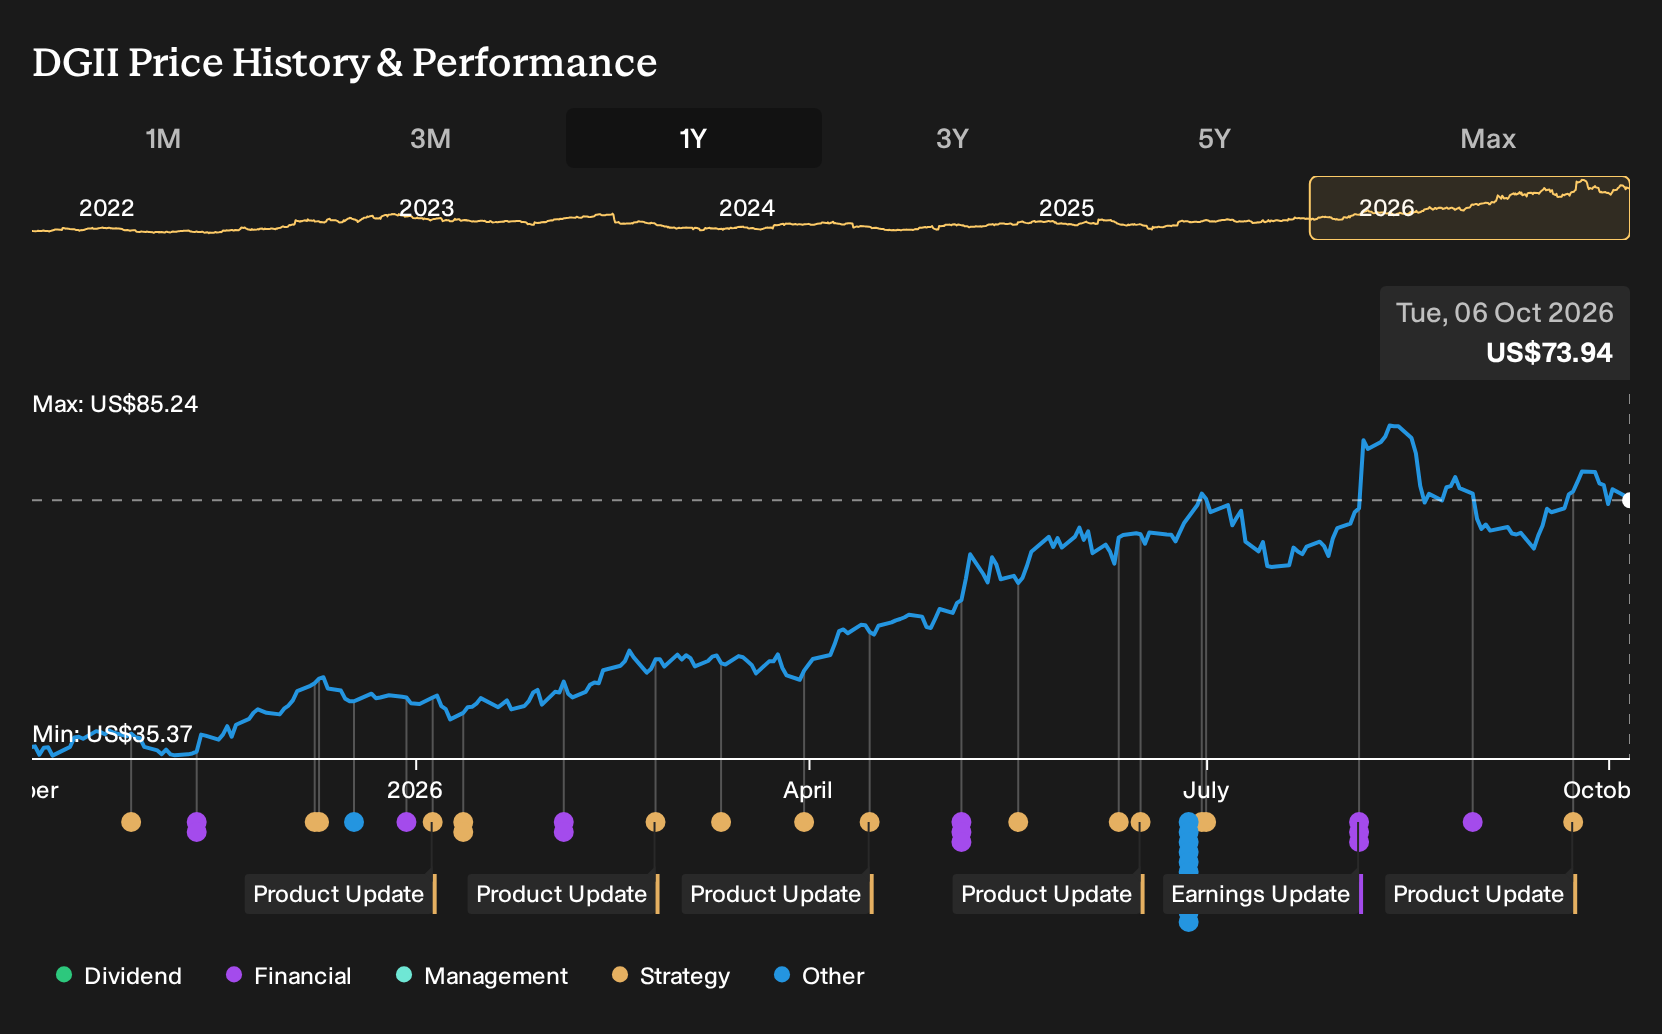
What The Results Changed For Digi International
Digi International delivered Q3 2026 revenue of US$138.67 million and net income of US$15.74 million, with net margin moving from 9.5% to 11.4%. That shift supported the subscription focused case that assumed stronger profitability from recurring services. However, insider selling during the period gave cautious investors a reason to question how durable that strength might be.
The lesson is simple. When a subscription story is on the table, track net margin and the share of recurring revenue in quarterly updates to see whether higher quality sales are actually turning into better profitability.
What Digi International’s Price Already Assumes
Digi International now trades at US$73.94, and the selected Narrative places its Fair Value above that level based on an ARR heavy model and acquisition execution. The focus is squarely on recurring contracts, high margins and whether the M&A engine can keep turning without eroding returns.
For anyone treating that higher Fair Value as a guide, the key test is whether Digi International can keep folding acquired ARR into its platform while protecting gross margin and cash conversion.
"The accelerating transition of customers to Digi International's subscription-based and recurring revenue solutions, with ARR growing faster than revenue and reaching $191 million in fiscal Q3 2026, continues to shift the mix toward higher margin software and services. This can support more stable revenue and stronger net margins over time."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Where Could You Get There Earlier?
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 41% below our estimate - targets data center and AI hardware programs while exiting weaker-margin consumer products manufacturing.
- Company 2 - 39% below our estimate - expands a unified integration helping merchants manage complex digital pay-ins and pay-outs.
- Company 3 - 45% below our estimate - absorbs a merger adding bankers, specialty platforms and technology while preserving relationship-focused services.
Three companies from the same screener. Open all 27 potentially undervalued companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com