
Krystal Biotech (KRYS) Could Be 17% Undervalued On Its Multiproduct Pipeline Story
Krystal Biotech (KRYS) has drawn fresh attention after recent price weakness, with the stock down about 9% over the past month and roughly 13% in the past 3 months, despite strong year-to-date gains.
Krystal Biotech’s recent pullback comes after a strong run. The 1-year total shareholder return is 78.57%, and the 5-year total shareholder return is at a very large multiple of the initial investment. Meanwhile, the 30-day share price return of 8.77% and 90-day share price return of 12.94% show that momentum has cooled from earlier in the year.
Scan for more stocks with a similar mix of strong historical returns and recent pullbacks by running the hand picked 27 high quality undervalued stocks alongside Krystal Biotech in your watchlist.
Bulls point to Krystal Biotech’s strong multi year returns and growing genetic medicine platform. Bears focus on recent share price softness and valuation risk. Which side do the current numbers support as you weigh the stock’s pricing?
Most Popular Narrative: 17% Undervalued
At a last close of $326.81 versus a most followed fair value view of about $392.11, Krystal Biotech screens as meaningfully below that narrative estimate. This puts the focus squarely on whether its genetic medicine pipeline can justify that gap.
Advancement of Krystal Biotech toward a multiproduct genetic medicines company through late stage programs such as KB803, KB801, KB407, KB111, KB707 and KB408, supported by HSV 1 platform technology designations, could broaden the revenue base beyond Vyjuvek and spread fixed costs across multiple products.
See why 32 investors see Krystal Biotech as 17% undervalued.
Result: Fair Value of $392.11 (UNDERVALUED)
Still, two pressure points could unsettle that 17% undervalued narrative for Krystal Biotech, including tighter Vyjuvek pricing in Europe and heavier spending on the expanding HSV 1 pipeline.
Find out about the key risks to this Krystal Biotech narrative.
Another View: Krystal Biotech Through Earnings Multiples
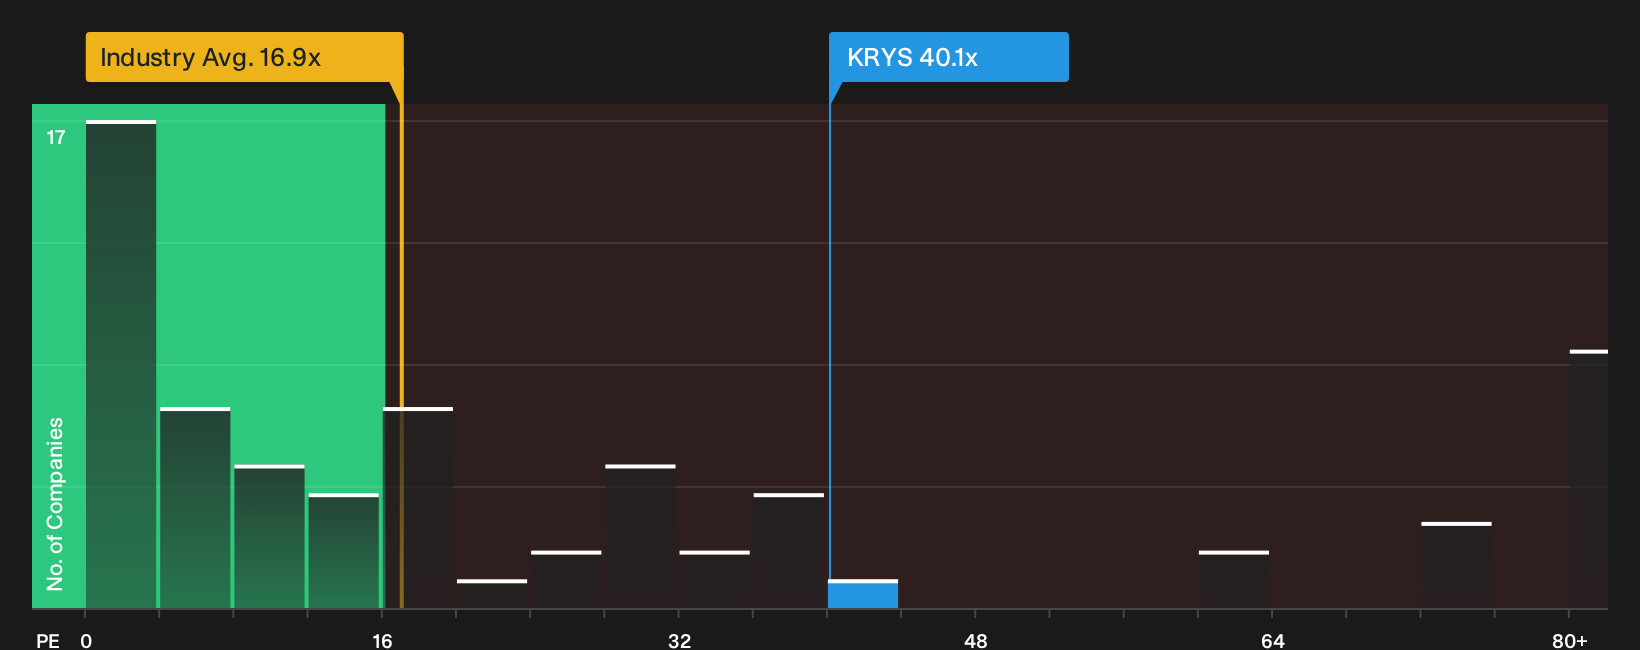
There is a catch in the Krystal Biotech story. On a P/E basis of 40.1x, the stock trades well above both the US Biotechs industry at 16.9x and its own fair ratio of 34.9x. That gap implies investors are already paying up, so how much margin of safety really remains?
To see what the numbers say about this price in more detail, take a look at the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed about whether the recent Krystal Biotech pullback signals opportunity or risk, and keen to act before sentiment shifts again, you can review both sides of the thesis through the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Krystal Biotech?
If you are serious about levelling up your portfolio, do not stop at Krystal Biotech. Use the Simply Wall St Screener to uncover fresh ideas that match your risk appetite and return goals.
- Target potential outperformance by scanning for quality companies that look mispriced using the 27 high quality undervalued stocks.
- Strengthen your income stream by finding businesses with generous payouts through the 8 dividend fortresses.
- Protect your capital by focusing on financially resilient opportunities via the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com