
Atmos Energy (ATO) Could Be 14% Undervalued As $697.5 Million Debt Deal Lands
Atmos Energy (ATO) just raised roughly $697.5 million through a new 6.000% fixed rate bond due 2036, giving the utility fresh long term capital that could matter for equity and credit investors.
Recent trading has been choppy for Atmos Energy, with the share price down 4.7% over the past month and 9.8% over 90 days, even as the new bond deal and an upcoming November earnings call keep attention on its longer term plans. Despite that near term pressure, the latest 1-day and 7-day share price returns are mildly positive, while total shareholder return over 3 and 5 years remains strongly positive. This suggests that long haul investors have still seen substantial gains even as short term momentum has cooled.
Scan other utility and infrastructure stocks that show similar balance sheet resilience with our curated 31 resilient stocks with low risk scores to see how Atmos Energy compares with companies that have lower risk profiles.Atmos Energy now has fresh long term debt in place and a share price that has drifted in recent months. The real tension is simple: Does a solid utility business translate into a fair entry price today?
Most Popular Narrative: 14% Undervalued
Atmos Energy is trading at $159.74 against a widely followed fair value estimate of about $185.55. This frames the stock as cheaper than that narrative implies, with the 7.24% discount rate doing a lot of the heavy lifting in that conclusion.
Major multiyear capital investment programs, including about US$4.2b of fiscal 2026 capex with roughly 87% to 89% directed to safety, reliability and modernization, continue to expand the regulated asset base and support future rate filings that can increase regulated revenue and operating income.
See why 14 investors see Atmos Energy as 14% undervalued.
Result: Fair Value of $185.55 (UNDERVALUED)
Still, the Atmos Energy story can change quickly if the US$4.2b capex program strains free cash flow or if legal and safety issues push operating costs higher than regulators allow.
Find out about the key risks to this Atmos Energy narrative.
Another View On Atmos Energy Valuation
The first fair value story for Atmos Energy leans on analyst forecasts and a 7.24% discount rate. A different lens tells a cooler story. The SWS DCF model points to a value of $133.68, which is below the current $159.74 share price and frames the stock as overvalued on that basis. Which lens do you trust more when the two models disagree by that much?
For investors who want to see how this cash flow view is built line by line, Look into how the SWS DCF model arrives at its fair value..
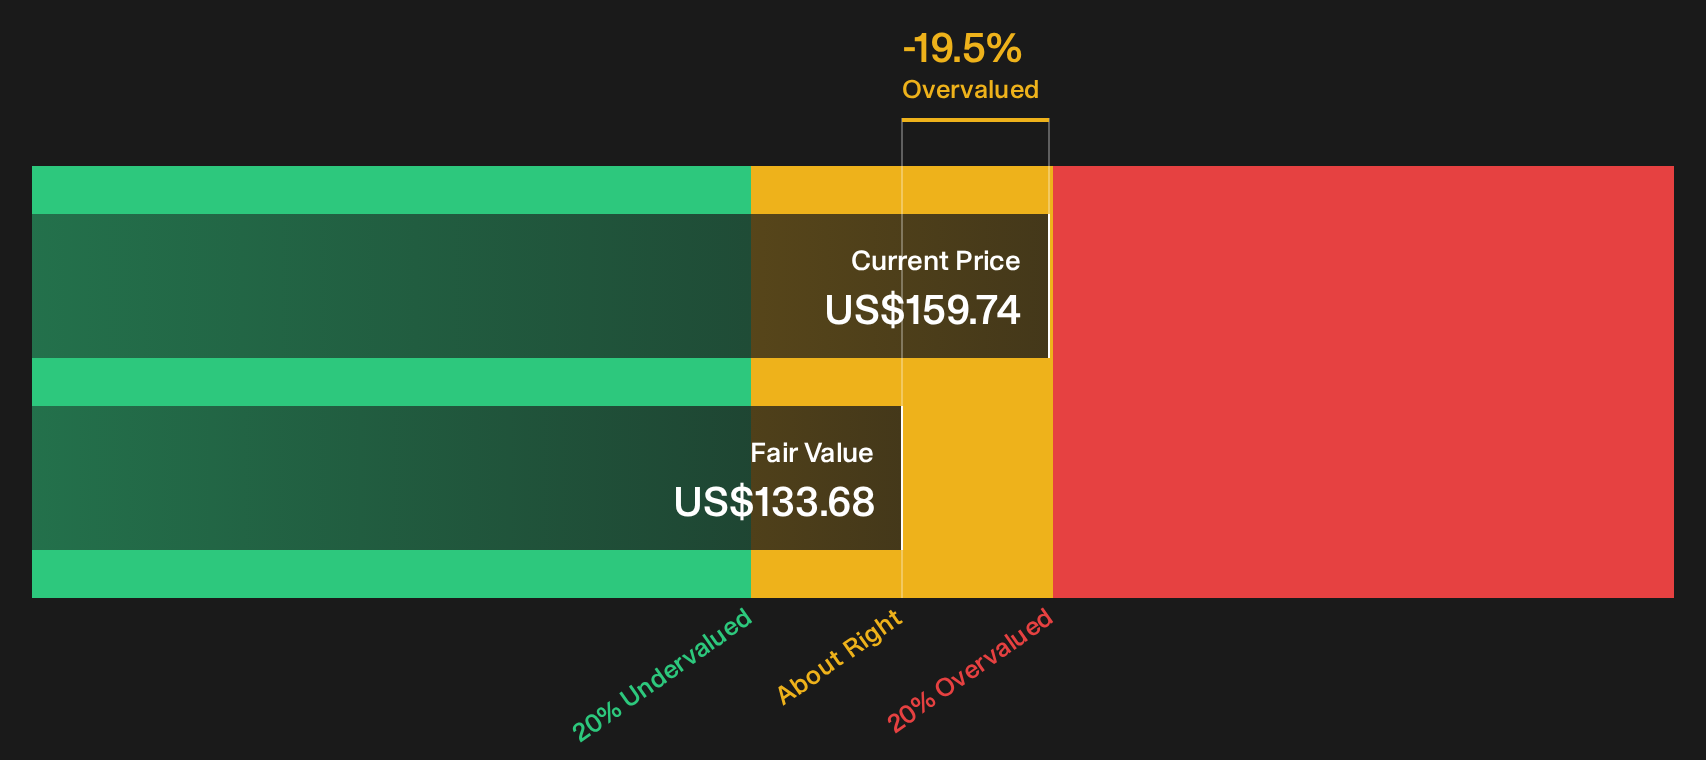
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Atmos Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Atmos Energy so far. If you want to move quickly and build your own view, start by weighing the 2 key rewards and 2 important warning signs.
Looking for more Atmos Energy style investment ideas?
If Atmos Energy is on your radar, do not stop there. Broader opportunities often sit just beyond the stocks you already know.
- Target steadier compounding by scanning companies that match your risk comfort level through our 31 resilient stocks with low risk scores.
- Hunt for mispriced quality and see which businesses currently screen as potential bargains in the 27 high quality undervalued stocks.
- Strengthen your income stream by reviewing companies that feature resilient payouts in the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com