
Flex (FLEX) Could Be 7% Undervalued Following Its US$3.3b EPC Power Loan Move
Flex (NasdaqGS:FLEX) just lined up a new US$3.3b senior term loan facility that ties directly to its plan to acquire EPC Power, giving investors a fresh angle on the stock’s capital structure.
Flex’s latest financing move comes at a time when the stock has already seen strong interest, with a 1-day share price return of 3.96% and a 7-day gain of 6.63% contributing to a 30-day share price return of 10.84%, even though the 90-day share price return declined 8.99%. These short-term moves sit on top of a year-to-date share price return of 90.61%. Long-term investors are sitting on a 1-year total shareholder return of 112.02% and a very large 5-year total shareholder return, as the Axiom spin-off plans and EPC Power acquisition funding influence how the market views Flex’s growth potential and balance sheet risk.
Scan other potential beneficiaries of the same AI data center and power build out by reviewing our curated list of 91 AI infrastructure stocks alongside Flex.
Flex now has a fast growing data center arm priced near its own market value and a fresh US$3.3b loan commitment on the table. Is that strength already fully reflected in the share price, or not yet?
Most Popular Narrative: 6.8% Undervalued
Flex closed at $121.38 against a narrative fair value of $130.26, which frames the new EPC Power funding inside a wider valuation story that already treats the business as more than a traditional contract manufacturer.
Flex is transitioning from a cyclical, low-margin manufacturer into a high-margin, sticky, engineered-solutions partner. It sits squarely at the intersection of three macro trends: the AI infrastructure buildout, global supply chain nearshoring, and energy transition power management. Investors increasingly view Flex as a critical technology enabler rather than a legacy manufacturer.
See why 4 investors see Flex as 7% undervalued.
Result: Fair Value of $130.26 (UNDERVALUED)
Still, the Flex narrative can crack if AI data center demand cools or if the CPI spin off and EPC Power integration add execution and balance sheet strain.
Find out about the key risks to this Flex narrative.
Another View: Flex Through The P/E Lens
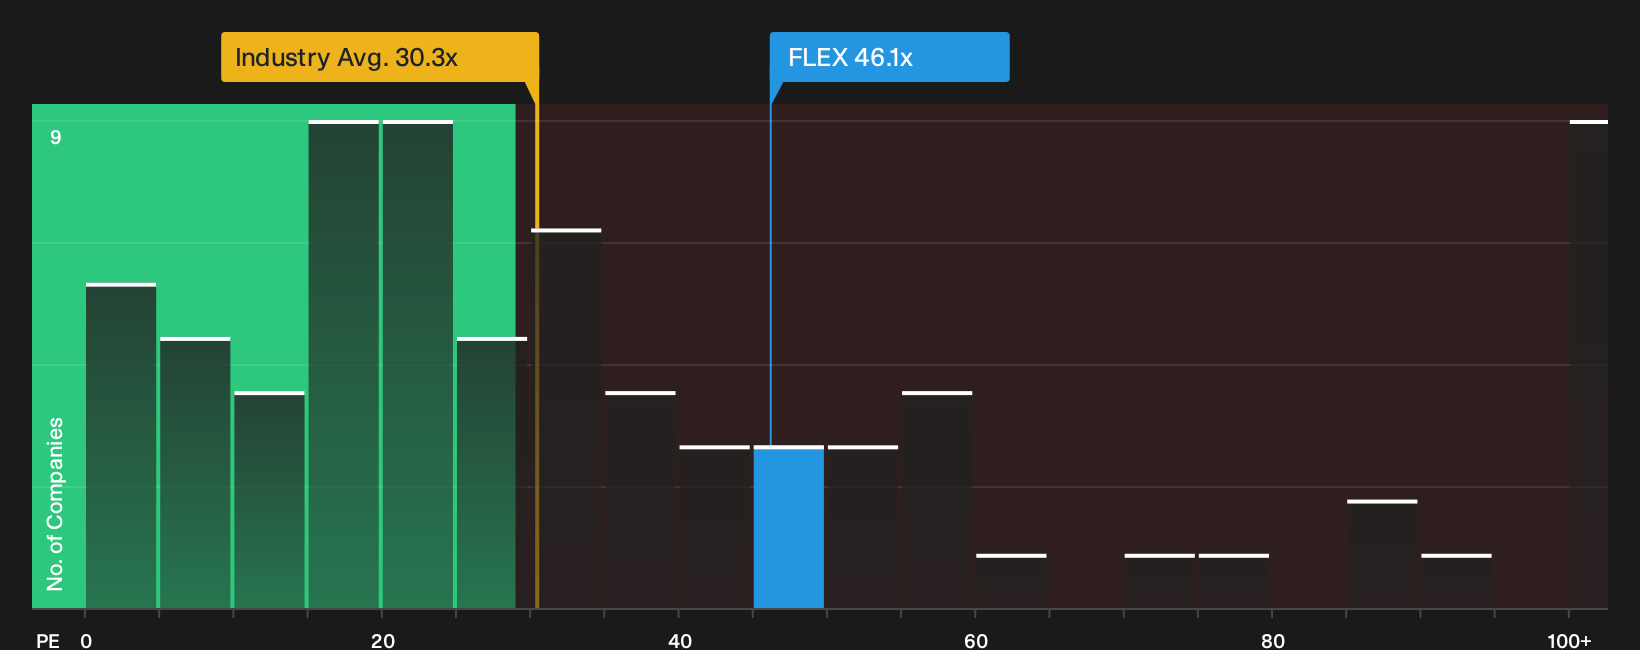
The SWS DCF model paints Flex as undervalued, with the shares trading about 40.5% below an estimated future cash flow value of $204.10. The market is not that cautious when you look at the P/E. At 46.1x earnings, Flex trades well above the US Electronic industry on 30.3x and ahead of peer averages at 37.1x.
Even so, that same 46.1x ratio sits below an estimated fair ratio of 61.1x. This implies investors are already paying a premium, but not the full price that regression work suggests the stock could move toward. How comfortable you feel paying up for that kind of multiple premium comes down to how much growth and balance sheet strain you think the Flex story can support.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals like these always split opinion, so treat this as a prompt to check the data yourself and decide where Flex really sits on your risk reward spectrum. To weigh those trade offs quickly, start with the balance of 4 key rewards and 1 important warning sign
Looking for more Flex investment ideas?
If you like the setup around Flex, do not stop there. Use curated stock lists to test other opportunities before the crowd catches on.
- Target potential mispricing early by scanning our 27 high quality undervalued stocks and compare how those opportunities stack up against Flex on quality and price.
- Lock in reliable income candidates by reviewing a focused group of 8 dividend fortresses that might complement a growth story like Flex in your portfolio.
- Protect the downside first and screen for 31 resilient stocks with low risk scores that can balance out more aggressive ideas without leaving unused cash on the sidelines.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com