
Novartis (SWX:NOVN) Could Be 7% Undervalued On Its Growth Narrative
Novartis (SWX:NOVN) is back in focus after CAS agreed to help its biomedical research arm pull together scattered reaction data into a single AI-ready discovery platform for internal and external chemistry information.
Recent price action has cooled, with a 30-day share price return down 9.57% and a 90-day move down 6.93%. Even though year-to-date the share price is up 8% and the 1-year total shareholder return sits at 14.82%, this hints that Novartis still carries longer term momentum despite shorter term pressure.
Spot 126 healthcare AI stocks that, like Novartis, are leaning into AI driven research platforms and could be setting up their next leg of momentum.After a strong 1-year return but a softer 3 month patch, the question is simple: Is Novartis still offering meaningful upside, or has most of the easy gain already played out on the current valuation?
Most Popular Narrative: 7% Undervalued
On the most followed valuation view, Novartis has a fair value of about CHF126 per share versus a last close of CHF117.18. This points to a modest discount that hinges on how its pipeline and core franchises play out over the next few years.
Novartis' robust pipeline and rapid regulatory progress in advanced therapies (including biologics, gene, and cell therapies) positions the company to benefit from emerging healthcare technologies, potentially accelerating future earnings and margin growth as new high-value products launch. Expansion in emerging markets, particularly China (with Leqvio's strong out-of-pocket uptake and continued ex U.S. growth in priority brands), increases Novartis' overall addressable market, mitigating saturation in developed geographies and driving future sales and cash flow.
See why 111 investors see Novartis as 7% undervalued.
This widely followed narrative leans on a 3.95% discount rate and incorporates long term revenue of about $66.9b and earnings of $18.4b by 2029, with profit margins rising from 22.5% to roughly 27.5% and a future P/E of 17.2x underpinning the CHF126.13 fair value. That framework treats the recent patch of weaker price momentum as noise around a longer term story driven by a focused drug portfolio, high quality earnings and an expected 11.04% annual earnings growth profile, while still flagging patent expiry, pricing pressure and competition as central risks to that valuation.
Result: Fair Value of CHF126.13 (UNDERVALUED)
Still, Novartis faces meaningful downside catalysts if key late stage programs stumble or if pricing and reimbursement pressure hits cash flows harder than analysts expect.
Find out about the key risks to this Novartis narrative.
Another View: What The P/E Says About Novartis
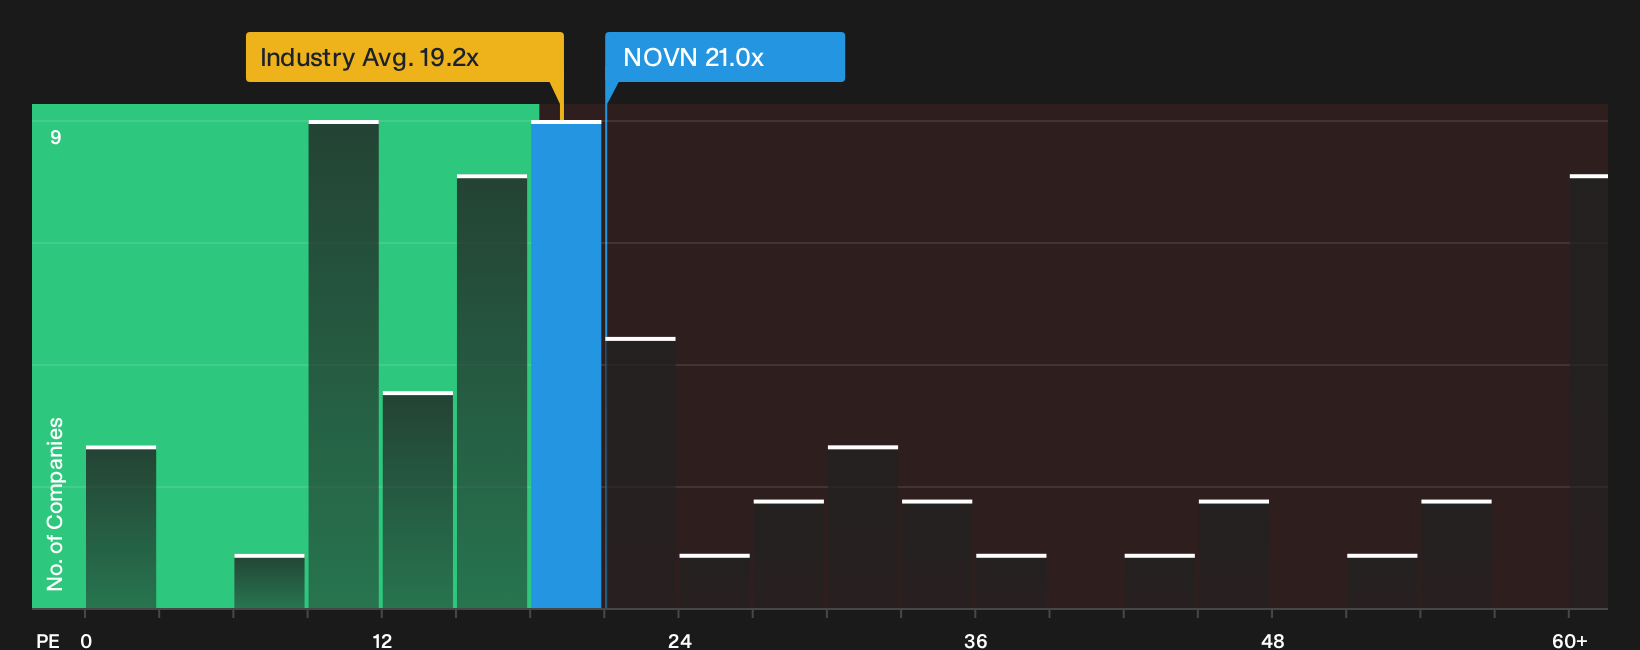
There is a different read on Novartis if you step away from cash flow forecasts and look only at what investors pay for each franc of earnings. The stock trades on about 21x P/E, which is higher than the European pharmaceuticals average of 19.2x.
At the same time, Novartis is on a much lower P/E than its closer peer group at 41.3x, and below an estimated fair ratio of 44.9x. That mix of slightly pricey versus the wider industry but cheaper versus peers raises a simple question: Is the market overpaying for safety here or underpaying for future quality?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Novartis so far, with both concerns and bright spots in the data. Consider acting promptly and weigh the full picture for yourself by checking the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Novartis?
If Novartis has your attention, do not stop there. Use the screener to surface fresh opportunities that fit your goals before others move first.
- Target resilient cash generators by reviewing a curated 168 dividend fortresses that focuses on income without losing sight of balance sheet strength.
- Hunt for quality at a discount with a focused 178 high quality undervalued stocks that combines healthier balance sheets with compelling valuations.
- Zero in on financial resilience through a list of solid balance sheet and fundamentals (206 results) that filters for sturdier fundamentals when conditions get tougher.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com