
Astronics (ATRO) Could Be 31% Undervalued As Aerospace Demand Builds
Astronics (ATRO) is back on the radar after recent trading left the share price at $69.16. The business carries a market value of about $2.95b and has meaningful aerospace exposure.
Recent trading has been choppy for Astronics, with the share price down about 9.3% over the past month and 2.8% over 90 days. However, the year-to-date share price return of 46.6% and a 1-year total shareholder return of 73.4% signal momentum that has been building over a longer stretch.
Scan for other Astronics-style aerospace and defense plays that show similar momentum and fundamentals in our hand picked list of solid balance sheet and fundamentals (25 results).
Astronics has already rewarded anyone who stayed on board through the swings. The real tension now is simple: pay up at this price, or hold cash and hope for a friendlier tag later as the valuation picture comes into focus.
Most Popular Narrative: 31% Undervalued
Astronics is being framed as materially undervalued, with a narrative fair value of $100.50 against the last close at $69.16, so the gap rests on whether current growth and margin assumptions hold.
Production rate increases for major commercial aircraft platforms (such as Boeing 737, Airbus A320, and expected ramp-ups for 787, A350, and new programs like the A220) are likely to drive continued growth in demand for Astronics' power, lighting, and connectivity solutions, supporting both revenue acceleration and operating leverage through 2025 and beyond. Continued global growth in air travel and airline fleet renewals boost both OEM sales and retrofit opportunities for cabin power, inflight connectivity, and entertainment products, strengthening recurring revenue streams and fostering pricing power, as reflected by ongoing successful price increases across major OEM and airline customers.
See why 13 investors see Astronics as 31% undervalued.
According to the most widely followed narrative, that $100.50 fair value reflects analyst assumptions that Astronics can lift annual revenue to about $1.4b and earnings to $249.6m by 2029, while the SWS DCF work applies an 8.18% discount rate and a future P/E of 22.3x to those profit forecasts. The current share price sits well below both that fair value and the $96.79 future cash flow estimate in the SWS DCF model, so anyone reviewing Astronics now is really deciding how much conviction they have in those growth, margin and balance sheet assumptions holding up over time.
Result: Fair Value of $100.50 (UNDERVALUED)
Still, the bullish Astronics script can unravel if tariff costs bite harder than expected, or if Test Systems stumbles again with project overruns and weak execution.
Find out about the key risks to this Astronics narrative.
Another View: Astronics Through The P/E Lens
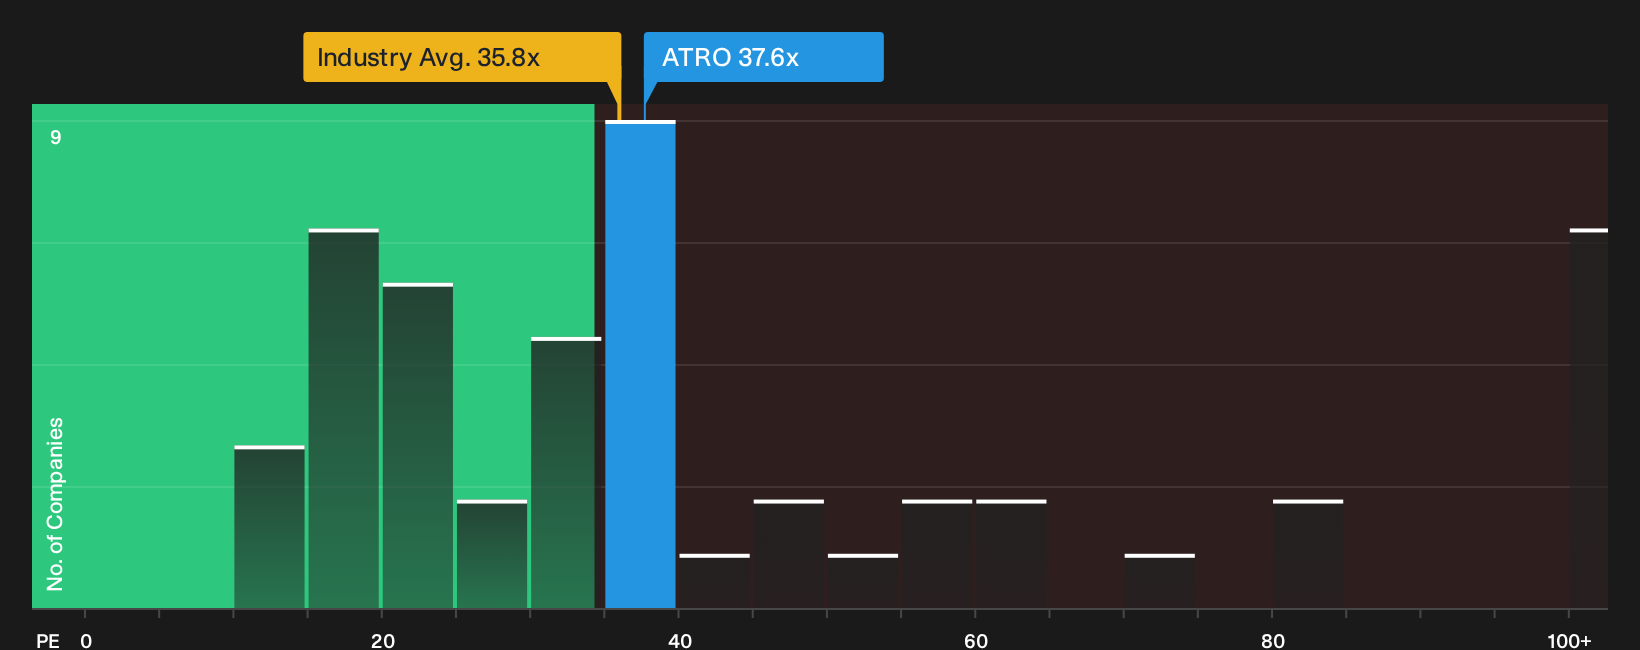
There is a twist when you look at Astronics through simple earnings multiples instead of fair value estimates. The stock trades on a P/E of 37.6x, which is richer than the broader US Aerospace & Defense group at 35.4x, and exactly in line with its fair ratio of 37.6x. That points to a fully priced tag on this metric, even though the same P/E still comes in well below the 56.9x peer average. For anyone weighing the bullish fair value story against this richer earnings multiple, the key issue is which signal deserves more weight in your own process.
To see what those numbers say about valuation risk and potential opportunity, take a closer look at the detailed multiple breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed feelings about Astronics after all this. If you want to move past the headline story and test the thesis yourself, start by weighing the 4 key rewards and 2 important warning signs.
Looking for more Astronics-style investment ideas?
If Astronics has your attention, do not stop here. Put a shortlist of fresh ideas to work so your capital is not sitting on the sidelines.
- Target potential mispricings by reviewing the 27 high quality undervalued stocks that combine quality fundamentals with cheaper tags than many peers.
- Strengthen the defensive side of your portfolio by scanning the 31 resilient stocks with low risk scores that score well on resilience and balance sheet quality.
- Get ahead of the crowd by checking the 19 high quality undiscovered gems that pair solid financials with lower investor attention right now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com