
Why Cathie Wood Is Taking Profits on AMD Stock
Amid elevated bond yields, high oil prices, interest rates, and talks of superintelligence, maverick investor Cathie Wood has uncharacteristically stayed away from the spotlight. Known for making outsized bets on companies like Tesla (TSLA) and Palantir (PLTR) when it was not fashionable, Wood has amassed an enviable following in the world of investing.
However, Wood's latest moves in the market are certainly noteworthy, and the investing community has taken note of them again. While the funds overseen by Wood may have bought shares of Nvidia (NVDA) and biotech company Intellia Therapeutics (NTLA) in substantial numbers, it is her largest sale that has grabbed more attention.
Wood's funds sold 181,767 AMD (AMD) shares worth roughly $110.4 million. Further, this is not the first time this year that Wood has traded out of AMD shares. On Aug. 28, ARK sold $74.5 million of AMD while buying approximately $55.6 million of Nvidia and $20.5 million of Broadcom (AVGO).
Cathie Carts Out AMD Stock Worth $111 Million
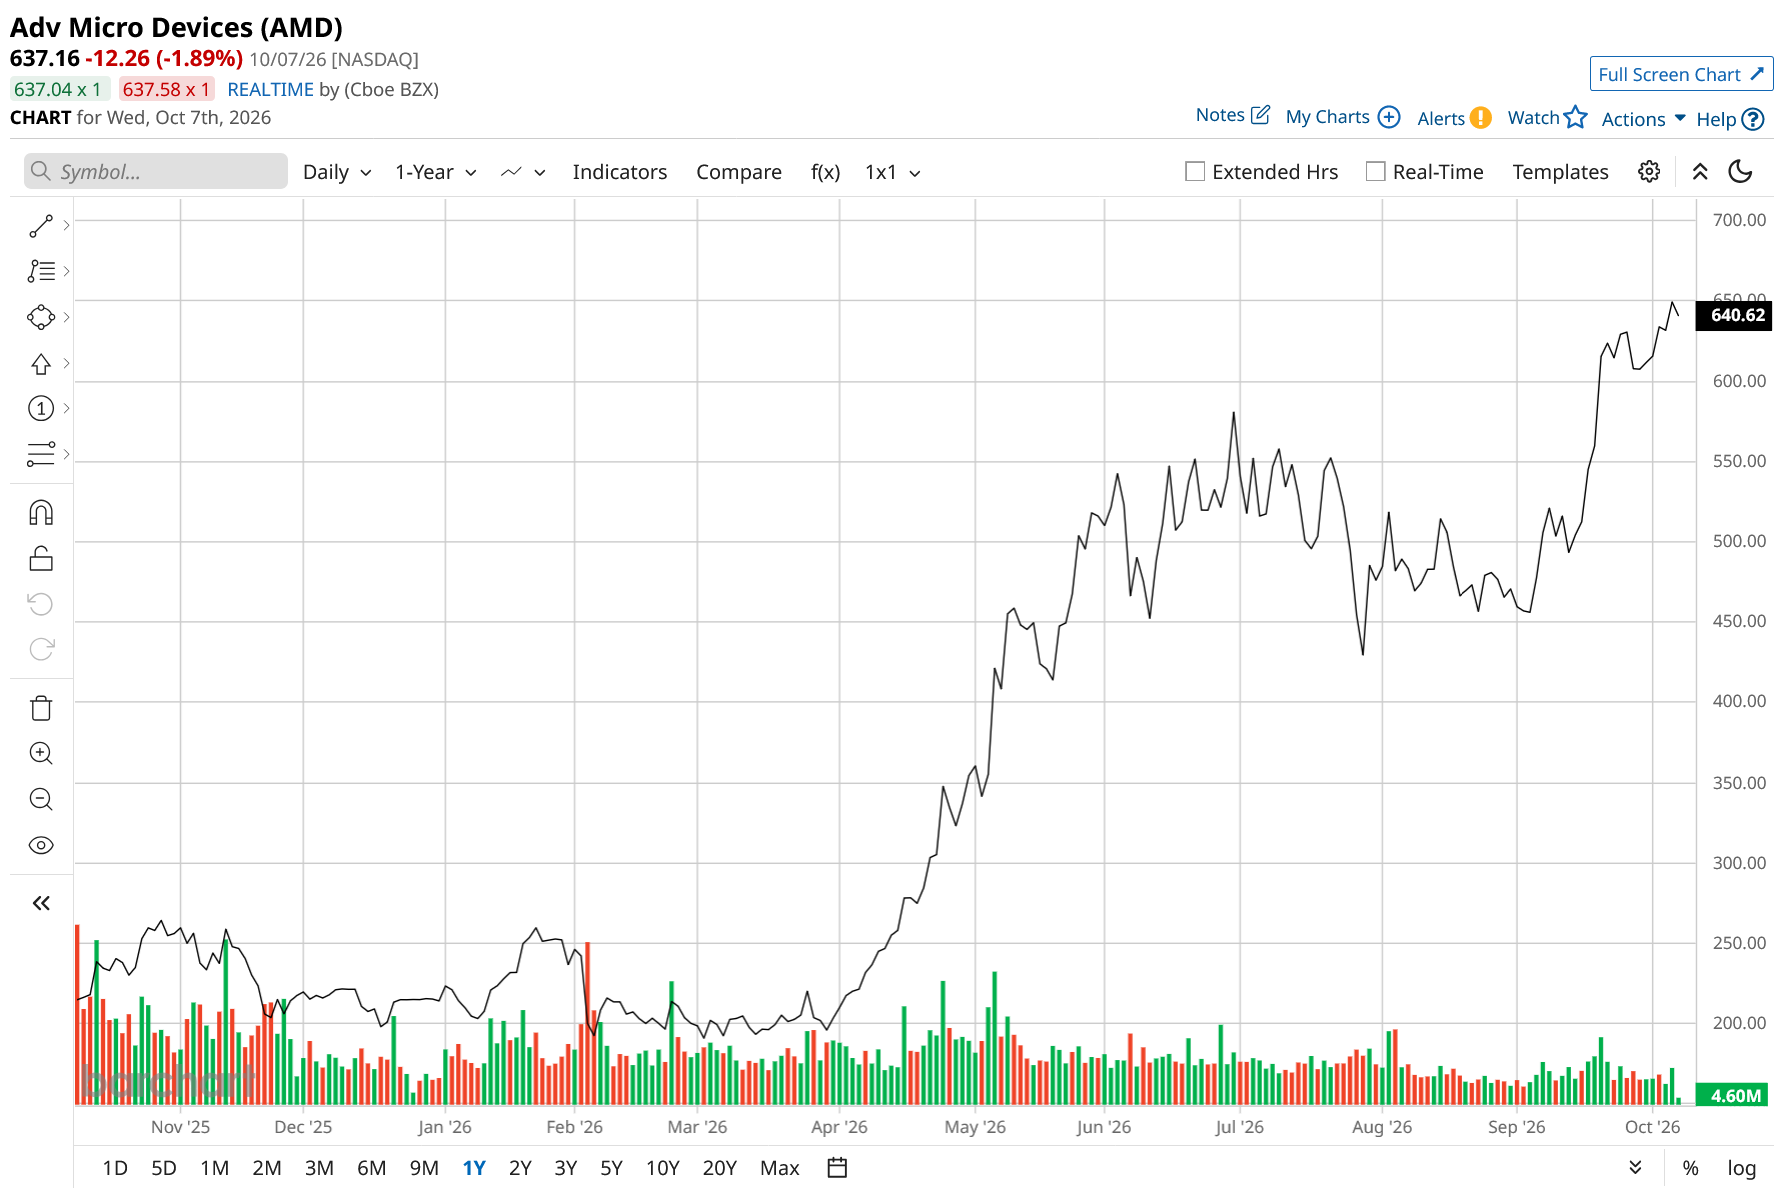
AMD has been having a great time in the markets, especially this year. Its shares are up 195%, which propelled it to the venerable $1 trillion market-cap club. It debuted its first-ever rack-scale system, Helios, and recently bought spatial intelligence company World Labs for $8.2 billion. So, why is Wood lightening up on AMD when it is seemingly gearing up to take on market leader Nvidia (NVDA) on all fronts? AMD skeptics may also point to the fact that Wood loaded up on the latter and Broadcom (AVGO), two competing companies.
However, the answer is elementary, really: profit booking.
AMD shares have outperformed Nvidia and Broadcom by a country mile, with Nvidia and Broadcom up just 28.4% and 5.3%, respectively. Moreover, AMD is also trading at a premium to both Nvidia and Broadcom. Notably, AMD has a P/E, P/S, and P/CF on a TTM basis of 110.05, 25, and 102.66, currently. Whereas the same metrics for Nvidia are 33.37, 18.75, and 42.05, respectively, and for Broadcom it is at 36.39, 18.92, and 41.70, respectively.
Thus, this seems like a routine reallocation out of a stock that has gone ballistic in a short span of time and is most probably not a verdict from the veteran investor on AMD's long-term investment attractiveness.
Q2 Showing Should Dispel Any Fears
AMD delivered strong second quarter 2026 results that largely met high expectations. Despite a decline in the share price after the release, the company once again achieved a double beat on both revenue and earnings.
Revenue rose 50% year-over-year (YoY) to $11.5 billion. Data center revenue reached $6.7 billion, reflecting growth of 107% from the prior year. Gross margins expanded meaningfully to 54% from 40% in the year earlier period. Looking ahead, the company guided for third-quarter net revenue between $12.7 billion and $13.3 billion, well above the consensus estimate of $12.5 billion.
Earnings per share surged 246% YoY to $1.66, exceeding the consensus forecast of $1.62. This marked the seventh consecutive quarter in which AMD outperformed profit expectations.
Cash generation remained solid, with net cash from operating activities climbing to $2.4 billion from $1.5 billion in the year-ago period. Free cash flow advanced 32% to $1.6 billion. The company ended the quarter with $13.1 billion in cash, substantially higher than its short-term debt balance of $875 million.
During the quarter, AMD also introduced its next-generation Instinct MI400 Series graphics processing units, its sixth-generation EPYC server central processing units, and the Helios rack scale systems.
The significant run-up in the stock has left AMD shares trading at elevated valuation levels. A forward P/E ratio of 83.66 times, P/S multiple of 20.31 times, and P/CF of 131.68 times all stand well above the respective sector medians of 23.53 times, 3.51 times, and 20.60 times.
Analyst Opinion on AMD Stock
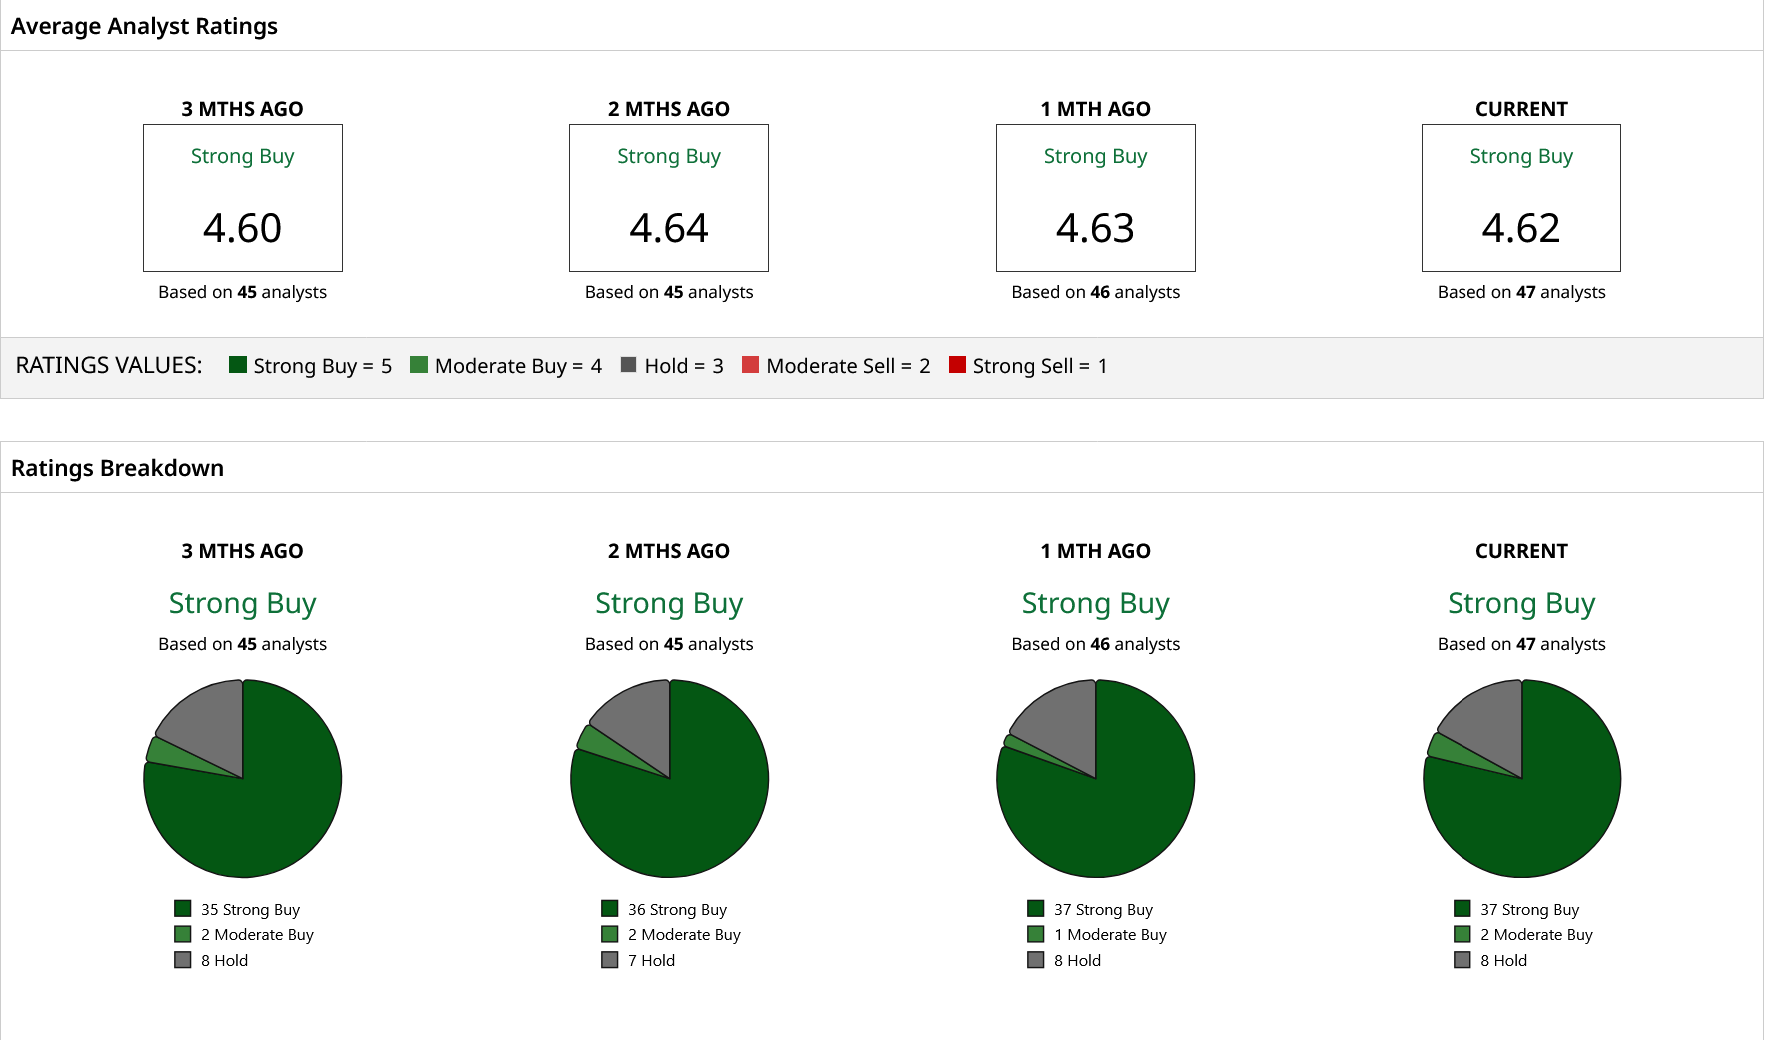
Overall, Wall Street seems bullish on AMD stock, earmarking a consensus rating of “Strong Buy.” The mean target price of $652.86 sits only 2.5% above its current price, setting the stage for a possible upward revision soon. Out of 47 analysts covering the stock, 37 have a “Strong Buy” rating, two have a “Moderate Buy” rating, and eight have a “Hold” rating.
On the date of publication, Pathikrit Bose did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.