
Health Platform Launch Could Be A Key Test For Clorox (CLX)
- Clorox recently launched Clorox Purell ProCare, a combined CloroxPro and GOJO health and hygiene platform that gives professional and healthcare customers unified access to brands including Clorox, Purell, Pine-Sol and Glad, supported by a single sales and distributor network.
- The new platform shows Clorox leaning further into institutional health and hygiene, using the GOJO acquisition to build a broader solutions ecosystem rather than just adding another product line.
- Next, the focus turns to how Clorox’s Purell ProCare rollout could reshape the investment narrative around health and hygiene driven earnings.
Compare Clorox’s health and hygiene focus with other resilient consumer stocks by reviewing our hand picked 31 resilient stocks with low risk scores that aim to keep risk profiles in check.
Clorox Investment Narrative Recap
To remain invested in Clorox, you need to believe the health and hygiene pivot can offset sluggish categories and value-seeking shoppers who favor club and mass channels. The Purell ProCare launch aligns with that view, since it is focused on institutional demand and more contracted, repeat business rather than one-off retail volumes.
In the near term, the key swing factor is whether productivity initiatives, ERP benefits and ProCare scale can outpace roughly US$200 million of forecast input and supply chain cost pressure for fiscal 2027. The main risk is that margin rebuilding remains slow, which could keep earnings tight against a high dividend payout and limit balance sheet flexibility.
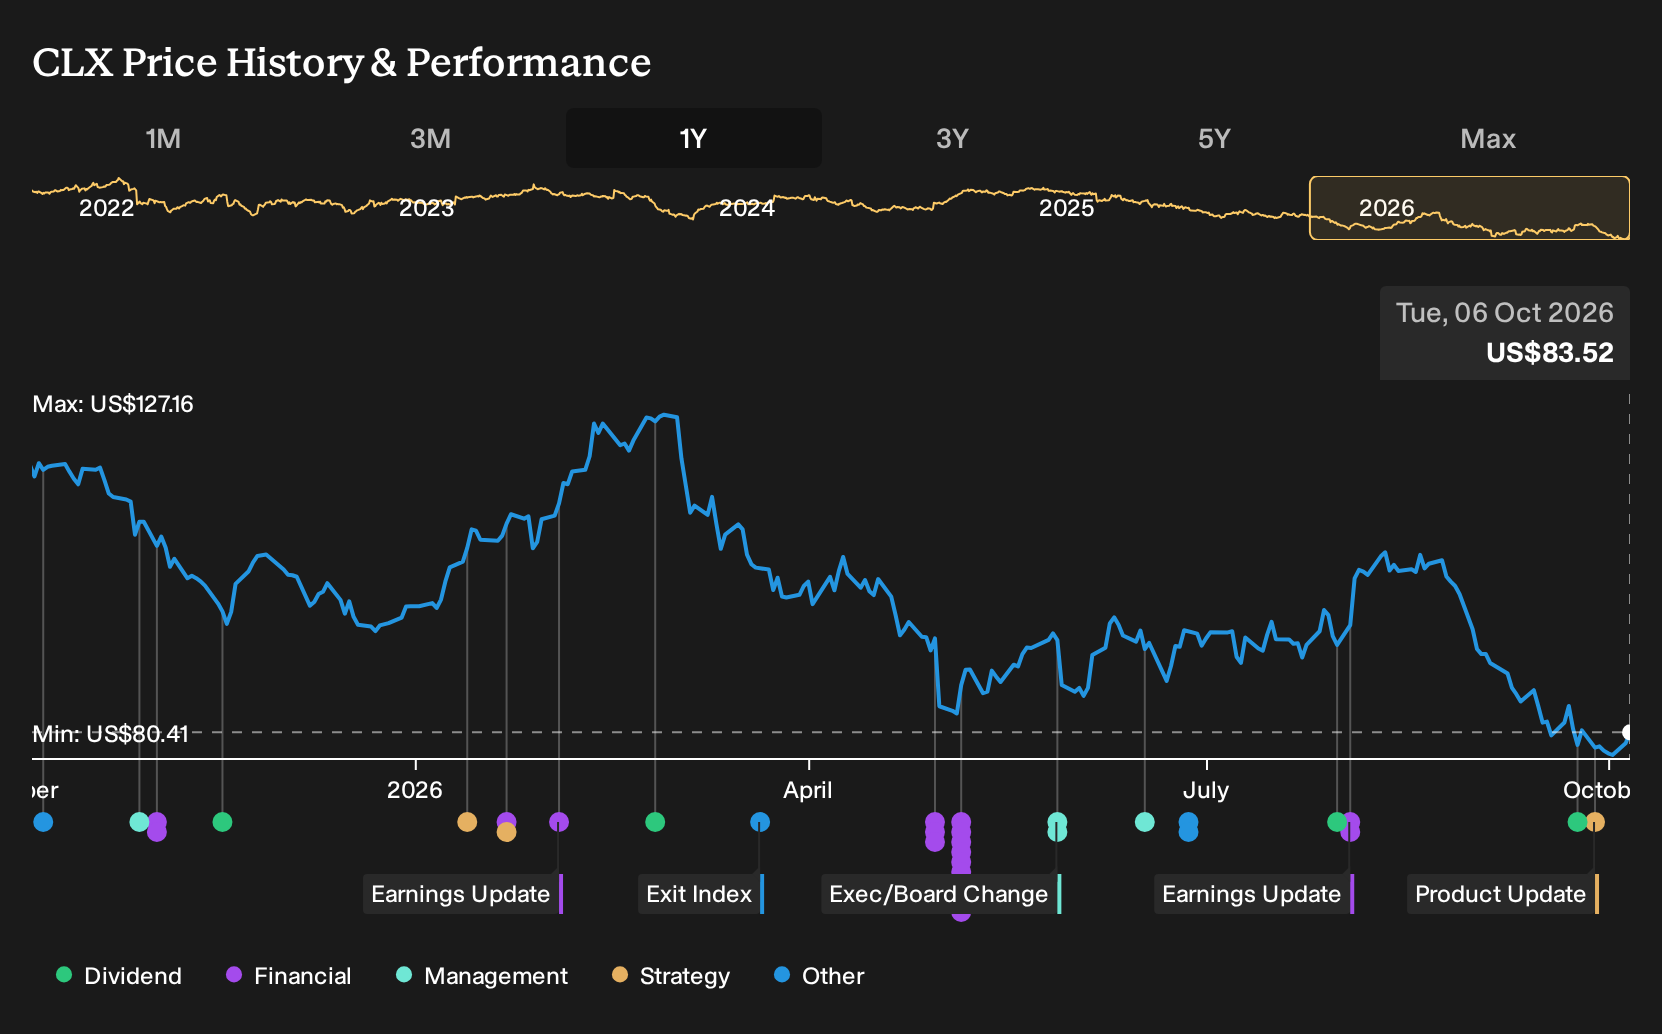
The recent quarterly dividend declaration of US$1.25 per share keeps income front and center for Clorox holders at a time when the stock has fallen 27% on a 1-year total return basis. That payout, combined with earlier commentary around a 6.2% yield, highlights how much of the story still rests on cash returns.
The practical question for investors is whether Purell ProCare, ERP optimization and SG&A efficiency can eventually support that dividend without stretching a balance sheet where debt is not well covered by operating cash flow. If margin progress or free cash flow underwhelm, capital allocation options could narrow and investor patience may be tested.
Clorox's narrative projects US$8.0b revenue and US$807.6 million earnings by 2029. That implies 6.2% yearly revenue growth and an earnings increase of about US$220.6 million from US$587.0 million today.
Uncover why Clorox's fair value indicates a 21% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Some of the most optimistic analysts think Clorox could reach about US$8.2b in revenue and US$894.7 million in earnings by 2029, far above consensus. They put more weight on ERP and product launches than on dividend strain. Your takeaway is simple: smart people disagree. Use this ProCare news to reassess both stories.
Explore 6 other Clorox fair value estimates, including one that suggests as much as 187% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Clorox research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Clorox. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Clorox's overall financial health at a glance.
Looking for more investment ideas beyond Clorox?
Once you have a view on Clorox, broaden your opportunity set by lining it up against other companies that fit the type of portfolio you want to build. The Simply Wall St Screener can help you quickly filter for traits that match your risk tolerance and income or growth goals.
- For investors who care most about capital resilience and steadier profiles, start with a 31 resilient stocks with low risk scores that aims to prioritise durability over drama.
- If you are hunting for value where balance sheets still look robust, scan our 27 high quality undervalued stocks that combines financial strength with attractive pricing signals.
- Income focused readers who want yield supported by solid fundamentals can review a 8 dividend fortresses that concentrates on higher payout opportunities.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com