
How Investors May Respond To NetApp (NTAP) AI Infrastructure Push
- Recent announcements from NetApp and partners cover AI-focused storage platform Novus, expanded hybrid multi cloud controls, new OCI and SAP collaborations, and a Diskover Data tie up that extends governed visibility across ONTAP and StorageGRID for data heavy industries.
- The cluster of product launches and alliances points to NetApp leaning further into AI factories, data governance, and subscription-like services that can reshape how its storage platform is consumed across regulated and file intensive workloads.
- We will now look at how NetApp's AI focused Novus launch fits into the broader investment narrative that investors are already watching.
Scan how NetApp is repositioning around AI data infrastructure, then size up other hand-picked infrastructure plays through our screen of 91 AI infrastructure stocks that could be building similar foundations for GPU demand.
NetApp Investment Narrative Recap
To own NetApp, you need to believe its pivot toward AI data infrastructure, hybrid cloud and subscription services offsets pressure on traditional hardware, regional softness and margin risk from hyperscalers. The short term story still revolves around keeping AI related wins coming while cloud storage and Keystone style offerings build a steadier recurring base.
Recent Novus, OCI and Diskover announcements look directionally helpful but do not obviously change the main near term swing factor, which is execution on large AI and hybrid cloud deployments without eroding profitability. The biggest risk remains intensifying competition and pricing pressure as enterprise workloads keep shifting toward cloud platforms.
The Diskover Data collaboration looks closest to the current news focus. It plugs governed cataloging and cost analytics into ONTAP and StorageGRID for industries that rely on giant file estates, from media production to EDA and scientific research. That ties directly into the AI data plumbing story, since these are the workflows feeding large GPU clusters.
For catalysts, this kind of governed visibility can make NetApp infrastructure more “sticky” as customers move toward AI factories and subscription models. The flip side is execution risk. NetApp must integrate Diskover cleanly, sell it through the channel without confusing Keystone or cloud services positioning, and prove that the extra governance and chargeback features meaningfully influence deals.
NetApp's current analyst narrative points to revenue of $9.4b and earnings of $1.9b by 2029, based on 8.5% yearly revenue growth and an earnings increase of about $0.5b from $1.4b today.
Uncover why NetApp's fair value indicates a 13% potential downside to its current price, a premium that may not hold.
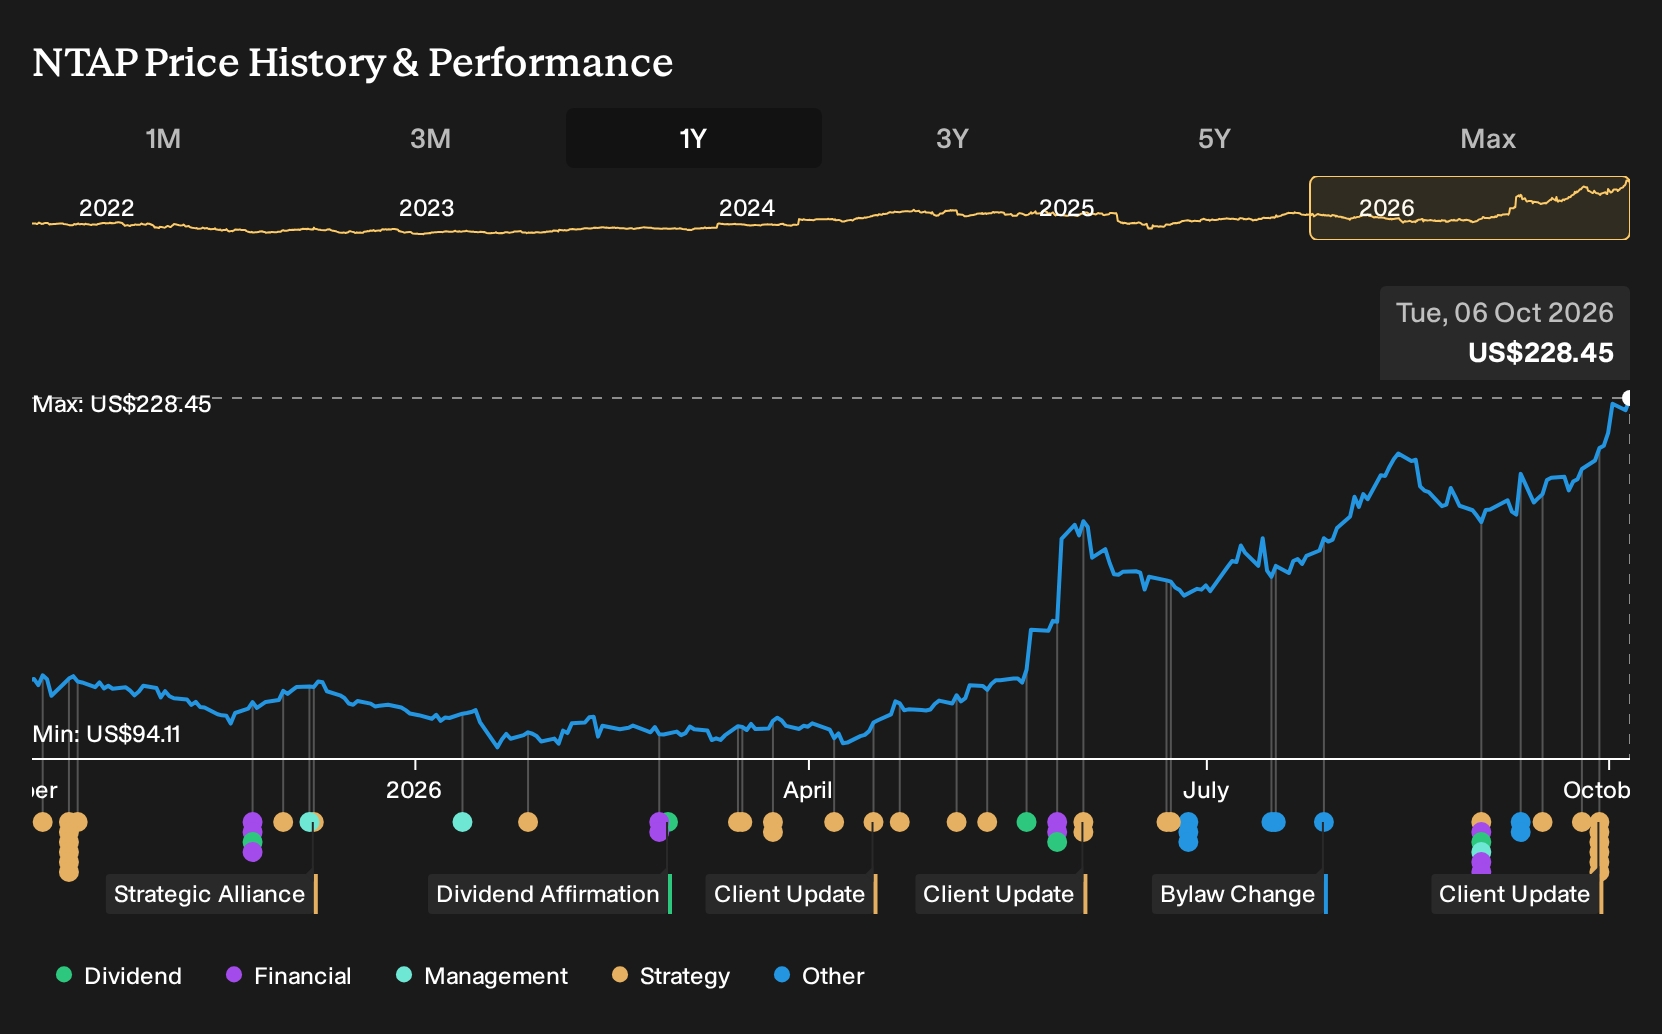
Exploring Other Perspectives
You are seeing one clear disagreement. Consensus assumes NetApp reaches about US$9.4b revenue and US$1.9b earnings by 2029, helped by AI projects lining up behind deals like Diskover. The most cautious analysts only pencil in roughly US$8.6b and US$1.7b. That more hesitant story may shift as these announcements sink in.
Explore 3 other NetApp fair value estimates, including one that suggests as much as 13% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your NetApp research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for NetApp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NetApp's overall financial health at a glance.
Looking for more investment ideas beyond NetApp?
Once you have a view on NetApp, it often helps to zoom out and compare it with other businesses that fit clear financial themes using the Simply Wall St Screener.
- Prefer resilient balance sheets and steady fundamentals over headline stories? Then scan our list of solid balance sheet and fundamentals (25 results) that share those traits.
- If you care most about finding quality at a reasonable price, filter through the 27 high quality undervalued stocks that might line up better with your return expectations.
- For investors who want income on top of potential price gains, focus on our 8 dividend fortresses that combine higher yields with stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com