
Merck KGaA (XTRA:MRK) Opens Wisconsin Semiconductor Hub, Is It Still Below Fair Value?
Merck KGaA’s new US semiconductor hub
Merck KGaA (XTRA:MRK) just expanded its North American footprint with EMD Electronics’ new semiconductor research and development centre in Sheboygan Falls, Wisconsin, part of a multi-year $200 million US investment.
Merck KGaA’s new US semiconductor hub lands at a time when momentum has been rebuilding, with a 14.59% year-to-date share price return and an 18.90% one-year total shareholder return, even though the 3-year and 5-year total shareholder returns remain negative.
Scan other electronics and semiconductor material plays moving on similar themes to Merck KGaA’s expansion by filtering for 91 AI infrastructure stocks in one focused screen.
Merck KGaA is putting real money behind its semiconductor ambitions. The tougher question is whether a €139 share price already captures that story or still leaves room based on current fundamentals.
Most Popular Narrative: 9% Undervalued
Merck KGaA’s most followed valuation story points to a fair value of €153.50, sitting above the recent €139.00 close and putting fresh focus on whether the current price fully reflects its mix of Life Science, Healthcare, and Electronics exposure.
The robust and accelerating growth in the Life Science segment, particularly Process Solutions (with double-digit organic growth, strong order intake, and a sustained book-to-bill above 1), is being driven by increasing global investment and demand in biotechnology and advanced biologics manufacturing. This supports top-line revenue growth and higher operating leverage.
See why 57 investors see Merck KGaA as 9% undervalued.
That fair value of €153.50 is built using a 5.41% discount rate and analyst assumptions on revenue, earnings, and margins over the coming years, so any change in those inputs could shift the estimated upside or downside from today’s level.
Result: Fair Value of €153.50 (UNDERVALUED)
Still, weak Semiconductor Solutions demand and the looming Mavenclad patent expiry leave clear room for Merck KGaA’s earnings path to deviate from this upbeat script.
Find out about the key risks to this Merck KGaA narrative.
Another View on Merck KGaA’s Valuation
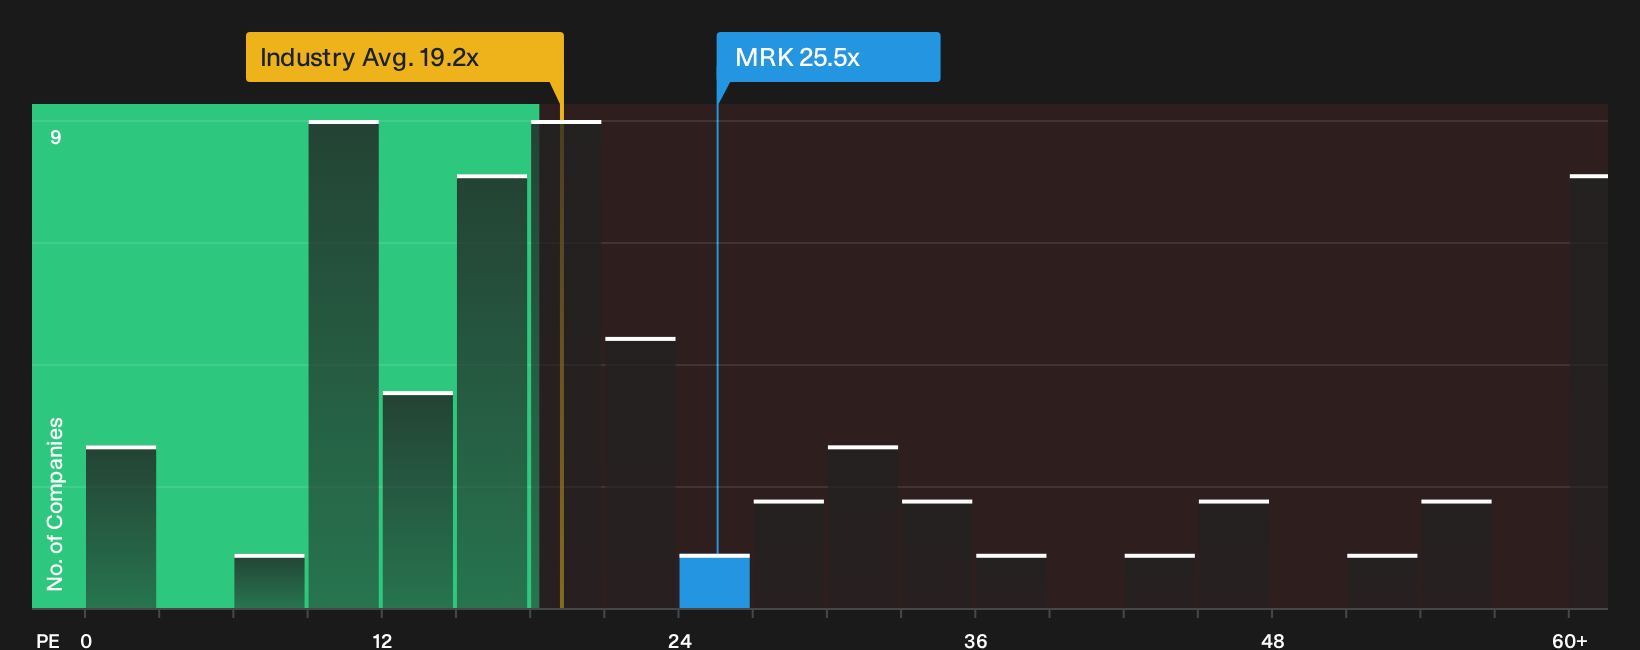
That 9% gap to fair value looks reasonable until the P/E is put under the microscope. Merck KGaA trades at 25.5x earnings compared with 20x for the wider European pharmaceuticals group, yet the fair ratio points to 28.6x. That uplift suggests some upside, but also more room for sentiment to swing if earnings disappoint.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Have you seen enough optimism for one day, or are you still undecided about Merck KGaA’s setup? Act while the data is fresh and pressure test the upside case with 3 key rewards
Looking for more ideas beyond Merck KGaA?
If Merck KGaA has sharpened your focus on valuations and fundamentals, now is the moment to widen your opportunity set with a few targeted screens.
- Target strong upside potential by scanning a curated mix of quality companies that look cheap on fundamentals using the 179 high quality undervalued stocks.
- Lock in income prospects by reviewing a hand picked pool of higher yielding opportunities through the 169 dividend fortresses.
- Reduce portfolio stress by concentrating on sturdier balance sheets and resilient profiles with the 228 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com