
3 Consumer Finance Stocks To Watch As CFPB Scrutiny Eases
Regulators are quietly easing off the brakes. CFPB examiners are cutting back on deep dives into nonbank lenders, and that shift is rippling through subprime and near-prime consumer finance stocks that live and die by enforcement risk. This reset in oversight could reshape margins, funding costs, and investor confidence. The sections that follow spotlight three US-listed lenders exposed to this regulatory turn and explain how the same story can mean opportunity or hazard for your portfolio.
The three lenders highlighted next are a starting sample only, since the full screen surfaced another 8 US subprime and near-prime consumer finance companies with equally compelling regulatory stories that are not covered here.
If you want to go straight to the data and identify your own higher conviction ideas, analyze the full US Subprime and Near-Prime Consumer Lenders with Reduced CFPB Scrutiny screener through the US Subprime and Near-Prime Consumer Lenders with Reduced CFPB Scrutiny screener.
World Acceptance (WRLD)
Overview: World Acceptance is a US consumer finance company that provides small installment loans and related services to higher risk borrowers.
Operations: The business generates about US$591 million in consumer finance revenue from customers across the United States, reflecting its focus on domestic subprime and near prime lending.
Market Cap: US$797 million
World Acceptance is directly tied to the screener theme because it lends to higher risk consumers who have limited access to banks. Its profitability has historically been sensitive to how actively regulators address fees, underwriting practices and collections. Investors considering subprime exposure may focus on potential changes in CFPB scrutiny, with outcomes depending in part on how one unresolved regulatory issue is ultimately addressed.
That unresolved issue could be the fulcrum for World Acceptance’s next chapter, so review the 1 key reward and 3 important warning signs (1 is major!) before this regulatory window shifts again.
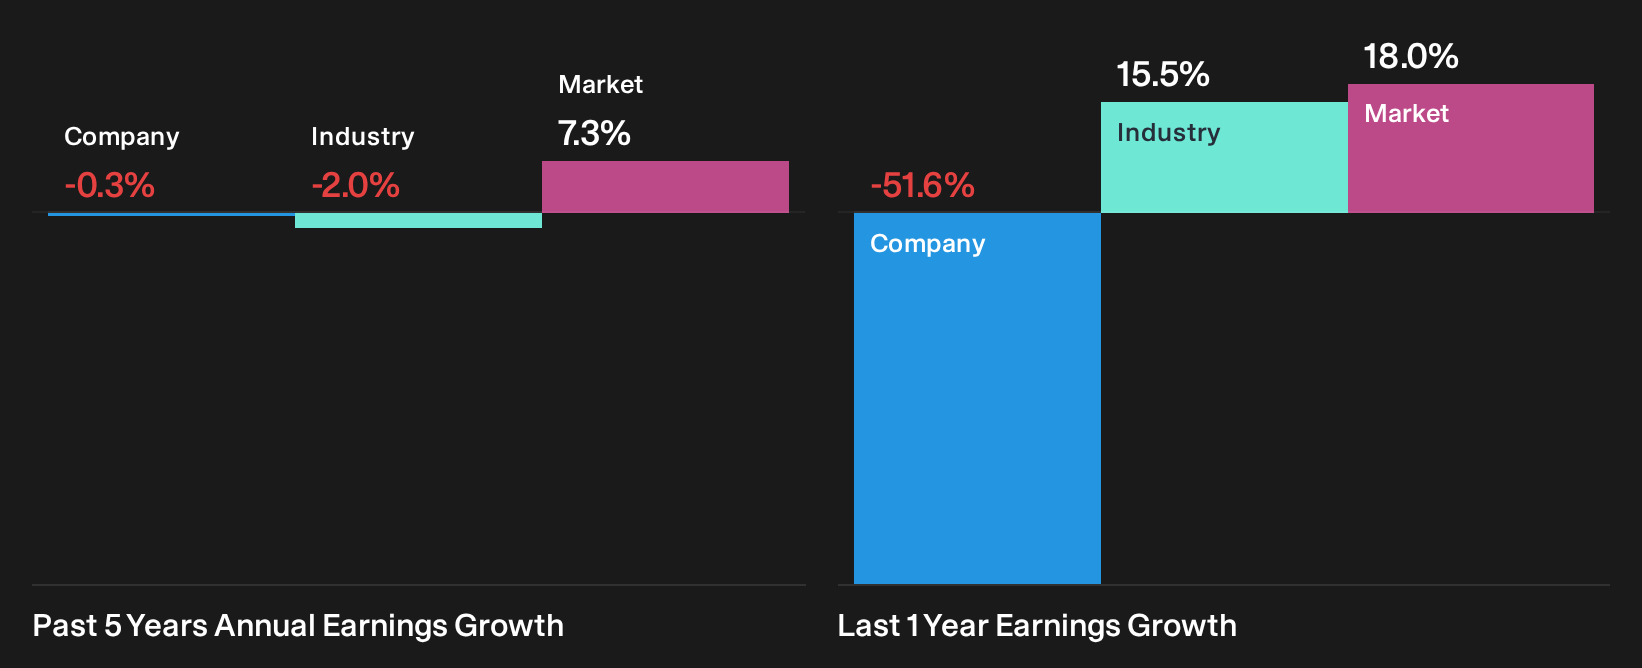
Regional Management (RM)
Overview: Regional Management provides installment loans and related insurance products to US subprime and near-prime borrowers who have limited access to traditional bank credit.
Operations: Regional Management generates about US$648 million of consumer finance revenue entirely in the United States, reflecting a focused domestic lending footprint.
Market Cap: US$302 million
Regional Management matters for this reduced CFPB scrutiny screen because it sits squarely in the nonbank installment lending niche regulators watch most closely. At the same time, its funding model and supervision track record give it meaningful room to benefit if the lighter touch holds.
"While the Column bank partnership currently delivers an estimated pre tax margin lift of about 200 basis points and represents roughly 28% of originations, the plan to extend this model to nearly all states by the end of 2027 concentrates execution and regulatory risk into a single funding channel. Any disruption or underperformance here could compress net margins and slow net income growth compared with what the higher margin profile implies."
What happens if a single, concentrated source of higher yielding loans hits friction could be the swing factor for margins and growth.
That concentration risk is only half the story, and the full narrative for Regional Management shows how Regional Management could still convert this model into accelerating returns if execution holds.
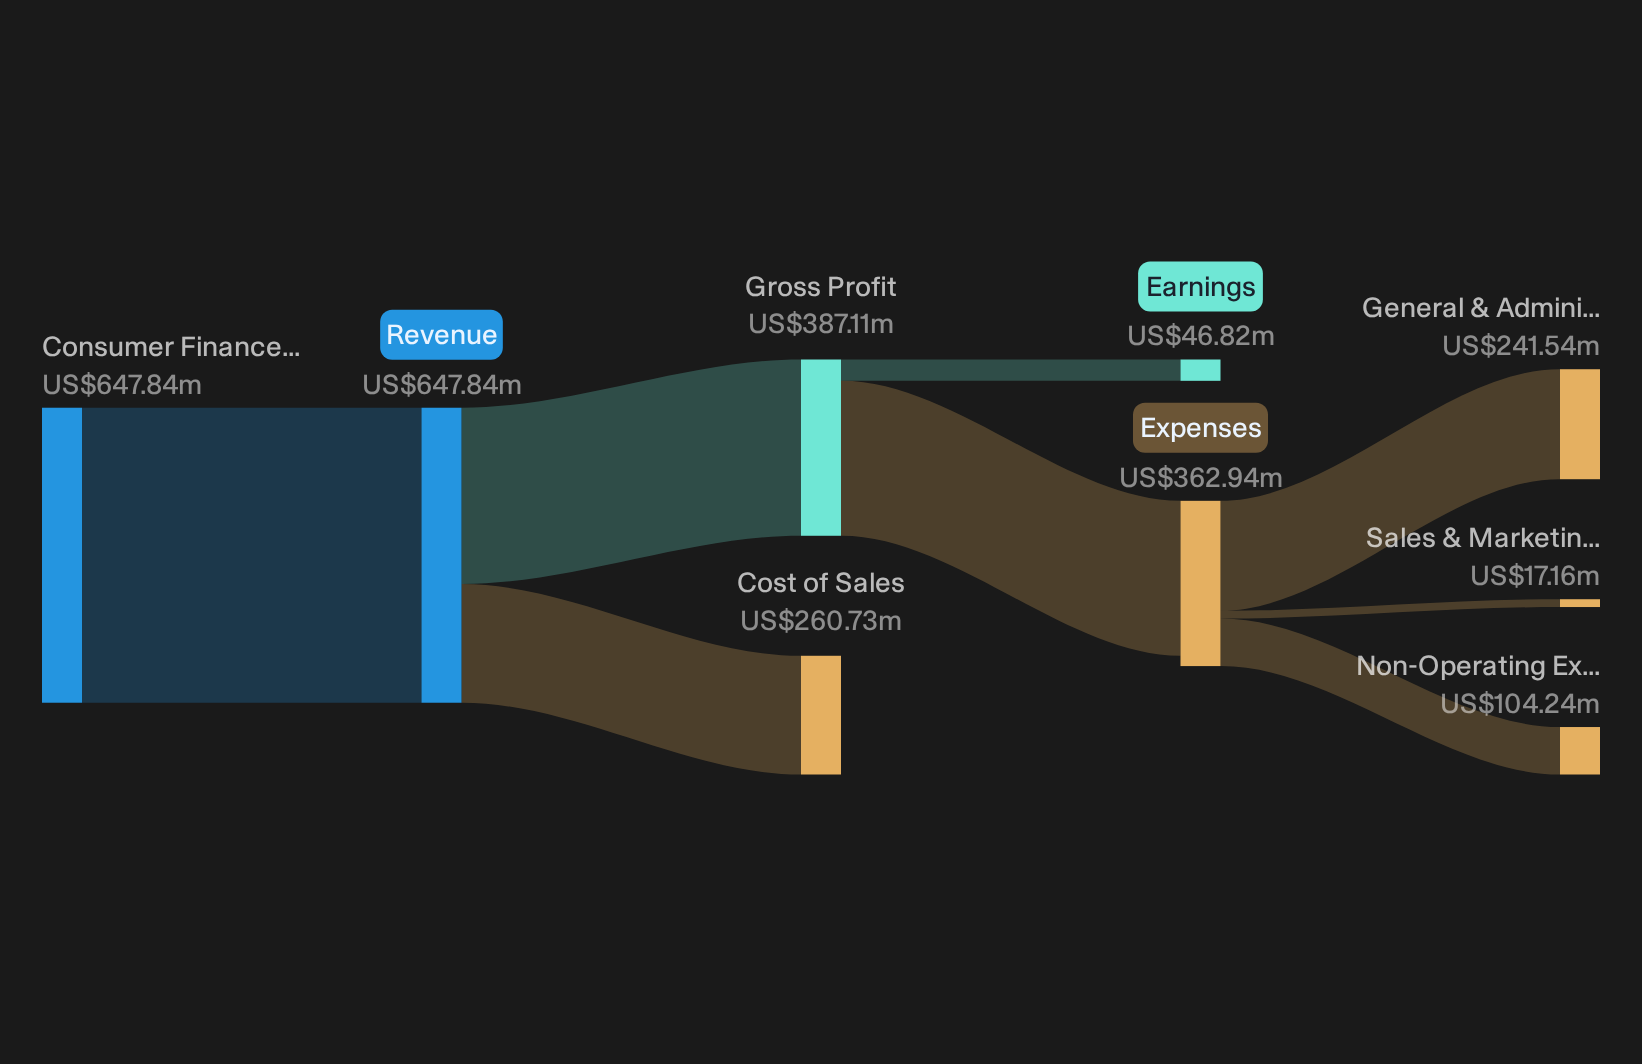
Enova International (ENVA)
Overview: Enova International is an online lender that uses technology and data to offer small consumer and business loans to higher risk borrowers.
Operations: Enova International generates about US$1.69b in consumer financial services revenue, with roughly US$3.36b of total revenue primarily from the United States.
Market Cap: US$4.43b
Enova International sits at the sharp end of this screener theme because its online subprime and near prime lending model reacts quickly when the CFPB either tightens the screws or, as now, steps back from intensive exams and heavy enforcement. This can amplify every regulatory nudge into real earnings consequences.
"Heightened regulatory scrutiny and tightening of consumer lending laws, particularly around high-cost, nonprime, and subprime borrowing, could force Enova to curtail certain product offerings or materially change underwriting, reducing its potential customer base and putting ongoing pressure on revenue over the long term."
What happens if a single regulatory assumption underpinning Enova International’s current growth and margin profile suddenly shifts in the opposite direction?
If that regulatory assumption snaps, you will want the full narrative for Enova International that explains how Enova International could adjust its strategy.

Seeking Alternatives Before Everyone Else?
Fresh themes tend to move first. Prices follow. Late money can get caught chasing momentum. Scan under the radar for now, while it matters, and aim to position early.
- Look for steady payers before yields get compressed by yield hunters using the curated 8 dividend fortresses built to spotlight income ideas that still appear under the radar.
- Track high conviction defensives that may hold up when weaker balance sheets start dropping by tapping into the curated list of solid balance sheet and fundamentals (25 results).
- Identify early-stage AI leaders with real revenue traction, not just hype, through the focused 35 profitable AI stocks that aren't just burning cash before the crowd fully prices in that momentum.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com