
Bright Horizons Family Solutions (BFAM) Faces A Fair Value Debate, Is A 26% Upside Real?
Bright Horizons Family Solutions (BFAM) has drawn attention after recent trading left the stock down about 5% over the past month and roughly 11% over the past 3 months, which has sharpened focus on its childcare and workforce services model.
Short-term momentum has picked up, with a 1-day share price return of 3.44% and 7-day share price return of 4.12%. However, Bright Horizons Family Solutions still reflects weaker sentiment, given its year-to-date share price decline of 33.11% and 1-year total shareholder return down 33.31%.
Compare Bright Horizons Family Solutions with other beaten-down opportunities by scanning our hand picked list of 27 high quality undervalued stocks, which shows fundamentals that appear stronger than recent share price moves suggest.
Bright Horizons Family Solutions runs a large childcare and employer services network, yet the share price has pulled back hard this year. Is a solid operator now being offered at an attractive valuation, or still priced for perfection?
Most Popular Narrative: 26% Undervalued
Against a last close of $66.42, the most followed narrative for Bright Horizons Family Solutions points to a fair value of about $89.44, which frames recent share price weakness alongside a more optimistic view of the business mix and cash generation.
The expansion of employer-sponsored childcare and growing demand from large corporate clients is now supported by multi-year evidence of companies adding back-up care and educational advisory on top of full-service childcare, which can deepen Bright Horizons Family Solutions client relationships and support higher recurring revenue and earnings over time.
See why 1 investors see Bright Horizons Family Solutions as 26% undervalued.
Result: Fair Value of $89.44 (UNDERVALUED)
Still, if full service childcare occupancy stalls and Australian losses linger, the optimistic Bright Horizons Family Solutions earnings mix story could quickly lose support.
Find out about the key risks to this Bright Horizons Family Solutions narrative.
Another View on Bright Horizons Family Solutions Valuation
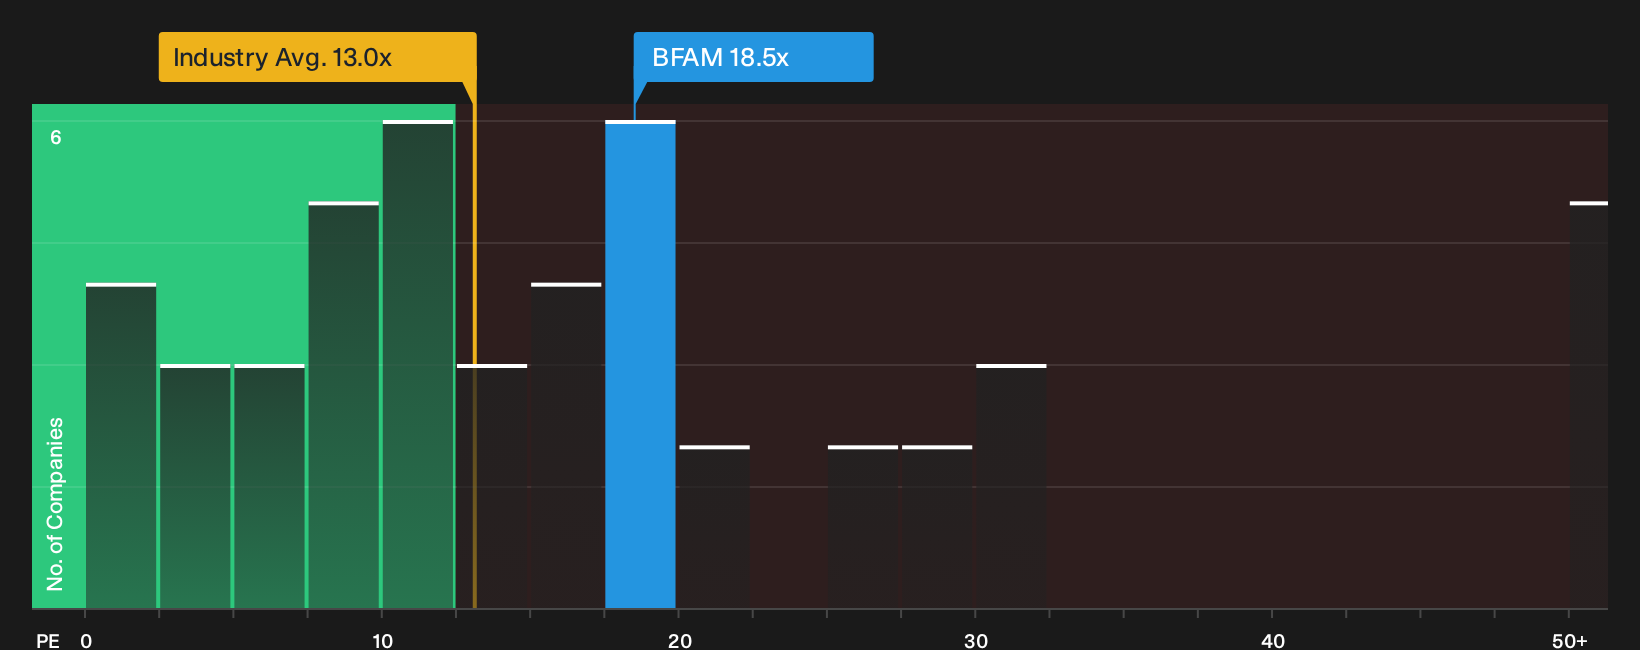
The earlier narrative leaned on future earnings and a fair value of $89.44, yet the current P/E of 18.5x paints a different picture. Bright Horizons Family Solutions trades above the US Consumer Services average of 12.9x, while its fair ratio is 21.6x. This leaves investors weighing valuation risk against the possibility of a re rating.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Bright Horizons Family Solutions is clearly split, so consider moving quickly, reviewing the underlying metrics, and then weighing the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Bright Horizons Family Solutions?
If Bright Horizons Family Solutions has your attention, do not stop here. Broaden your watchlist with a few focused stock pools built around clear, data driven themes.
- Target resilient balance sheets and steady fundamentals by scanning a carefully filtered list of solid balance sheet and fundamentals (25 results) that keeps financial strength front and center.
- Hunt for mispriced quality by reviewing a curated 27 high quality undervalued stocks where fundamentals appear stronger than what current share prices imply.
- Spot early stage opportunities before the crowd by working through a focused 19 high quality undiscovered gems built to surface lesser known, fundamentally driven ideas.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com