
How CFO Appointment Will Impact Teleperformance Stock Investors
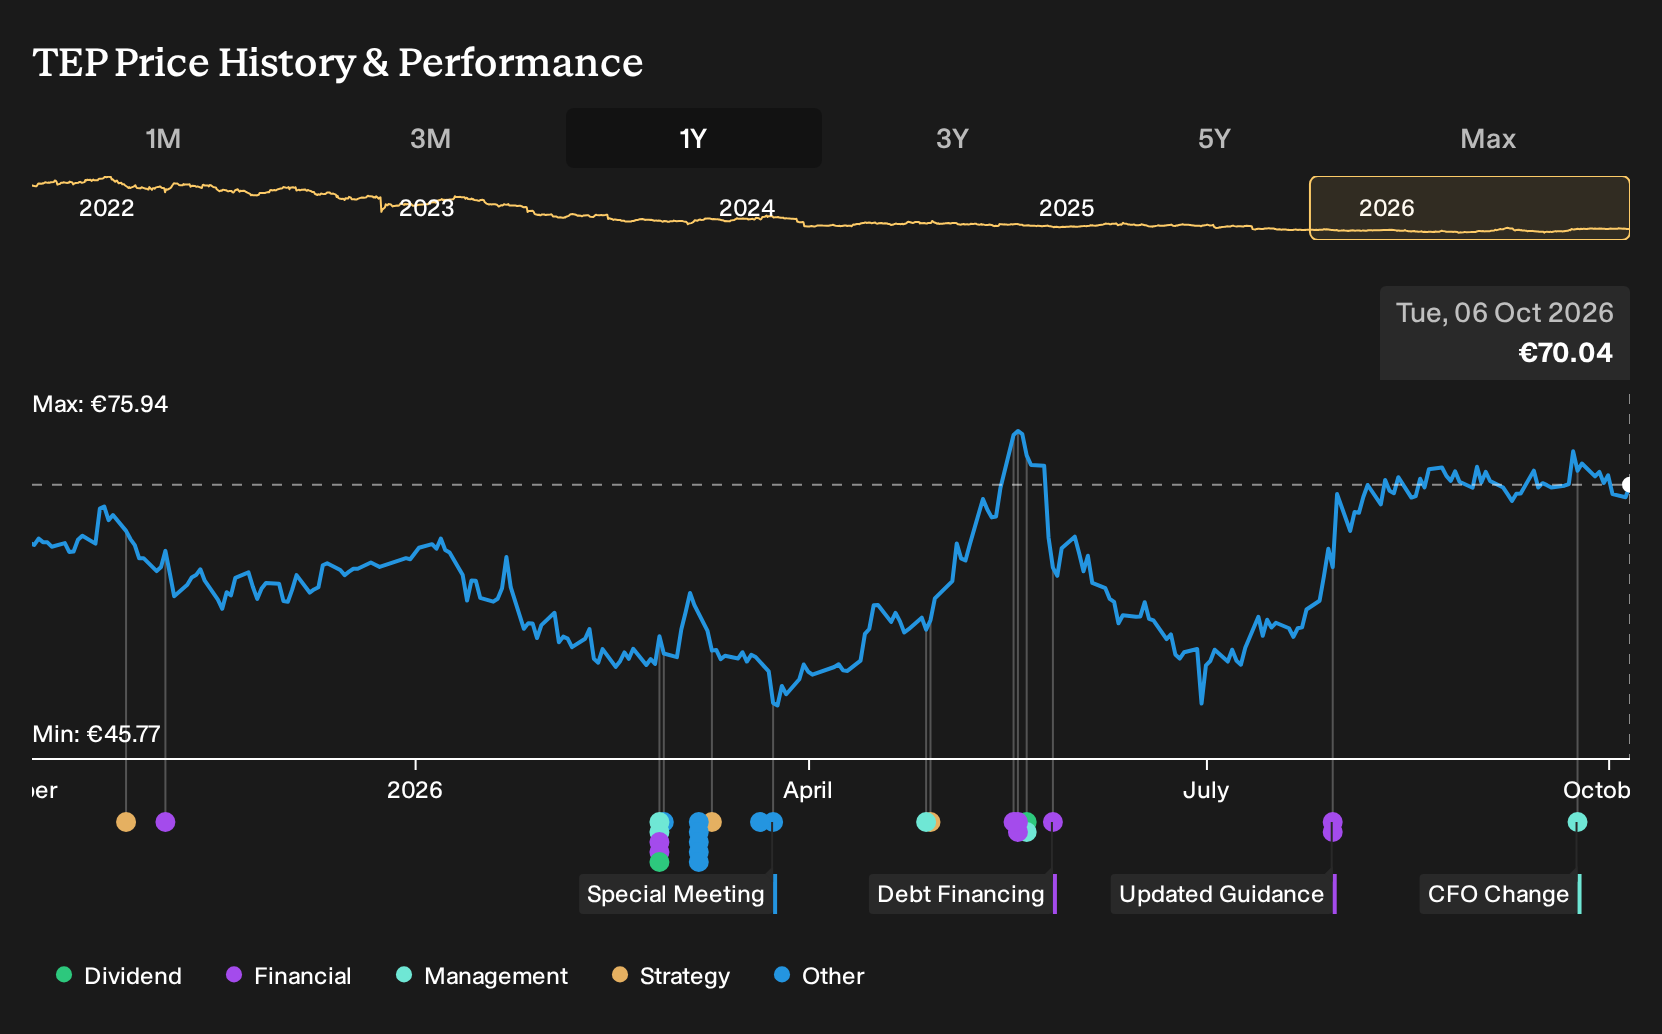
- Teleperformance confirmed that Benoit Gabelle, who had been Interim Group Chief Financial Officer since March 2026, was formally appointed Group CFO on 24 September 2026, after joining the group in 2022 as Deputy CFO overseeing reporting, tax, accounting and finance transformation.
- Gabelle’s track record with Teleperformance on unified financial systems, the Majorel integration, refinancing and the efficiency program directly links the finance role to execution of the group’s ongoing transformation agenda.
- We will look at how Teleperformance's investment narrative is influenced by Benoit Gabelle's focus on modernizing the finance function and capital structure.
Teleperformance Investment Narrative Recap
To own Teleperformance, you need to believe the group can turn a complex, capital intensive service model into steadier cash generation as AI projects, geographic mix and Specialized Services all settle. The main near term swing factor is whether operational execution in areas like efficiency programs and contract retention offsets currency headwinds and patchy demand in parts of the portfolio.
The biggest risk remains pressure in Specialized Services and U.S. interpretation volumes, combined with high debt and the impact of past one off items on earnings quality. Gabelle’s formal appointment as CFO does not radically change those near term drivers. It mainly reduces uncertainty around who steers the balance sheet and liquidity plan.
The most relevant piece tied to this CFO news is Teleperformance’s ongoing refinancing and efficiency program, which Gabelle already helped shape as Deputy CFO. Your focus here is simple: can this effort keep interest costs and leverage in check while the business invests in AI, cloud and integration work without stretching free cash flow further?
If refinancing stays disciplined, it can support the existing equity story where the stock screens as “good value” on several P/E checks and still carries a 6.42% dividend yield. If execution slips, the combination of volatile Specialized Services, FX pressure and high reliance on external borrowing can amplify earnings swings and keep the share price choppy.
What The New CFO Means For Teleperformance’s Targets
Teleperformance's narrative projects €10.3b revenue and €607.3m earnings by 2029. This implies largely flat yearly revenue trends and about a €110m earnings increase from €497.0m today.
Discover why Teleperformance's fair value indicates a 7% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
For Teleperformance, the sharpest contrast comes from bearish analysts who treat AI driven cost savings as the key risk. They worry the Future Forward plan and TP.ai roll out might need more restructuring, which could keep earnings nearer €519.4m on €9.8b revenue by 2029. Their pre announcement view is far more cautious than consensus, so you may want to compare both sets of assumptions and decide which story feels closer to your own interpretation of the new CFO appointment.
Explore 6 other Teleperformance fair value estimates, including one that suggests as much as 36% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so trust your own analysis.
- A great starting point for your Teleperformance research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Teleperformance. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Teleperformance's overall financial health at a glance.
Looking For More Investment Ideas Beyond Teleperformance?
Teleperformance might be the focus today, but your portfolio benefits when you keep a watchlist of other potential opportunities that match different goals, whether that is income, value or resilience.
- For investors who want potential value combined with quality fundamentals, scan a curated set of 179 high quality undervalued stocks that may warrant a closer look.
- If income is your priority and you care about reliability as much as yield, review a focused group of 169 dividend fortresses that aim to balance payout size with staying power.
- When capital preservation matters most, start with a carefully filtered 228 resilient stocks with low risk scores that screens for businesses scoring well on financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com