
Atlas Copco (OM:ATCO A) Extends Its Run As Service Growth Keeps Valuation In Focus
Atlas Copco (OM:ATCO A) has come into focus after fresh performance data showed a one day return of 2.2% and a one month gain of 5.7%, extending a 3 month move of 15.2%.
That latest move builds on a clear upswing in Atlas Copco’s momentum, with a 27.21% year to date share price return and a 28.52% total shareholder return over the past year, signalling that investors are reassessing both growth potential and risk around the SEK213.4 share price.
Compare Atlas Copco’s recent surge with a curated group of industrial peers by using the list of solid balance sheet and fundamentals (206 results) as the starting universe for analysis.
After that kind of run, Atlas Copco now sits close to its stated price target. The question is whether most of the easy upside has already played out or if valuation still leaves meaningful room above SEK213.4.
Most Popular Narrative: 2% Undervalued
On the latest figures, Atlas Copco’s narrative fair value of SEK218.48 sits only slightly above the SEK213.4 close. As a result, the debate shifts from big upside to whether the current price really reflects the story on growth, margins and risk.
The expanding, high-margin service and aftermarket business continues to grow robustly across business areas, increasing recurring revenue streams and helping to stabilize and lift group operating margins even amid volatility in equipment orders.
See why 31 investors see Atlas Copco as 2% undervalued.
Result: Fair Value of SEK218.48 (ABOUT RIGHT)
Still, the Atlas Copco story can break if large compressor and Gas & Process orders stay soft or if currency swings continue to pressure margins.
Find out about the key risks to this Atlas Copco narrative.
Another View: Atlas Copco Looks Expensive On Earnings
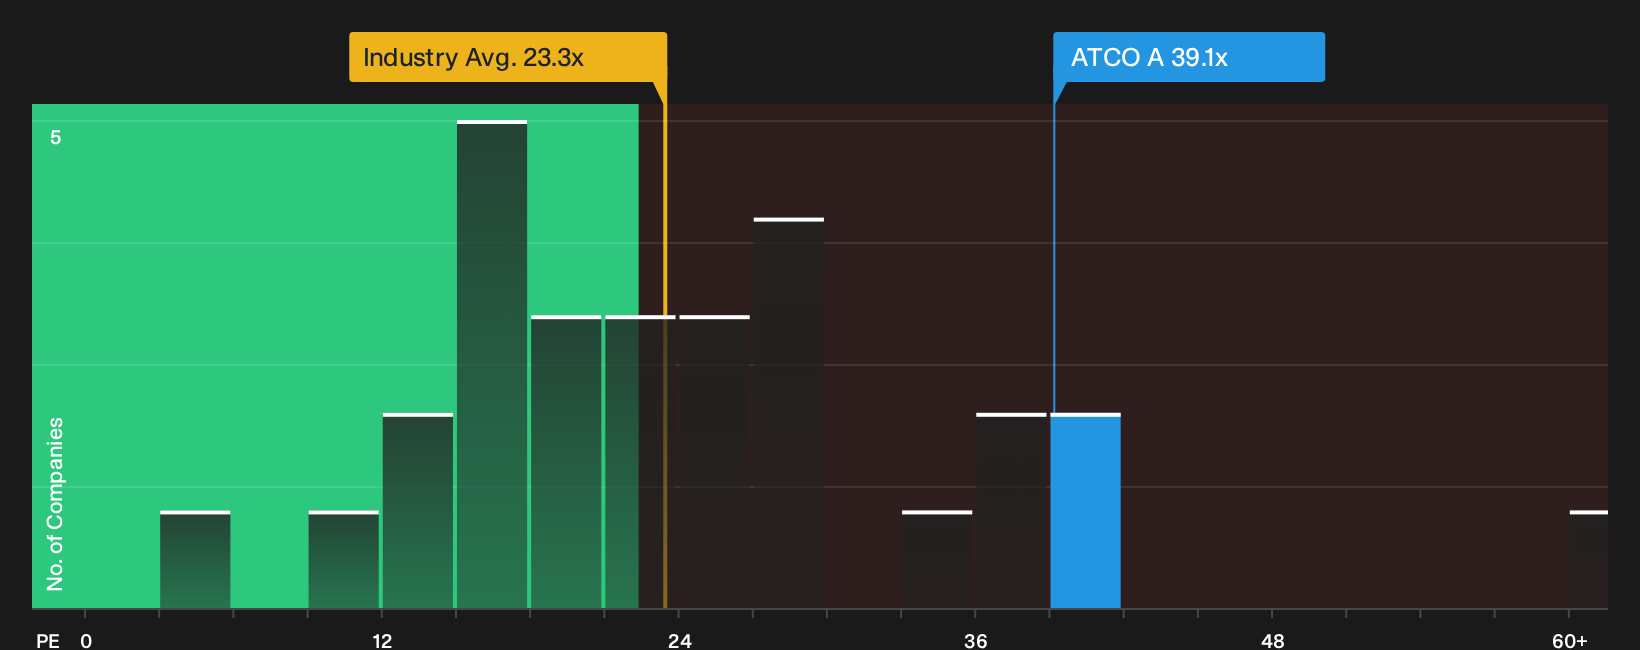
The analyst narrative pegs Atlas Copco close to fair value around SEK218.48. On simple earnings maths, the picture is less forgiving. The current P/E of 39.1x is higher than the Swedish Machinery industry at 23.4x, above peers at 27.9x and above a fair ratio of 35.9x. That gap points to valuation risk if expectations cool.
For a closer look at how this earnings based view compares with a full cash flow approach, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Does this mix of optimism and valuation risk feel balanced enough for you, or a bit stretched? Move quickly and review Atlas Copco’s upside drivers in the 1 key reward
Looking for more investment ideas beyond Atlas Copco?
If Atlas Copco has sharpened your focus, do not stop here. Fresh ideas often come from scanning beyond familiar tickers, before the crowd catches on.
- Target higher quality value by reviewing the 180 high quality undervalued stocks that combine solid fundamentals with prices that may not fully reflect them.
- Strengthen income potential by focusing on companies in the 169 dividend fortresses where yields are paired with robust underlying businesses.
- Dial down risk in your watchlist by searching within the 228 resilient stocks with low risk scores that score well on financial resilience and balance sheet strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com