
Top Growth Companies With Strong Insider Stakes October 2026
Over the last 7 days, the United States market has risen 2.2%, contributing to a 14% increase over the past year, with earnings forecasted to grow by 18% annually. In such a robust environment, stocks with high insider ownership can be particularly appealing as they often signal confidence in the company's potential for sustained growth and alignment of interests between management and shareholders.
Top 10 Growth Companies With High Insider Ownership In The United States
| Name | Insider Ownership | Earnings Growth |
| Upstart Holdings (UPST) | 14.0% | 68.4% |
| Standard Nuclear (STDN) | 18.8% | 64.2% |
| Sable Offshore (SOC) | 11.6% | 76% |
| Precigen (PGEN) | 11.7% | 54% |
| Nu Holdings (NU) | 22.8% | 22.3% |
| Karman Holdings (KRMN) | 14.4% | 56.4% |
| Himax Technologies (HIMX) | 29.1% | 70.2% |
| Figure Technology Solutions (FIGR) | 21.4% | 32.2% |
| Dave (DAVE) | 16.6% | 24.1% |
| Almonty Industries (ALM) | 10.8% | 57.0% |
Let's explore several standout options from the results in the screener.
Elmet Group (ELMT)
Simply Wall St Growth Rating: ★★★★★☆
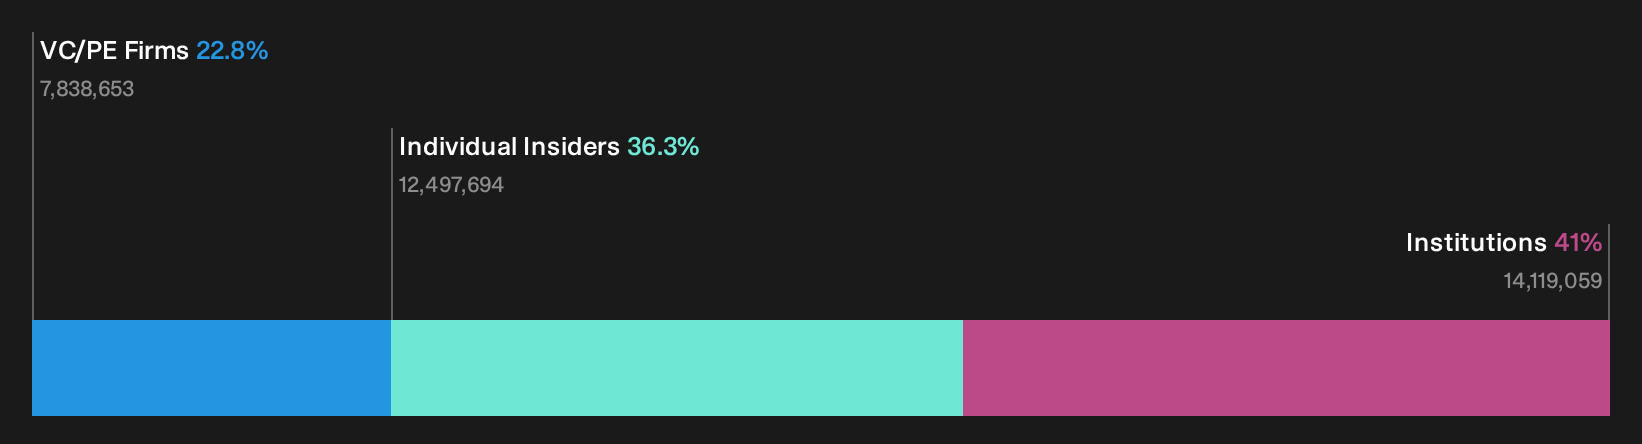
Overview: Elmet Group Co. manufactures and sells precision-engineered components and high-energy systems for various industries, including aerospace and defense, with a market cap of $648.48 million.
Operations: The company generates revenue through its Engineered Microwave Products (EMP) segment, which accounts for $32.14 million, and its Critical Materials and Components (CMC) segment, contributing $196.39 million.
Insider Ownership: 39%
Revenue Growth Forecast: 31.7% p.a.
Elmet Group demonstrates significant growth potential with its revenue expected to grow 31.7% annually, outpacing the US market. Despite recent volatility in share price, the company is trading at nearly 41% below fair value estimates, suggesting potential undervaluation. Elmet's strategic moves include a tungsten concentrate offtake agreement and a substantial investment in Blue Moon Metals’ Springer Tungsten Complex. These initiatives align with government-backed efforts to strengthen critical material supply chains across various industries.
- Delve into the full analysis future growth report here for a deeper understanding of Elmet Group.
- The valuation report we've compiled suggests that Elmet Group's current price could be inflated.
Teamshares (TMS)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Teamshares Inc. currently does not have significant operations and has a market cap of $547.55 million.
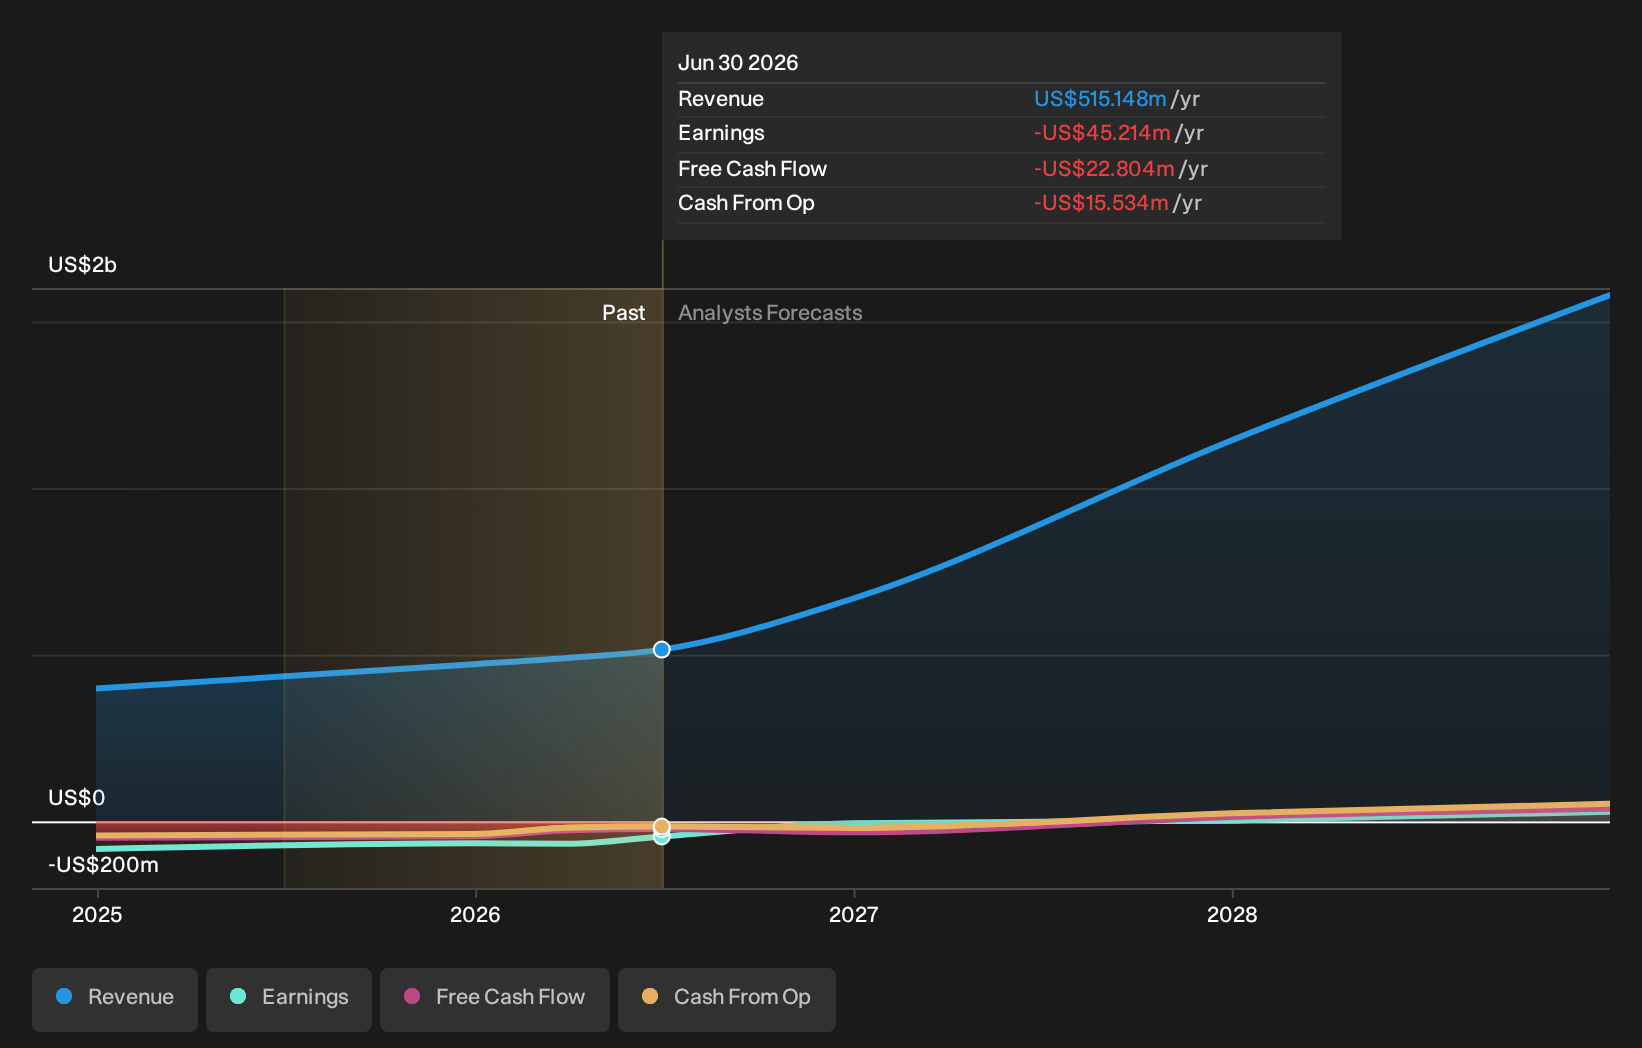
Operations: The company's revenue primarily comes from the Small-To-Medium-Sized Enterprises (SME) segment, amounting to $515.15 million.
Insider Ownership: 10%
Revenue Growth Forecast: 33.3% p.a.
Teamshares Inc. showcases robust growth potential with revenue forecasted to expand by 33.3% annually, surpassing the US market average. The company recently reported a significant turnaround in profitability, achieving a net income of US$9.17 million for Q2 2026 compared to a loss last year. Despite high share price volatility, Teamshares is trading at an attractive value relative to peers and industry benchmarks, supported by its inclusion in the S&P TMI Index and recent capital raising activities totaling US$225 million through preferred stock issuance.
- Click to explore a detailed breakdown of our findings in Teamshares' earnings growth report.
- Our expertly prepared valuation report Teamshares implies its share price may be lower than expected.
XPeng (XPEV)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: XPeng Inc. is a physical AI company with a market capitalization of approximately $8.99 billion.
Operations: The company's revenue is primarily generated from vehicle sales and related business, amounting to CN¥75.41 billion.
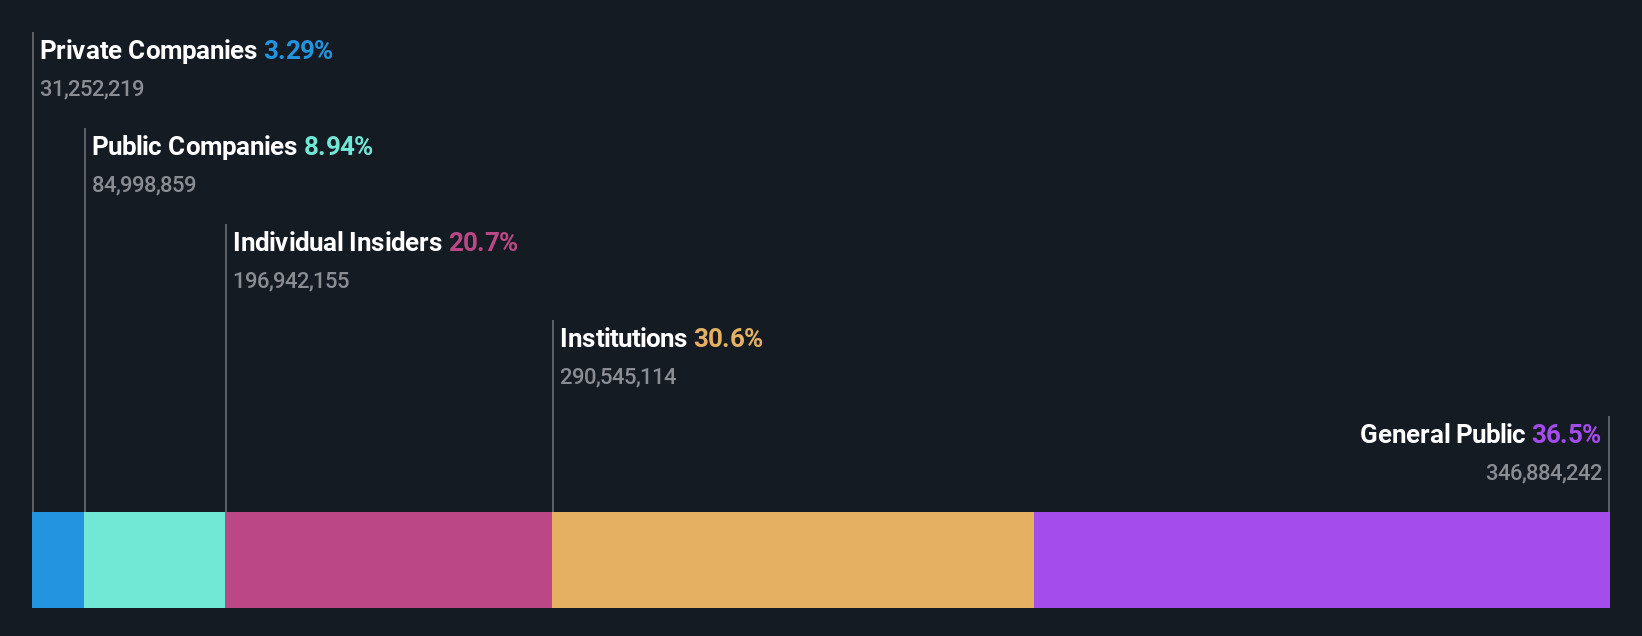
Insider Ownership: 20.8%
Revenue Growth Forecast: 17.4% p.a.
XPeng Inc. is poised for robust growth, with revenue projected to increase by 17.4% annually, outpacing the US market average. The company aims to achieve profitability within three years and recently reported a 15% quarterly increase in vehicle deliveries, reaching 118,390 units in Q3 2026. Despite a net loss of CNY 3.12 billion for H1 2026, XPeng's strategic innovations and partnerships are enhancing its global expansion and product development capabilities.
- Take a closer look at XPeng's potential here in our earnings growth report.
- The valuation report we've compiled suggests that XPeng's current price could be quite moderate.
Seize The Opportunity
- Click here to access our complete index of 183 Fast Growing US Companies With High Insider Ownership.
- Searching for a Fresh Perspective? The end of cancer? These 35 emerging AI stocks are developing tech that will allow early idenification of life changing disesaes like cancer and Alzheimer's.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com