
Neurocrine Biosciences (NBIX) After New VYKAT XR Data Why The Undervalued Narrative Persists
Neurocrine Biosciences (NBIX) is back in focus after announcing a slate of new VYKAT XR and Prader Willi syndrome data that will be presented at the FPWR 2026 conference in Philadelphia.
Those fresh VYKAT XR findings come after a choppy stretch for Neurocrine Biosciences, with the share price up 5.18% over the past week but down 18.36% over 90 days, while the 1 year total shareholder return of 6.21% and 5 year total shareholder return of 38.77% point to steadier long term momentum.
Scan how Neurocrine Biosciences compares with other under the radar healthcare and biotech plays by checking our curated list of 19 high quality undiscovered gems today.
After a sharp 90 day pullback and fresh excitement around VYKAT XR, Neurocrine Biosciences now sits at a very different entry point. Do the current terms still compensate you for the risks on the table?
Most Popular Narrative: 30% Undervalued
The most followed narrative now pegs Neurocrine Biosciences at a fair value of about $207.81 per share versus the recent $145.51 close. This frames the current volatility against a model that leans heavily on execution in its neurology and endocrine franchises.
A broad, late-stage and diversified CNS pipeline, including multiple Phase III programs targeting major depressive disorder and schizophrenia, leverages advances in precision medicine and increases visibility for future earnings, supporting potential future valuation multiple expansion.
See why 49 investors see Neurocrine Biosciences as 30% undervalued.
Result: Fair Value of $207.81 (UNDERVALUED)
Still, the Neurocrine Biosciences story can break if pricing pressure on INGREZZA intensifies, or if VYKAT XR safety concerns slow adoption more than analysts currently factor in.
Find out about the key risks to this Neurocrine Biosciences narrative.
Another View: What Multiples Say About Neurocrine Biosciences
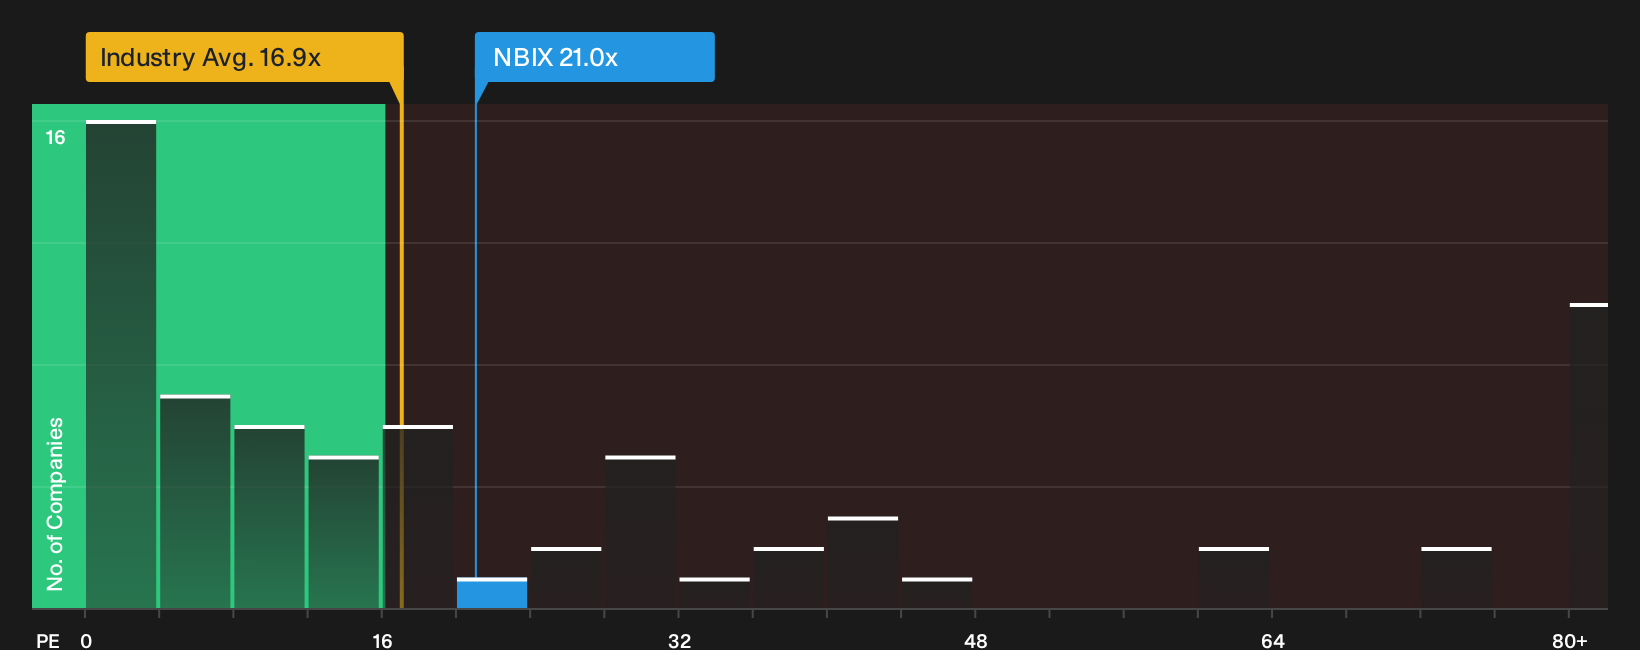
There is a different signal once you shift from fair value models to simple market ratios. Neurocrine Biosciences trades on roughly 21x earnings, which is higher than the US Biotechs average of 16.9x, yet below its own fair ratio of 25.3x and far under a 52.6x peer average. Is that a margin of safety or a warning that future expectations already carry a premium?
To pressure test this second lens before making any decisions, it is worth seeing how the current price compares with a fuller breakdown of earnings, peers and that 25.3x fair ratio. Then consider what would need to change in your own thesis for the share price to move closer to it. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Neurocrine Biosciences is split, so it helps to move fast, check the underlying data, and pressure test every assumption yourself. To see what the current optimism is based on, start with the 4 key rewards.
Looking for more Neurocrine Biosciences sized ideas?
If you stop with Neurocrine Biosciences, you risk missing other opportunities that better match your goals, risk comfort and preferred timelines across the market.
- Target quality at a discount by checking companies on our 27 high quality undervalued stocks with stronger fundamentals than their current prices suggest.
- Prioritise resilience by scanning the 31 resilient stocks with low risk scores that pair steadier business profiles with more controlled risk scores.
- Strengthen your core holdings by reviewing the list of solid balance sheet and fundamentals (25 results) to find businesses backed by healthier financial foundations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com