
Is Innovent Biologics (SEHK:1801) Undervalued After Jaypirca Approval And New IBI3003 Data?
Innovent Biologics (SEHK:1801) is back in focus after two cancer drug updates. China’s NMPA cleared Jaypirca for broader CLL/SLL use, and new Phase 1 data for IBI3003 in multiple myeloma drew attention.
These twin drug updates hit a market that has already been warming to Innovent Biologics, with the share price at HK$97.5 after a 90-day share price return of 12.91% and a three-year total shareholder return of 127.27%, even though the one-year total shareholder return is down 6.88%.
Capitalize on the momentum around Innovent Biologics by scanning a curated 126 healthcare AI stocks that could benefit from similar breakthroughs in complex diseases.After a sharp three year climb and a softer 12 month patch, Innovent Biologics now trades at HK$97.5. Does that set up a relatively fair entry today, or does it argue for patience and a better price later?
Preferred P/E of 117.7x: Is it justified?
On simple earnings math, Innovent Biologics looks expensive. The shares last closed at HK$97.5 while the stock trades on a P/E of 117.7x compared with a peer average of 28.1x and a Hong Kong Biotechs industry average of 18.4x.
The P/E ratio compares the current share price with earnings per share. For a research heavy biopharma group like Innovent Biologics, a steep multiple often reflects expectations for strong profit expansion rather than current profitability alone.
Analysts currently expect earnings to grow 33.5% per year and revenue to rise 18.8% per year, which is ahead of the broader Hong Kong market on both measures. That helps explain why the market is paying a P/E of 117.7x, although the estimated fair P/E of 38.3x and a calculated 35.2% discount to an intrinsic value of HK$150.42 suggest the current pricing could still be rich relative to the level the valuation model points toward over time.
The comparison with the Hong Kong Biotechs group is stark. A P/E of 117.7x is more than 6x the industry average of 18.4x, while it also runs well ahead of the peer set at 28.1x. The gap to the estimated fair P/E of 38.3x is similarly wide, which signals a level the market could move towards if growth or sentiment cools.
Explore the SWS fair ratio for Innovent Biologics.
Result: Preferred multiple of Price-to-Earnings of 117.7x (OVERVALUED)
Still, any setback in key drug trials or delays in wider approvals for Innovent Biologics products could hit sentiment and put that rich P/E under pressure.
Find out about the key risks to this Innovent Biologics narrative.
Another view on Innovent Biologics: DCF points the other way
The high P/E paints Innovent Biologics as expensive, yet the SWS DCF model tells a different story. At HK$97.5, the shares sit 35.2% below an estimated fair value of HK$150.42 based on future cash flows. That indicates investors might be paying less today relative to the company’s projected earnings power.
DCF analysis relies on long range assumptions about growth, profitability and discount rates. The rich P/E reflects nearer term sentiment and earnings multiples. When one framework indicates “expensive” and another suggests a discount, investors may need to consider which signal should carry more weight in their process.
Look into how the SWS DCF model arrives at its fair value.
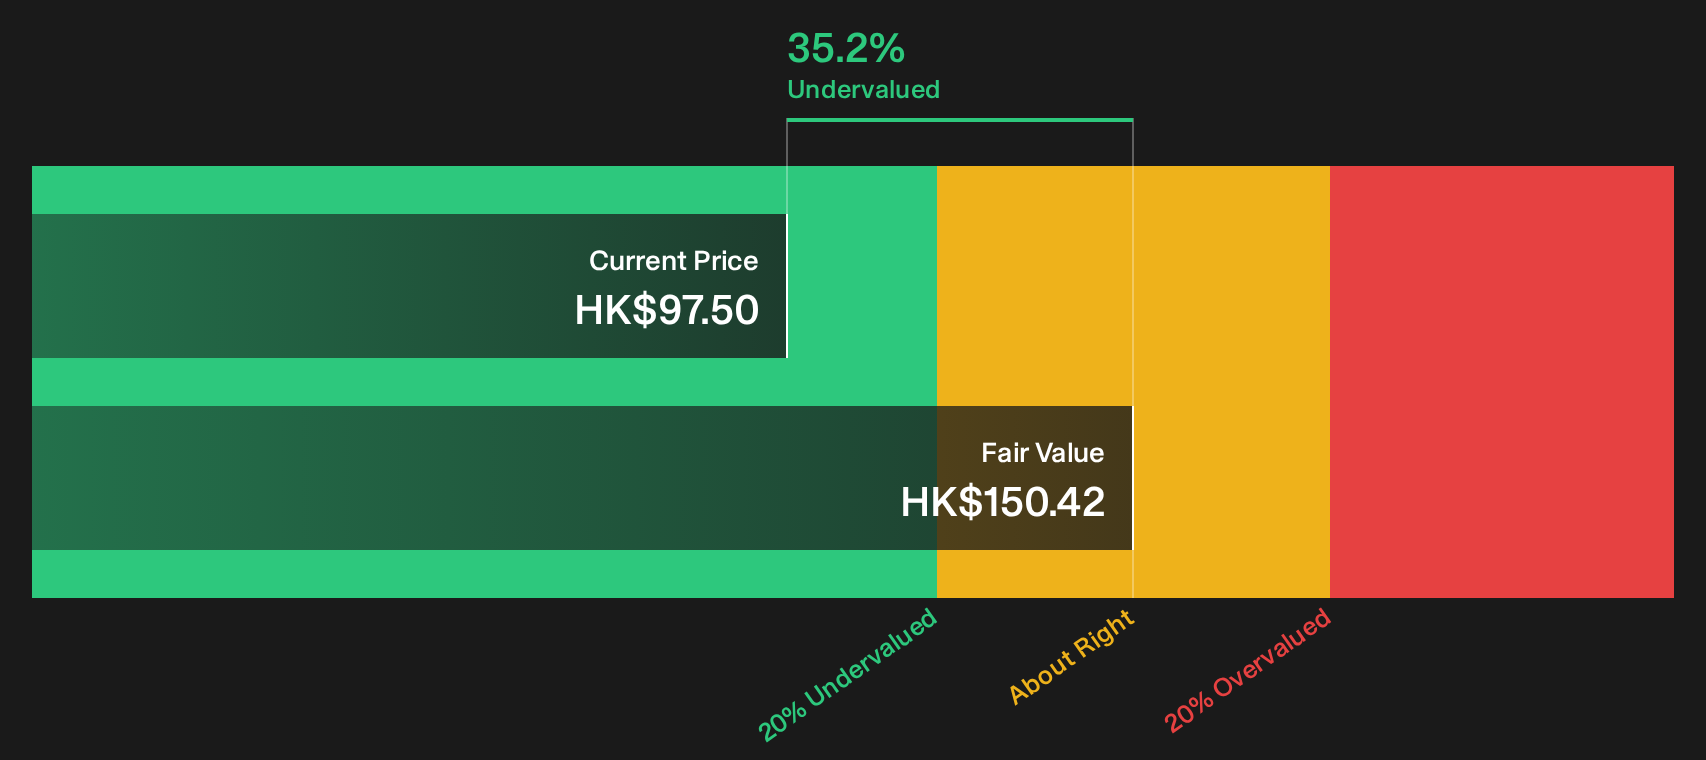
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Innovent Biologics for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 181 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty in this Innovent Biologics story leans optimistic, so do not wait for consensus to harden before you check the details yourself and test your own thesis. To see what the optimism is anchored to, review the 4 key rewards
Looking for more investment ideas beyond Innovent Biologics?
Do not stop your research with a single stock when a broader watchlist can sharpen your judgment and highlight better risk and reward trade offs.
- Target higher quality value opportunities by scanning a curated list of 181 high quality undervalued stocks before they attract wider attention.
- Protect your downside first and let the upside surprise you by reviewing 228 resilient stocks with low risk scores built around resilient balance sheets and steadier volatility.
- Hunt for future market leaders early by checking 614 high quality undiscovered gems with strong fundamentals that many investors have not studied yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com