
National Australia Bank (ASX:NAB) Wins An Analyst Upgrade, Is Fair Value Already Priced In?
National Australia Bank (ASX:NAB) just caught a fresh analyst upgrade, triggered by higher earnings estimates that signal growing confidence in the bank’s underlying operations and its profit outlook.
On the market, National Australia Bank’s share price has retreated, with the year to date share price return down 9.43% as shorter term moves have also softened. However, the 3 year total shareholder return of 50.86% and 5 year total shareholder return of 71.45% point to a much stronger longer run story that this latest upgrade now feeds into.
Scan how analysts’ upgrades are reshaping the big end of town by comparing National Australia Bank with 5 high quality undervalued stocks in similar positions.
Short term weakness has pulled National Australia Bank back just as upgraded earnings forecasts narrow the gap to analyst targets. Is the fair value story now closer to today’s A$38.40 price or to those higher estimates?
Most Popular Narrative: Fairly Valued
National Australia Bank is priced at A$38.40 against a most followed fair value estimate of about A$38.38, so the upgrade is landing on a stock that analysts already see as broadly in line with their long run numbers.
Ongoing digital transformation, focus on cost management, and productivity initiatives (including Citi integration, streamlined processes, and leveraging AI tools) are expected to structurally reduce the cost-to-income ratio over time, potentially boosting net margins and profitability. Expansion into transaction services and payments, combined with continued share gains in deposits and home lending, sets the stage for additional, diversified fee-based revenue streams and greater earnings stability, especially as deposit funding becomes a more significant driver of margins.
See why 79 investors see National Australia Bank as 0% overvalued.
Result: Fair Value of A$38.38 (ABOUT RIGHT)
Still, the story can change quickly if fintech rivals chip away at National Australia Bank’s fee pools or if SME loan quality weakens and pushes credit costs higher.
Find out about the key risks to this National Australia Bank narrative.
Another View on National Australia Bank’s Value
The DCF work suggests National Australia Bank is trading at a discount, with the A$38.40 share price sitting below an estimated future cash flow value of A$40.66. That points to a modest gap. The real question is whether those cash assumptions hold up if conditions turn tougher.
Look into how the SWS DCF model arrives at its fair value.
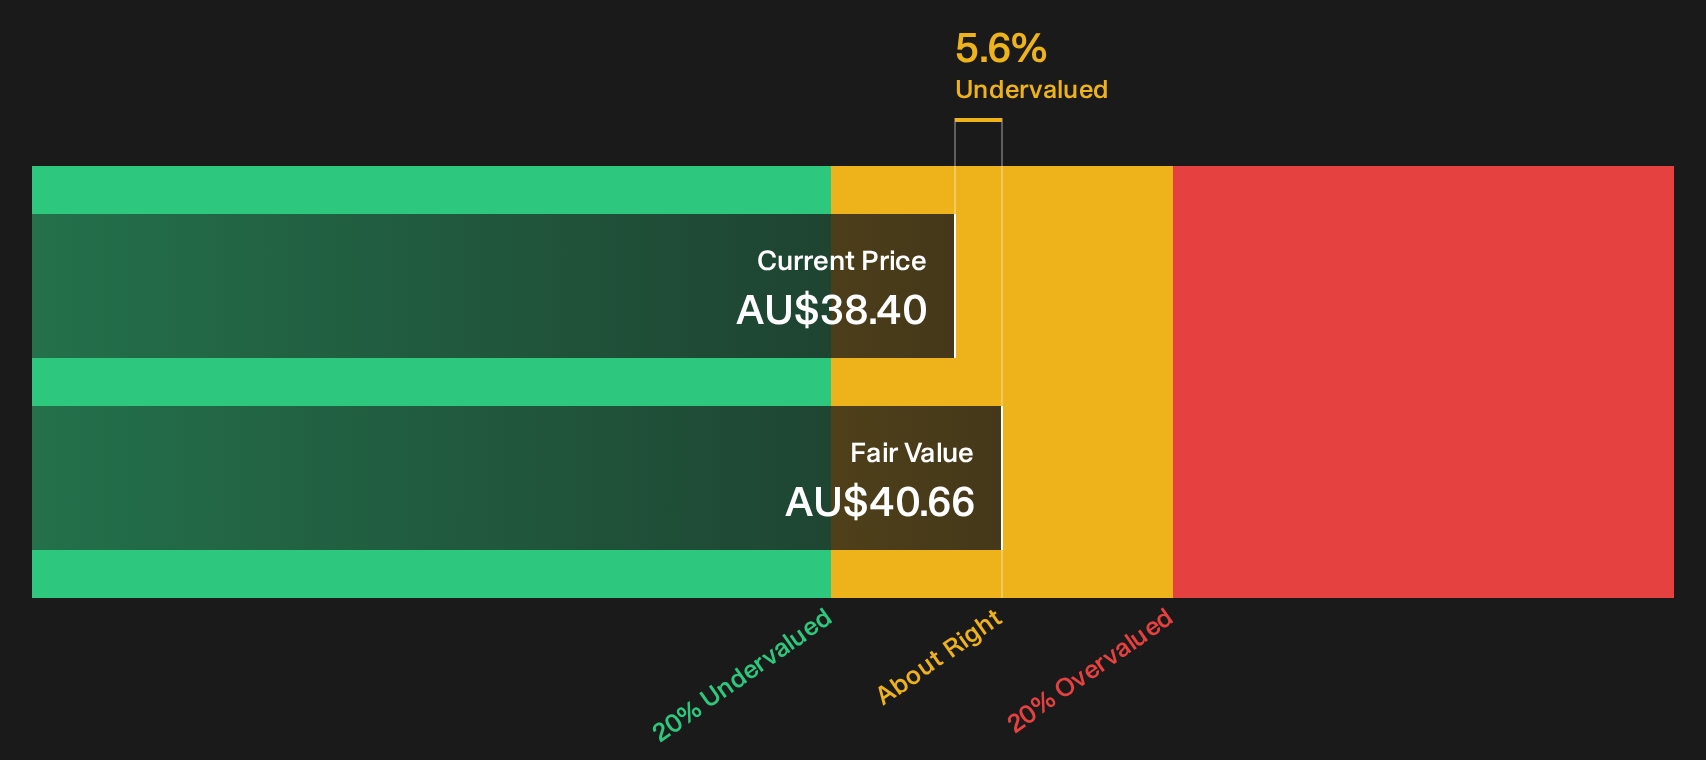
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out National Australia Bank for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on National Australia Bank's value story can be useful if you move quickly and compare the narrative with your own expectations. To assess whether the potential upside justifies the concerns, start by checking the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond National Australia Bank?
If National Australia Bank has sharpened your focus on value and risk, you may want to widen your watchlist and pressure test your thinking against fresh ideas from the Simply Wall St Screener.
- Target resilient compounding by scanning a 3 dividend fortresses that focuses on income strength as well as balance sheet support.
- Hunt for mispriced opportunities by reviewing a focused 15 high quality undiscovered gems that pairs quality fundamentals with quieter market attention.
- Reduce portfolio stress by filtering for a 7 resilient stocks with low risk scores that screens for dependable financial profiles and fewer red flags.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com