
Turning Point Brands (TPB) Faces A Fresh Test As Nicotine Pouch Growth Meets Valuation Debate
Turning Point Brands (TPB) has drawn fresh attention after a prolonged slide, with the share price down about 22% over the past month and roughly 34% over the past 3 months.
For context, Turning Point Brands has seen its share price weaken over short timeframes, with a 7-day share price return of down 3.01% and a year-to-date share price return of down 47.14%. However, longer horizons tell a different story, with the 3-year total shareholder return up 159.96% and the 5-year total shareholder return up 25.94% from reinvested dividends and price moves combined.
Scan how Turning Point Brands compares with other under-pressure opportunities by checking the curated list of 27 high quality undervalued stocks that combine quality fundamentals with weaker recent share price performance.
Turning Point Brands has been hit hard in a short span, yet it still carries a track record of longer term shareholder gains along with double digit recent revenue and net income growth. Does that mix still tilt the risk reward toward buyers when you line it up against the current valuation?
Most Popular Narrative: 58% Undervalued
On the most followed view, Turning Point Brands screens as materially cheap, with a narrative fair value of $140 against a last close of $58.27. That gap is being tied directly to how Modern Oral and nicotine pouches reshape the business mix over time.
The planned 70% increase in chain store count for nicotine pouches by the end of 2026, combined with ongoing efforts to deepen share of shelf and expand SKU assortments, gives Turning Point Brands room to shift a larger portion of Modern Oral sales into higher volume bricks and mortar channels. This can support future revenue growth and help spread fixed SG&A over a broader base.
See why 0 investors see Turning Point Brands as 58% undervalued.
Result: Fair Value of $140 (UNDERVALUED)
Still, the bullish Turning Point Brands story leans heavily on smoother pouch margins and onshoring going to plan, with any cost or regulatory setback quickly challenging that optimism.
Find out about the key risks to this Turning Point Brands narrative.
Another Take on Turning Point Brands Valuation
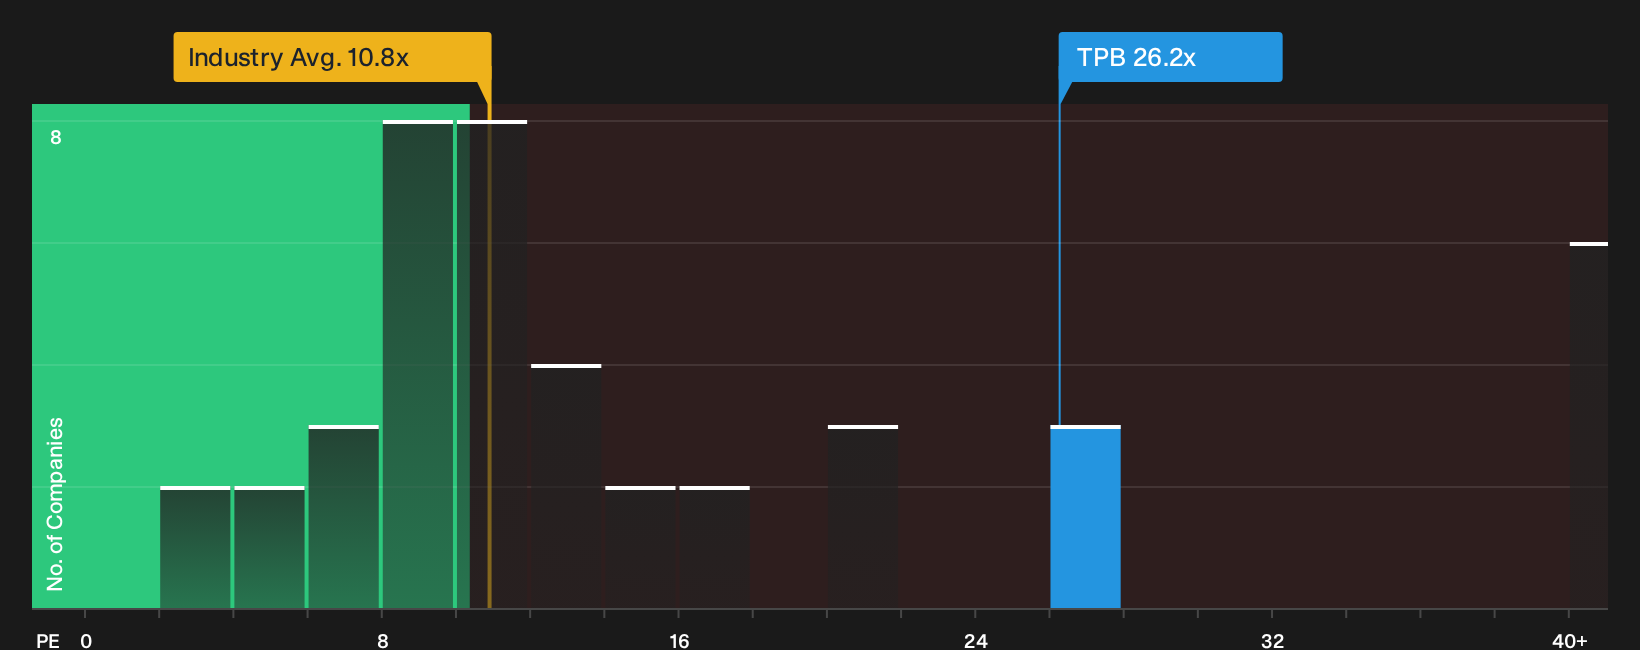
The bullish narrative pegs Turning Point Brands at a fair value of $140, yet the simple earnings multiple paints a tighter picture. TPB trades on a P/E of 26.2x compared with 10.8x for the global tobacco group, a much richer tag that relies on stronger growth expectations and leaves less room for disappointment.
Analysts note some cushion because TPB’s current P/E sits below an estimated fair ratio of 34.4x and under a peer average of 34.1x. This suggests potential upside if the market eventually prices the stock in line with faster growing comparables. The question is whether investors are being compensated sufficiently for backing the higher multiple story.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Turning Point Brands valuation and risk can feel messy, so move quickly, review the same numbers, and weigh both the downside and upside using the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Turning Point Brands?
If Turning Point Brands has you thinking more carefully about risk and reward, you do not need to stop here. Broaden your watchlist with targeted ideas that match your style and time horizon.
- Target resilient returns by reviewing a 31 resilient stocks with low risk scores that focuses on businesses with steadier profiles and lower overall risk scores.
- Hunt for potential future leaders early by scanning a 19 high quality undiscovered gems built around companies with strong fundamentals that are still off most investors' radar.
- Prioritise balance sheet strength by working through a list of solid balance sheet and fundamentals (25 results) so you are not the one chasing quality after the crowd has already moved.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com