
Snowflake (SNOW) Stock Could Be Pricey Despite Fresh AI Partnership News
Snowflake has delivered a 105.9% share price gain over the past three years, which puts its AI data platform firmly on investor screens. With the stock last closing at US$335.95 after a strong year to date, the open question is whether that price is supported by the sales the company is generating today and those investors expect it to deliver.
- A 105.9% return over three years means anyone buying Snowflake now is effectively paying up for a business the market already values far more highly than it did in 2023. As a result, the link between its current sales base and that higher valuation really matters.
- Fresh partnerships and marketplace integrations, from UiPath to CrowdStrike and LSEG, can support expectations for higher data consumption and platform usage. This feeds directly into how much revenue investors may think is reasonable to attach to each Snowflake share.
- Your read on Snowflake is one view; the desks covering it have another. See what analysts think Snowflake's shares could be worth.
The issue now is whether Snowflake's current share price can be justified by its sales given this mix of strong past returns and high expectations around its data and AI ecosystem.
Snowflake is not the only AI data story on the market. If you want a broader watchlist built on similar themes, consider a focused stock screen of 91 AI infrastructure stocks.
Has Snowflake Run Too Far on Sales?
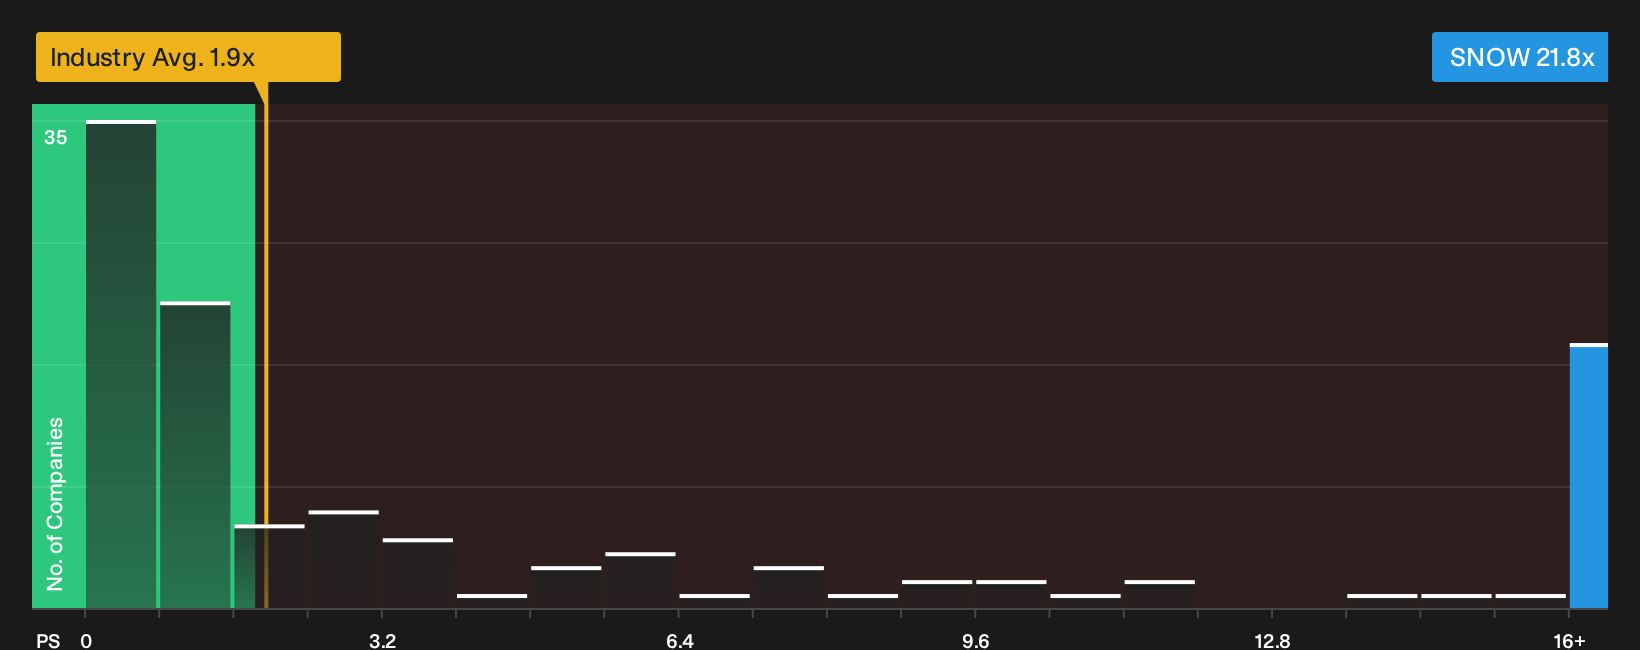
P/S is a useful lens for Snowflake because the business is still valued more on its revenue engine than on current accounting earnings. On this metric, the stock trades on a P/S of 21.8x, only a touch above the 21.6x peer average but far above the wider IT industry on 1.9x. That suggests investors are placing Snowflake in a tight cluster of high priced software and AI infrastructure stocks rather than judging it against the broader sector.
The fair multiple that reflects Snowflake's own growth profile, margins, scale and risk comes out lower than where the shares trade today, so the current 21.8x appears overvalued on this framework. Because the recent CrowdStrike, UiPath and LSEG tie ups highlight Snowflake's AI data cloud, enthusiasm around these partnerships is likely one reason the valuation premium has stayed in place on this P/S yardstick. Explore the numbers behind Snowflake's P/S valuation.
The Snowflake Narrative: What Would Justify Today's Price?
Snowflake's Simply Wall St Narratives pick up where this valuation question leaves off by spelling out what kind of future growth, margins and earnings would need to show up in order for the shares to look materially richer or cheaper than today. Each narrative treats Snowflake's fair value as a hypothesis about how the business might develop over time, so you can watch that story play out on the Community page rather than treating it as a one day snapshot.
Snowflake’s community views split around how durable AI driven consumption really is and how much risk the premium valuation carries.
Bull case: 21% undervalued
"Rapid product innovation, including the launch of approximately 250 new features and expanded offerings such as Snowflake Intelligence, Cortex AI SQL, and Postgres support, is increasing average revenue per user and deepening customer stickiness..."
Discover why this Narrative puts Snowflake at 21% undervalued.
Bear case: 326% overvalued
"The competitive pressure from Databricks is real, and the AI market remains in its early stages..."
Explore why this Narrative puts Snowflake at 326% overvalued.
Before you act on Snowflake's valuation, there is one more piece to check
Numbers only tell part of the story. The people steering Snowflake and the way their pay is structured can heavily influence how risk, growth bets and capital allocation play out over time. See who runs Snowflake and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com