
Home Depot (HD) Reaffirmed Its Outlook, Is The Stock Trading At A Discount?
Why Home Depot Is Back On Investors’ Radar
Home Depot (HD) is drawing fresh attention after management reaffirmed its fiscal 2026 outlook, even as higher interest rates pressure consumer spending and the wider Consumer Discretionary sector.
Recent trading has been choppy for Home Depot. The share price closed at US$286.69 after a 1-day share price return of 1.97%, yet it is still down 10.7% over 30 days and 17.1% year to date as higher rates weigh on Consumer Discretionary names and investors wait for the next earnings update.
Over a longer horizon, the total shareholder return is down 23.78% over the past year but modestly positive at 3.48% across three years. This suggests that shorter term momentum has faded, even though the multi year experience has not been uniformly weak.
Spot opportunities that share some of Home Depot’s defensive traits by scanning our hand picked 31 resilient stocks with low risk scores, which aims to balance resilience with equity market upside.Bulls see Home Depot’s reaffirmed 2026 outlook and repair focused demand as a cushion, while bears point to rate driven housing pressure and recent share price weakness. Which side do the current valuation markers support?
Most Popular Narrative: 26% Undervalued
According to andrei9868, the prevailing Home Depot narrative pegs fair value at $385, which sits well above the last close at $286.69. The story hinges on whether the Pro focused expansion can justify that gap.
Home Depot is evolving from a traditional big-box home improvement retailer into a comprehensive supplier ecosystem for professional contractors (“Pros”), while continuing to serve DIY customers through stores, digital tools, and faster fulfillment. Recent acquisitions (including SRS Distribution and GMS) expand its reach into specialty distribution for roofing, drywall, HVAC, and other complex project categories, enlarging the addressable market toward roughly $1.2 trillion and the Pro segment opportunity near $700 billion.
See why 6 investors see Home Depot as 26% undervalued.
Result: Fair Value of $385 (UNDERVALUED)
Still, the Home Depot story can crack if housing turnover stays weak for longer, or if recent acquisitions keep margins under pressure for years.
Find out about the key risks to this Home Depot narrative.
Another View On Home Depot’s Valuation
The community narrative pins Home Depot’s fair value at $385 and calls the stock undervalued. The SWS DCF model takes a different line. At $286.69, HD is trading above an estimated future cash flow value of $273.58, which points to modest overvaluation instead.
Both views use reasonable inputs yet land on opposite sides of fair value, which leaves investors with a simple question: Which set of assumptions about Home Depot’s future cash generation feels more realistic to you?
Look into how the SWS DCF model arrives at its fair value.
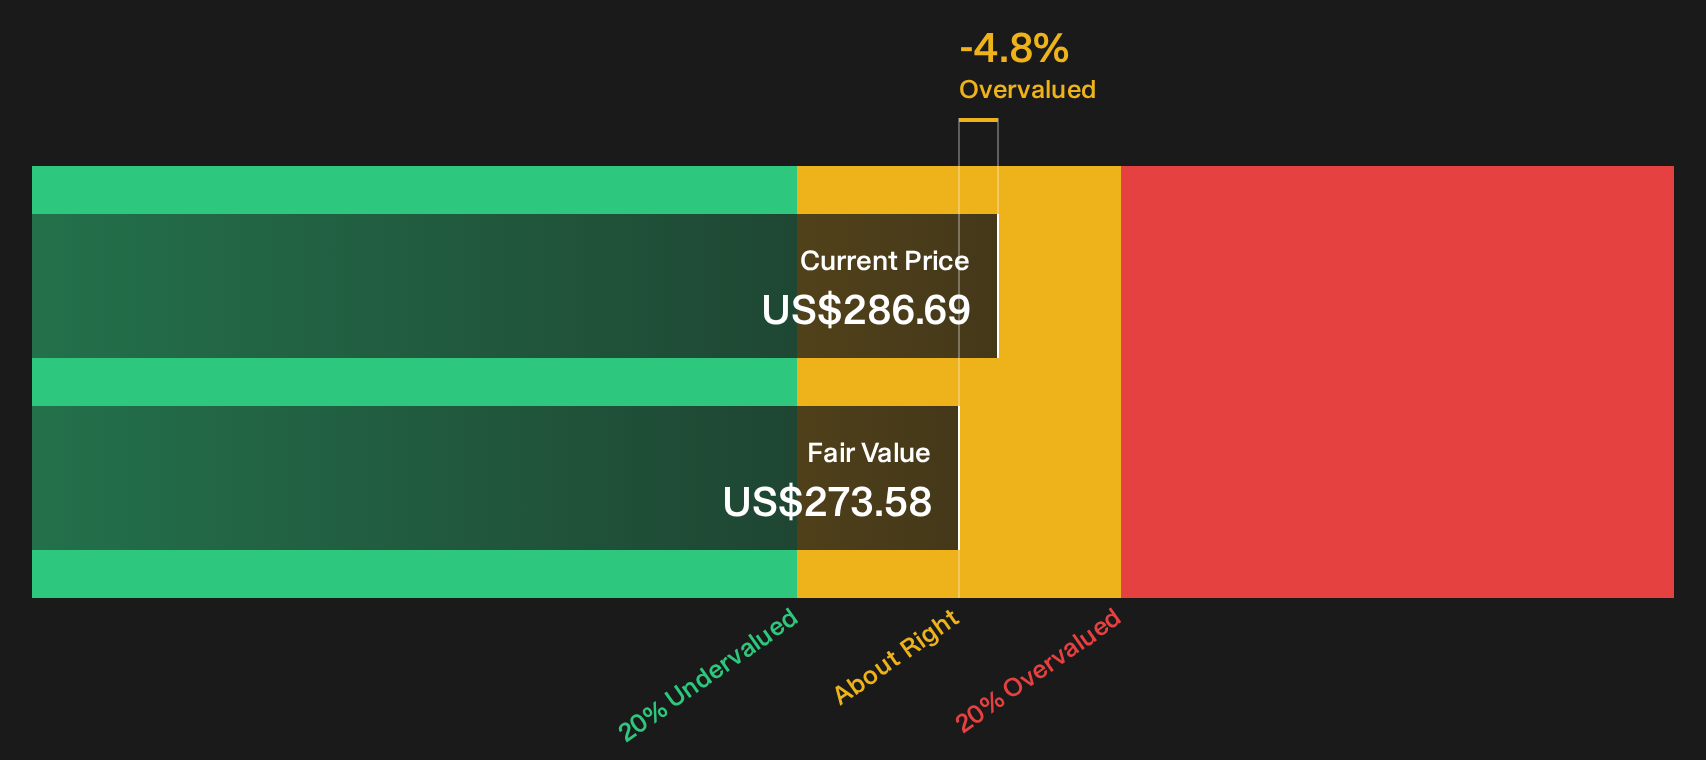
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Home Depot for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed on Home Depot after all this. If you want to move quickly and form your own take, start by weighing the 3 key rewards and 2 important warning signs.
Looking for more Home Depot style investment ideas?
If Home Depot has you thinking bigger about your portfolio, you can broaden your opportunity set by scanning a few focused stock lists built from clear, financial evidence.
- Target durable value by reviewing the 27 high quality undervalued stocks that combine solid fundamentals with prices that may not fully reflect those qualities.
- Strengthen your downside protection by checking the list of solid balance sheet and fundamentals (25 results) to see which companies pair healthier finances with room for long term compounding.
- Get ahead of the crowd by scanning the 19 high quality undiscovered gems before wider attention potentially closes the valuation gap.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com