
Did FDA Approval Just Shift Edwards Lifesciences (EW) Investment Narrative?
- Edwards Lifesciences reported that the FDA has approved the AUTUS Size-Adjustable Valve, a pediatric-focused surgical pulmonary valve that can be expanded as children grow using a minimally invasive transcatheter procedure.
- The AUTUS valve targets a specific congenital heart disease segment where repeat open-heart surgeries are common. This development may reshape Edwards Lifesciences' role in pediatric structural heart interventions and influence resource allocation within its broader valve portfolio.
- We will now explore how Edwards Lifesciences' pediatric focused AUTUS valve approval could reshape the existing investment narrative around structural heart.
Spot opportunities shaped by the same long-term healthcare forces behind Edwards Lifesciences' AUTUS valve approval by scanning our curated list of list of solid balance sheet and fundamentals (25 results).
Edwards Lifesciences Investment Narrative Recap
To own Edwards Lifesciences, you need to believe the multi platform structural heart plan can translate clinical data into steady procedure volume, while management steadily lifts operating margins despite mixed recent profit trends. The AUTUS approval fits that story at the margin, but the near term needle movers still sit in TAVR and transcatheter mitral tricuspid therapy execution.
The key short term swing factor remains whether Edwards Lifesciences can turn forecast revenue and earnings growth into cleaner profitability after recent one off items and softer margins. The biggest risk is that legal, trade or governance issues, including tariff exposure and the JenaValve injunction, drag on costs and distract from operating focus.
The AUTUS valve win lines up with a broader push into transcatheter based care, which links directly to the longer term TMTT revenue ambition of at least US$2b by 2030. That path already leans on projected 2026 TMTT sales of US$760 million to US$780 million, so execution in adjacent valve categories matters for investor confidence.
Expanded Medicare coverage for TAVR and the expectation for 100 to 200 new TAVR programs give Edwards Lifesciences more room to place valves and related tools if it delivers on clinical and commercial execution. The AUTUS approval adds another proof point in structural heart, while the core catalysts still relate to turning that broader opportunity into durable margins.
Edwards Lifesciences' narrative projects US$8.5b revenue and US$2.2b earnings by 2029, based on analyst models that assume 9.3% yearly revenue growth and an earnings increase of about US$1.2b from US$979.9m today.
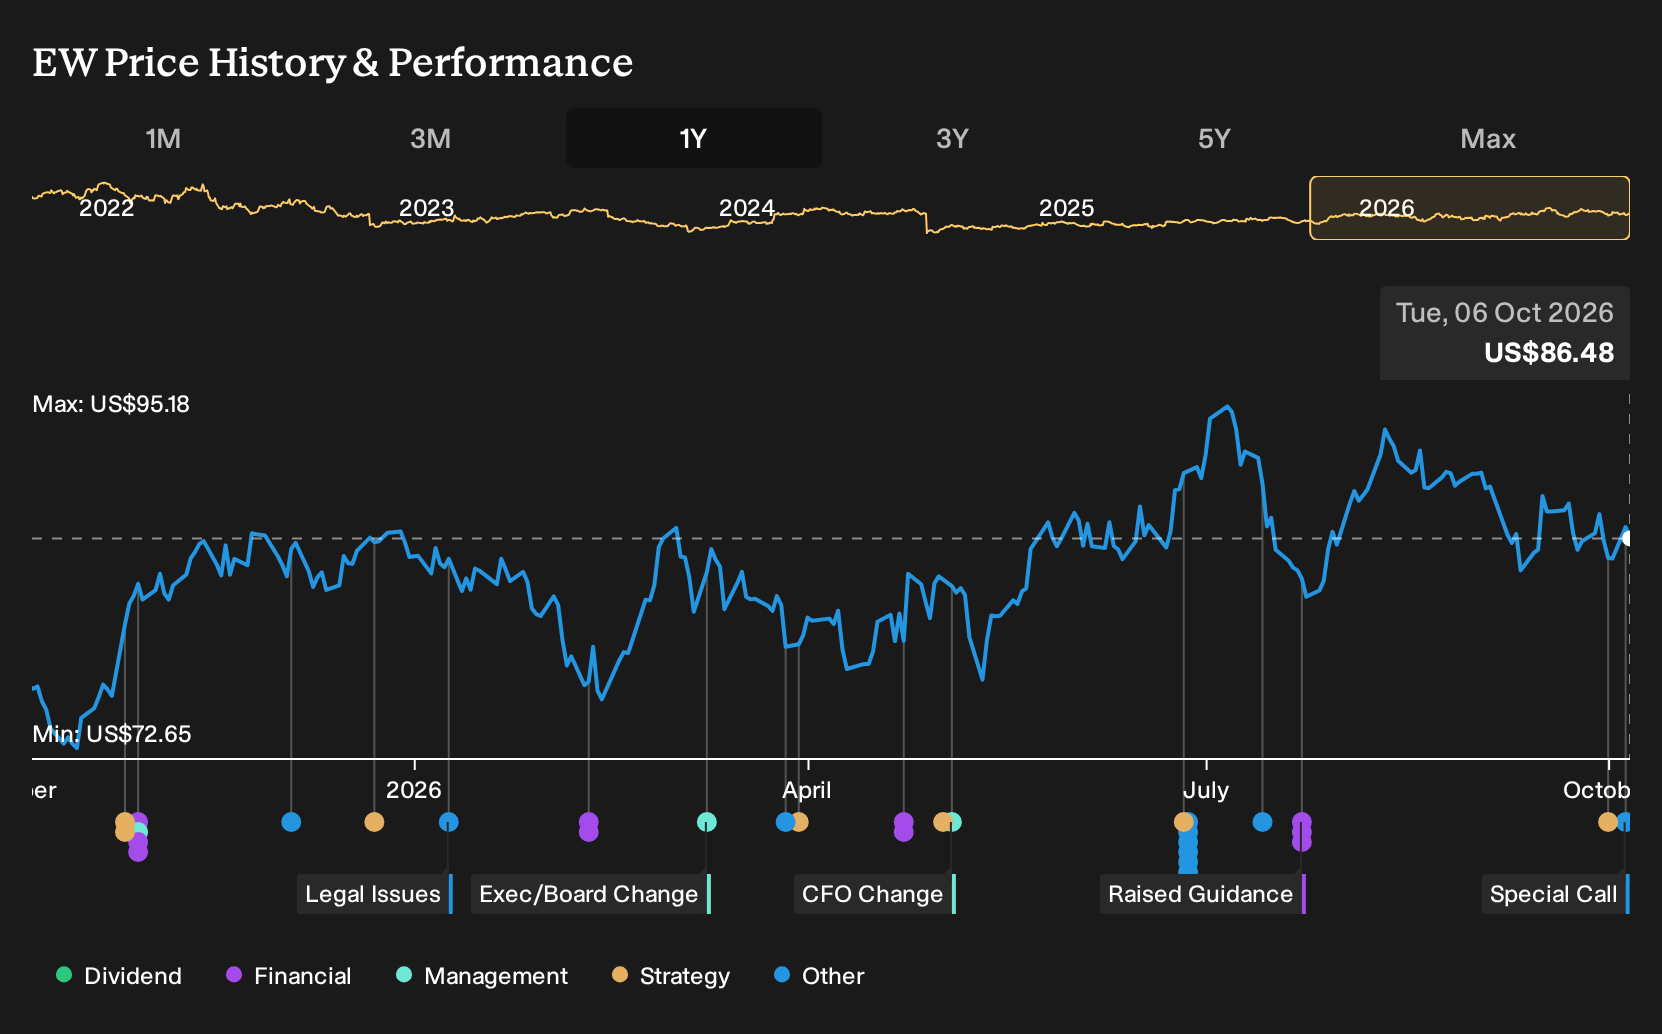
Discover why Edwards Lifesciences' fair value suggests a 17% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community offers two fair value views on Edwards Lifesciences, clustered tightly between 90.50 and 100.96, which still span a meaningful range at the extremes. Those estimates do not factor in the AUTUS approval or ongoing tariff, legal and governance questions, so you are seeing only part of the picture. To round out your own view, weigh these community projections against the TAVR and TMTT catalysts, as well as the potential impact of trade and regulatory costs on future profitability. Then explore several alternative opinions before deciding how Edwards Lifesciences fits into your portfolio.
Explore another Edwards Lifesciences fair value estimate, including one that suggests as much as 17% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Edwards Lifesciences research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Edwards Lifesciences. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Edwards Lifesciences' overall financial health at a glance.
Looking For More Investment Ideas Beyond Edwards Lifesciences?
Once the Edwards Lifesciences story is on your watchlist, it can help to compare it with other businesses that fit very different profiles. The Simply Wall St Screener lets you scan for shares that match the kind of balance sheets, income streams, or re rating potential you want to focus on next.
- If capital preservation ranks high for you, start with a group of companies that score well on resilience and risk with the 31 resilient stocks with low risk scores.
- For investors hunting for quality at a reduced price, look through a curated set of seemingly mispriced opportunities using the 27 high quality undervalued stocks.
- If you want more than just Edwards Lifesciences on your radar, widen the net with a hand picked pool of under followed businesses through the 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com