
Broadridge Financial Solutions (BR) Signs Korea Proxy Voting Deal, Is The Premium Still Justified?
Broadridge Financial Solutions (BR) just signed a memorandum of understanding with Korea Securities Depository to help digitize and automate Korea’s proxy voting system for international investors in Korean equities.
For context, Broadridge Financial Solutions shares trade at US$158.66, with the 30-day share price return down 8.23% and the year-to-date share price return down 28.04%. The 90-day share price return is up 7.88%, suggesting some momentum has started to rebuild. Over a longer stretch, total shareholder return has fallen 31.50% over 1 year and is modestly positive at 1.74% over 5 years. Investors may see the Korea Securities Depository agreement and recent leadership changes as part of a broader attempt to refresh growth drivers and reassess risk.
Scan how Broadridge Financial Solutions compares with other market infrastructure and governance plays by reviewing the 31 resilient stocks with low risk scores that have been curated for more resilient exposure to this theme.
The recent rebound in Broadridge Financial Solutions looks caught between a business quietly signing real deals and a market still nursing doubts after a tough year. How much of today’s price really reflects the underlying engine, rather than mood swings around the ticker?
Most Popular Narrative: 27% Overvalued
Against the last close at $158.66, the most followed narrative pins Broadridge Financial Solutions at a fair value of $125. That gap sets up an argument that the market is still paying a premium for a very high quality toll booth business.
Broadridge does not get much attention, but it runs something close to a toll booth on the U.S. stock market. It processes proxy materials and shareholder votes for roughly 80% of all U.S. shares outstanding. If you have ever voted your shares or gotten a fund prospectus in the mail, it probably went through Broadridge's pipes.
See why 2 investors see Broadridge Financial Solutions as 27% overvalued.
Result: Fair Value of $125 (OVERVALUED)
Still, that toll booth narrative can crack if tokenized securities reduce proxy plumbing volumes, or if regulators revisit fee schedules and shrink Broadridge Financial Solutions’ economics.
Find out about the key risks to this Broadridge Financial Solutions narrative.
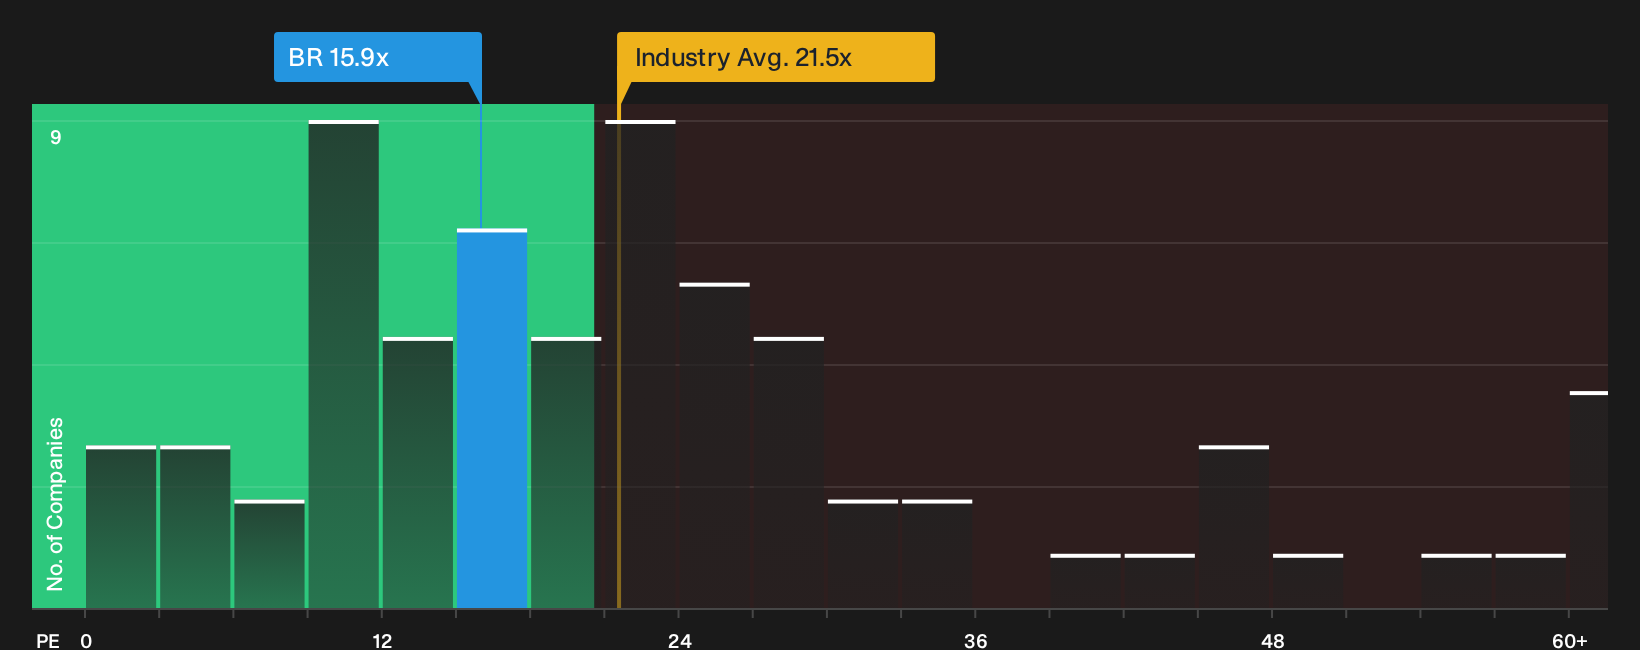
Another View: Broadridge Financial Solutions Through The P/E Lens
A different read on Broadridge Financial Solutions comes from its 15.9x P/E. That is cheaper than the US Professional Services sector on 21.5x and below its own fair ratio of 19.3x, yet slightly richer than peer averages at 15x. Is that gap a margin of safety or a value trap in disguise?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Broadridge Financial Solutions can either cause you to pause or encourage you to investigate the numbers yourself and act quickly while sentiment is still split. Consider both the caution and the optimism in the 5 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Broadridge Financial Solutions?
If the story around Broadridge Financial Solutions has you thinking harder about price, quality, and risk, use that momentum to sharpen your wider watchlist today.
- Target resilient balance sheets and cleaner fundamentals by scanning the list of solid balance sheet and fundamentals (25 results) to help keep financial stress firmly in the background.
- Hunt for quality at a discount by reviewing the 19 high quality undiscovered gems that many investors may not be watching yet.
- Focus on consistency and income potential by checking the 8 dividend fortresses that aim to pair higher yields with sturdier business profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com