
Is Toronto-Dominion Bank (TSX:TD) Fully Valued As Buybacks End And Bond Sales Expand?
Buybacks and bond issues shift the spotlight on Toronto-Dominion Bank
Toronto-Dominion Bank (TSX:TD) has been busy on both sides of its balance sheet. Investors just watched a major buyback tranche finish while a fresh wave of fixed income issuance comes to market.
Between September 1 and September 25, 2026, the bank repurchased 9,500,000 shares for CA$1,604.8 million. That portion represented 0.58% of its shares and completed a larger program announced earlier in the year.
Across the full plan, Toronto-Dominion Bank bought back 47,200,000 shares at a cost of CA$7,104.8 million. Those repurchases equated to 2.84% of its equity base, with the transaction formally closed on September 25, 2026.
Attention now shifts to a potential follow up. On September 30, 2026, the Board of Directors said it would review a new normal course issuer bid that could cover up to 61,000,000 shares, or 3.63% of its CA$10,000 million reference amount.
The plan is framed as a one year program and the repurchased stock would be cancelled. Execution depends on approvals from the Office of the Superintendent of Financial Institutions Canada and the Toronto Stock Exchange, so investors will be watching the regulatory calendar closely.
While equity is being retired, the bank has been active in the bond market. Recent days brought a series of fixed income offerings, which help shape how Toronto-Dominion Bank funds itself across different currencies, maturities, and investor bases.
On September 25, 2026, the institution announced 6.00% notes due October 16, 2031, priced at 100% with a 3.35% discount per security. These are callable, senior, unsecured EuroBonds and Eurodollar bonds, issued under a medium term note program.
Activity continued on September 28, 2026. The firm either announced or completed several non convertible corporate notes, all with fixed coupons and priced at 100%, but with different terms and structures.
- 5.00% notes due April 16, 2028, senior unsecured MTNs with a 1.7% discount per security.
- 5.5% notes due September 30, 2031, callable EuroBonds and Eurodollar bonds, junior, senior, unsecured MTNs, issued in a principal amount of US$1.454 million with a 1.522% discount.
- 5.60% notes due September 30, 2030, callable senior EuroBonds and Eurodollar bonds, in a principal amount of US$1.112 million with a 1.35% discount.
- 5.75% notes due September 30, 2031, callable senior unsecured EuroBonds and Eurodollar bonds, MTNs, with a US$1.147 million principal and a 0.842% discount.
- 5% notes due September 30, 2028, callable junior senior unsecured EuroBonds and Eurodollar bonds, MTNs, totaling US$4.68 million with a 0.737% discount.
- 5.85% notes due October 15, 2030, callable senior unsecured EuroBonds and Eurodollar bonds, MTNs, with a 2.35% discount.
- 5.35% notes due October 16, 2028, callable senior unsecured EuroBonds and Eurodollar bonds, MTNs, with a 1.7% discount.
This mix of buybacks and bond issuance provides a clearer view of how Toronto-Dominion Bank manages its capital structure. Equity is shrinking through repurchases, and fixed coupon debt, often callable, is used to fund operations and refinance existing obligations over time.
The latest flurry of buyback and bond headlines lands at a time when Toronto-Dominion Bank’s share price has climbed to CA$168.06, with a 29.46% year-to-date share price return and a 53.68% 1-year total shareholder return, indicating momentum that has built steadily over several years.
Spot 7 high quality undervalued stocks that, like Toronto-Dominion Bank, are actively reshaping their balance sheets through buybacks and bond issuance while the market reassesses their potential.Bulls point to Toronto-Dominion Bank’s aggressive buybacks, rising returns and value score of 1. Bears highlight the rich recent run. Which story do the current valuation markers support next?
Most Popular Narrative: 6% Undervalued
Toronto-Dominion Bank’s most followed valuation narrative puts fair value at CA$179.14, a touch above the last close at CA$168.06. This leaves the story focused on whether current strength already prices in the key moving parts.
Persistent investment in compliance (notably elevated AML remediation, cyber, and fraud prevention costs) is expected to drive higher structural expenses, weighing on net margins and overall earnings growth well into 2026 and 2027, as regulatory scrutiny and associated operational costs remain elevated.
See why 178 investors see Toronto-Dominion Bank as 6% undervalued.
Result: Fair Value of CA$179.14 (UNDERVALUED)
Still, heavy compliance spending and TD’s exposure to Canadian real estate leave room for credit surprises that could quickly reshape how investors interpret this valuation story.
Find out about the key risks to this Toronto-Dominion Bank narrative.
Another View on Toronto-Dominion Bank’s Valuation
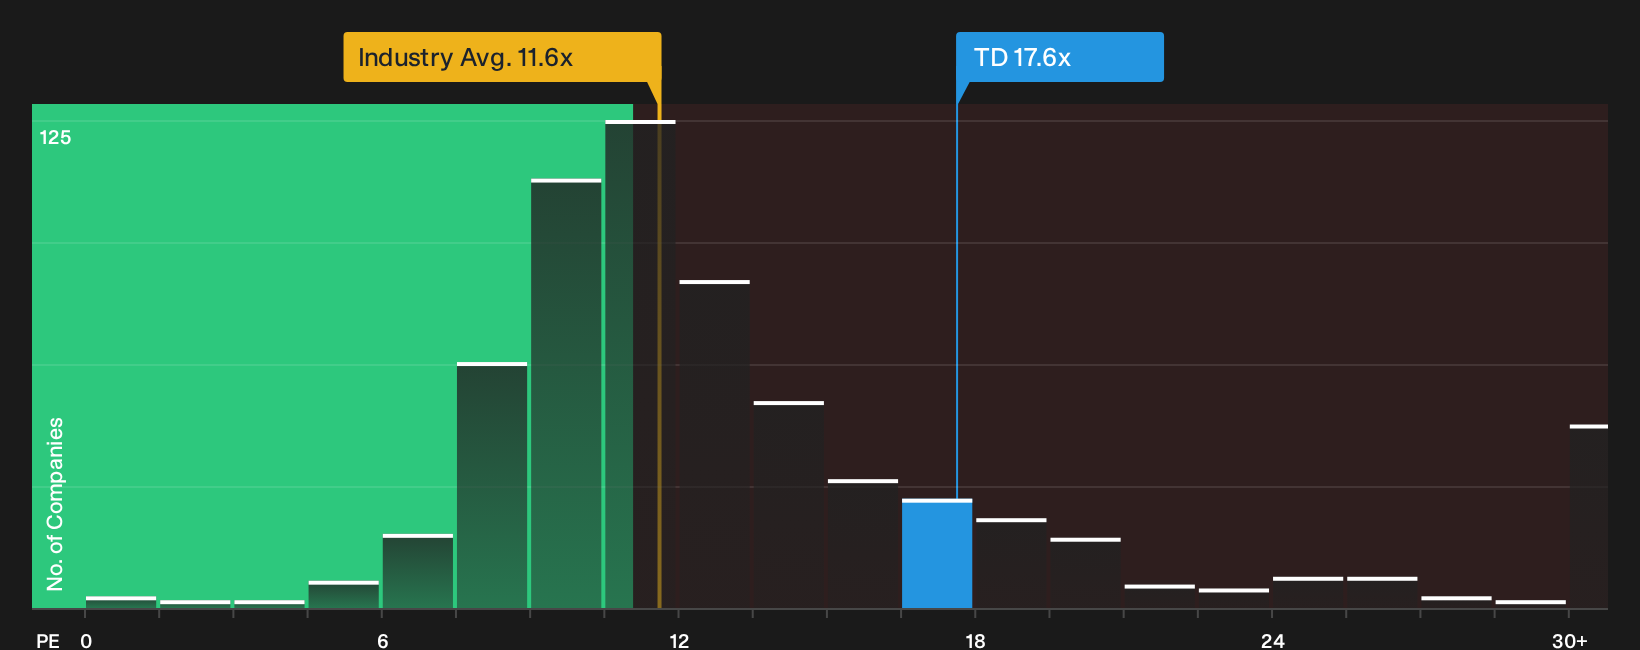
Analysts talk about Toronto-Dominion Bank as 6% undervalued based on their fair value of CA$179.14, yet the current P/E of 17.6x sits above the North American banks average of 11.6x and above its own fair ratio of 16.5x. That richer multiple suggests less margin for error if the story shifts.
For a closer look at what this richer P/E implies for risk versus opportunity, take a look at the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling pulled between the bullish and cautious takes on Toronto-Dominion Bank today? Act promptly, review the underlying metrics yourself, then weigh the 3 key rewards.
Looking for more ideas beyond Toronto-Dominion Bank?
If Toronto-Dominion Bank has you thinking about portfolio upgrades, use this momentum. Fresh ideas now can matter more than fine tuning existing positions.
- Spot potential bargains early by scanning the 8 high quality undiscovered gems before other investors start paying attention.
- Strengthen your core holdings by filtering for companies on the list of solid balance sheet and fundamentals (7 results) that can better handle shocks and funding needs.
- Build a cushion of potential cash flow by reviewing the 1 dividend fortresses that might help support more stable returns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com