
Is Novo Nordisk (CPSE:NOVO B) Still A Bargain On Earnings?
Novo Nordisk has been at the center of the global obesity and diabetes story, yet the share price has fallen hard in recent years, which puts fresh scrutiny on what investors are paying for its earnings today. With new data on its semaglutide franchise and fresh licensing deals reshaping expectations, the key issue for readers is whether the current valuation of Novo Nordisk stock still lines up with what the business earns.
- Over the past 3 years the share price has declined 58.8%, which raises the question of how much of the earlier optimism around Novo Nordisk's profits has already been priced out.
- Recent semaglutide trial results and licensing agreements in obesity and liver disease care can influence how investors think about the durability, mix, and timing of future earnings from Novo Nordisk's treatments.
- Your read on Novo Nordisk is one view; the desks covering it have another. See what analysts think Novo Nordisk's shares could be worth.
The issue now is whether Novo Nordisk's current share price is adequately supported by the earnings the company is generating today.
If you want to stress test this same earnings question beyond Novo Nordisk, line it up against a wider field of 183 high quality undervalued stocks.
Is Novo Nordisk Still Cheap on Earnings?
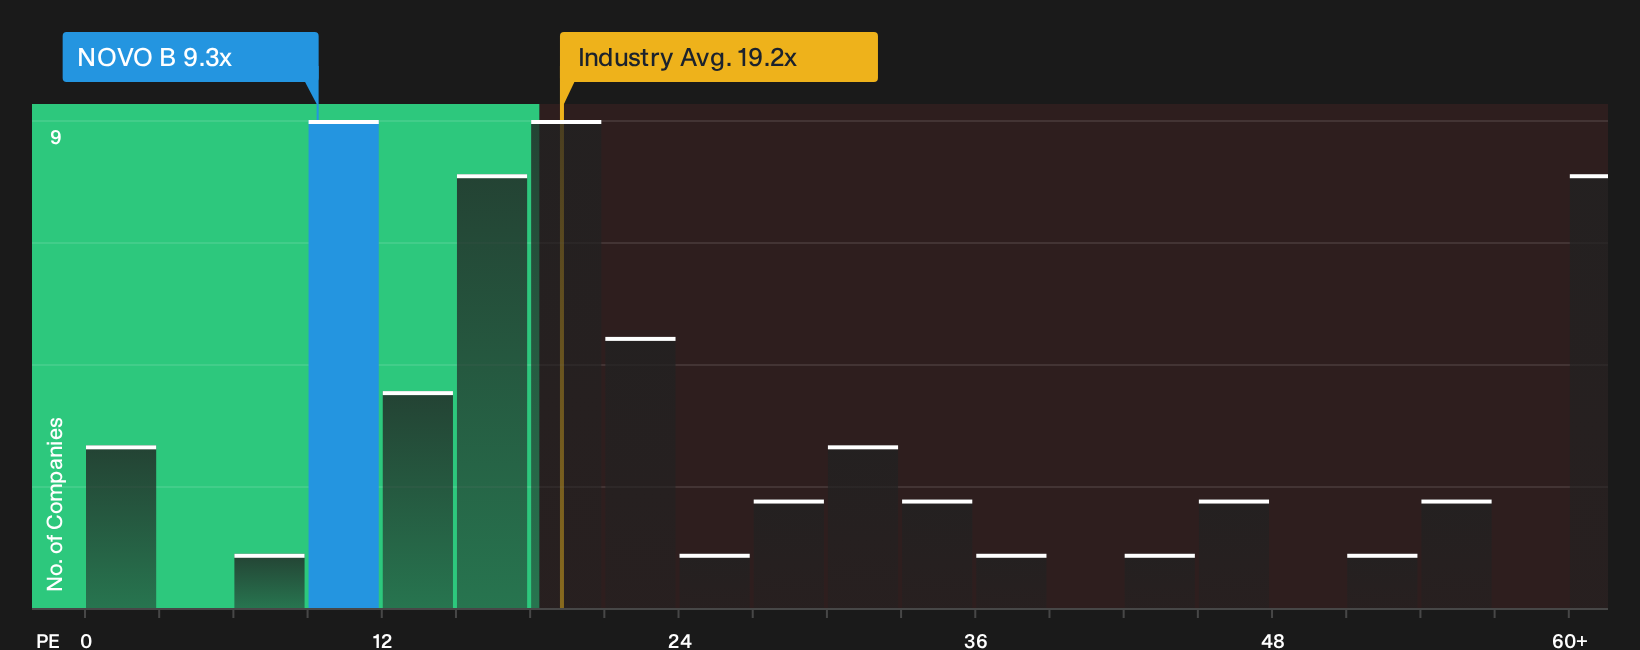
The P/E ratio suits Novo Nordisk because earnings remain the core yardstick most investors reach for when they price a large, profitable pharmaceutical group. On that measure, the stock trades on roughly 9.3x earnings, compared with about 21.7x for the wider pharmaceuticals industry and 26.2x for its peer group. That is a sizeable discount to both sector norms and to similar businesses that investors also view through an earnings lens.
Because the fair P/E that would typically line up with Novo Nordisk’s mix of growth drivers, profitability and risks appears higher than the current 9.3x, this framework views the shares as undervalued on earnings. Despite fresh data on semaglutide in obesity and liver disease broadening how the pipeline is perceived, the market is still pricing Novo Nordisk below where this earnings based model might usually place a large, established pharmaceutical stock. Explore the numbers behind Novo Nordisk's P/E valuation.
The Novo Nordisk Narrative: What Would Justify Today's Price?
Novo Nordisk Narratives on Simply Wall St sit between the current 9.3x P/E and your own expectations. They spell out which growth, margin and earnings paths would need to play out for the stock to be worth meaningfully more or less than today’s price on the Community page. Each Narrative ties its number to a specific view on where Novo Nordisk's growth, profitability and key risks might head next, which you can revisit as fresh information arrives.
Community views on Novo Nordisk split between a production platform that still has plenty to give and a pipeline that might not fully replace GLP 1 pressure.
Bull case: 71% undervalued
"With the unexpected success of its obesity drugs, the company has effectively gained a highly profitable new business segment almost for free..."
Discover why this Narrative puts Novo Nordisk at 71% undervalued.
Bear case: 21% overvalued
"Bearish analysts expect Novo Nordisk to face sustained revenue pressure as semaglutide moves into loss of exclusivity markets, with step-down price declines of up to about 50%..."
Explore why this Narrative puts Novo Nordisk at 21% overvalued.
One more Novo Nordisk check that belongs beside the P/E comparison
Price multiples tell you what investors pay for Novo Nordisk’s current earnings, while professional projections sketch where they think those profits might be heading over the next few years. Explore where analysts expect Novo Nordisk to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com