China Merchants Securities: US non-farm payrolls data for September were significantly lower than expected. Expectations for the Federal Reserve's interest rate hike in October are cooling down
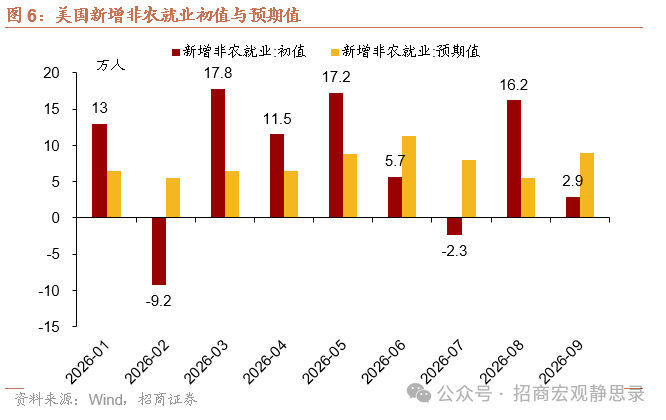
The Zhitong Finance App learned that China Merchants Securities released a research report saying that the US Bureau of Labor Statistics announced that in September 2026, the number of non-farm payrolls increased by 29,000. The expected value was 90,000, and the previous value was 133,000; the unemployment rate recorded 4.2%, the expected value was 4.1%, and the previous value was 4.1%. The data on new non-farm payrolls in September fell significantly short of expectations. The decline in new local government employment under a high base was a core factor. Furthermore, new employment in the leisure and hospitality industry once again declined markedly compared to the previous month, and the information industry, professional and commercial services, and financial services continued to be an absolute drag. Previously, the lower than expected PCE data for August had significantly reduced market concerns about inflation. After the release of the non-agricultural data, the market further lowered expectations for the FOMC rate hike in October. After the data was released, CME data showed that the market's expectation that the FOMC would keep the policy interest rate unchanged in October rose to 80%, but the maximum probability scenario was that the interest rate hike in December would be 25 BP.
I. Important overseas economic data
1. The year-on-year growth rate of the US PCE price index in August fell far short of expectations
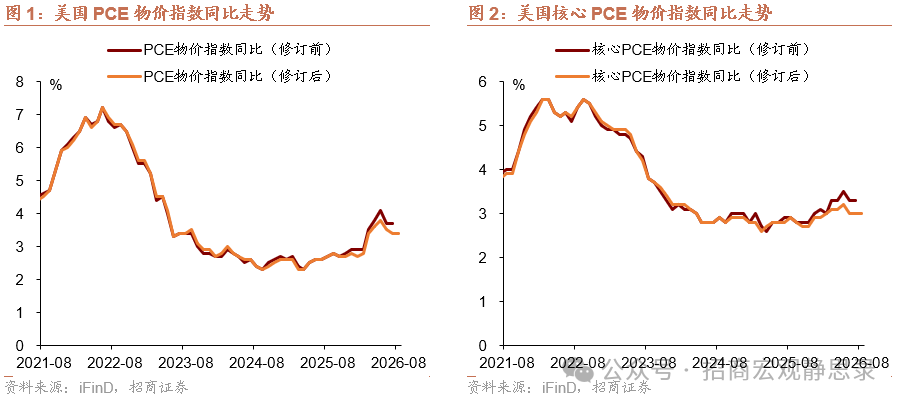
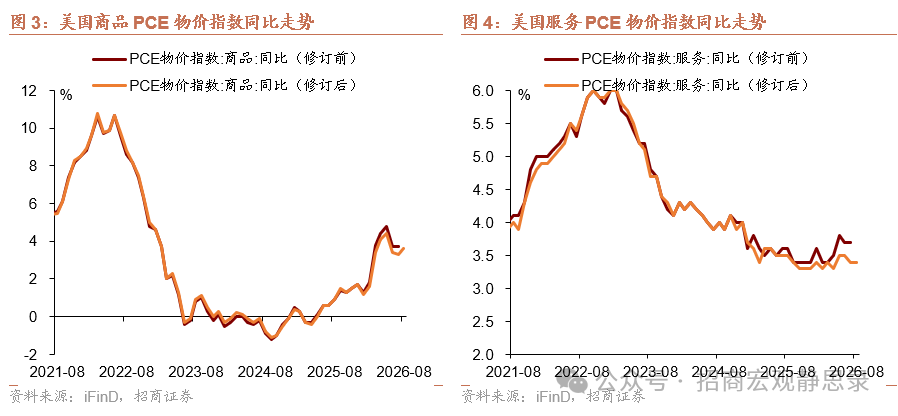
On September 30, 2026, the Bureau of Economic Analysis of the US Department of Commerce announced the personal consumption expenditure (PCE) price index for August. In August, the overall PCE price index rose 3.4% year on year, and the core PCE price index rose 3.0% year on year, lower than market expectations of 3.7% and 3.3%, respectively; up 0.3% and 0.2%, respectively. At the same time, BEA traced the annual revision back to 2021, but the comparison before and after the revision showed that the biggest change was the reading since 2026. After the correction, the overall PCE and core PCE year-on-year growth rates were significantly lower than before the revision.
The main reason for the fall short of expectations is the BEA's annual revisions to PCE data. The revisions are mainly reflected in the three sub-categories of financial services, legal services, computer software and accessories. 1) In terms of financial services, for portfolio management and investment advisory services, the old method used revenue data to calculate current price estimates and reduce the producer price index, but the two were inconsistent in reflecting changes in asset values and rate changes, leading to unverifiable fluctuations in the number of services estimated. The new method used employment and working hours data to directly extrapolate the number of services, and the price index was changed to an implicit derivation to reduce abnormal fluctuations. 2) In terms of legal services, the legal service CPI using the old method has not been publicly released for most of the time since 2023. Since then, the unpublished values used have not met the BLS publication quality guidelines and fluctuated abnormally. BEA therefore replaced the original CPI with a compound price index based on multiple producer price indices. 3) In terms of computer software and accessories, there is a mismatch between the composition of the old CPI and the actual scope of this consumer category in the national account: CPI includes hardware accessories such as flash drives and blank media, and these are not part of NIPA's software and accessory consumption categories; at the same time, projects such as game software publishing and application service provision services in the NIPA category are not covered by CPI. As a result, BEA switched to a composite price index and synthesized the CPI of computer software and accessories with producer price indices for game software publishing, hosting, and IT infrastructure services according to weight to better reflect the composition of this category.
This data correction has caused market interest rate hikes to cool down. As far as the Fed's subsequent decisions are concerned, this revision should have a marginal impact. The core PCE is an indicator that the Federal Reserve and Walsh are more concerned about. Relieving pressure on the data can also provide additional arguments for suspending interest rate hikes, but it is likely that it will not be a decisive factor in the path of subsequent interest rate hikes.
2. The US GDP growth rate increased sharply in the second quarter
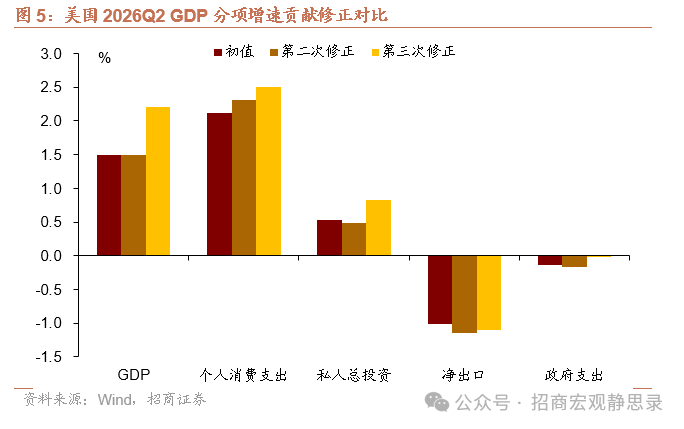
On September 30, 2026, the US Bureau of Economic Analysis announced the third estimate of real GDP for the second quarter of 2026. According to the data, real GDP grew at an annualized quarterly rate of 2.2% in the second quarter, an increase of 0.7 percentage points from the second estimate (both the initial value and the second estimate were 1.5%).
According to the BEA technical note, the upgrade mainly comes from consumer spending, private investment, and government expenditure. 1) Services and products are being upgraded simultaneously in consumer spending. The service side was driven by improvements in entertainment services and other services, partly offset by downgrades in transportation services, particularly air transport. The commercial side is driven by maintenance of recreational goods and vehicles, especially information processing equipment. 2) The increase in private investment is mainly reflected in the increase in private inventory investment and private fixed investment. In terms of inventory investment, non-agricultural inventory investment and agricultural product inventory investment have been upgraded. In terms of fixed investment, non-residential buildings and residential investments have been upgraded, particularly with regard to non-residential investment revisions relating to commercial and medical data centers. 3) The increase in government spending mainly targets federal defense spending, reducing the negative impact of government spending on GDP.
By incorporating more consumption, investment, and government spending factors, this revision more fully reflects the current resilience of the US economy. Against the backdrop of high inflation but monetary policy has yet to be tightened, consumer spending is still being revised up, indicating that consumer demand for services and goods has not weakened significantly. Investments in non-residential buildings, especially those related to data centers, have been upgraded, indicating that AI capital expenditure is becoming an important support for private investment. Consumer resilience and AI capital spending together boosted economic growth momentum in the second quarter, and mitigated market concerns about the risk of a short-term recession in the US economy.
The new non-farm payrolls data for March and September fell short of expectations
On October 2, 2026, the US Bureau of Labor Statistics (BLS) announced that in September 2026, the number of non-farm payrolls increased by 29,000, with an expected increase of 90,000; the previous value was an increase of 133,000; the unemployment rate recorded 4.2%, the expected value was 4.1%, and the previous value was 4.1%.
The data on new non-farm payrolls in September fell significantly short of expectations. The decline in new local government employment under a high base was a core factor. Furthermore, new employment in the leisure and hospitality industry once again declined markedly compared to the previous month, and the information industry, professional and commercial services, and financial services continued to be an absolute drag.
The September non-agricultural data can be seen as a phased correction to August's overly strong performance. The recovery in the labor participation rate drove the U3 unemployment rate to rise slightly, and the wage growth rate weakened, but the decline in the U6 unemployment rate indicates that the job market is still resilient. Local government, leisure, and hospitality segments continue to greatly disrupt the overall data, but excluding the interference caused by these two items, whether the continued upgrading of AI applications will further weaken employment in the service sector is an issue that needs to be focused on in the next phase.
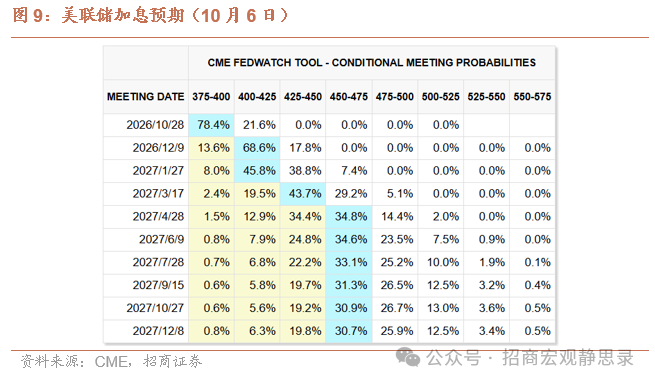
Previously, the lower than expected PCE data for August had significantly reduced market concerns about inflation. After the release of the non-agricultural data, the market further lowered expectations for the FOMC rate hike in October. After the data was released, CME data showed that the market's expectation that the FOMC would keep the policy interest rate unchanged in October rose to 80%, but the maximum probability scenario was that the interest rate hike in December would be 25 BP.
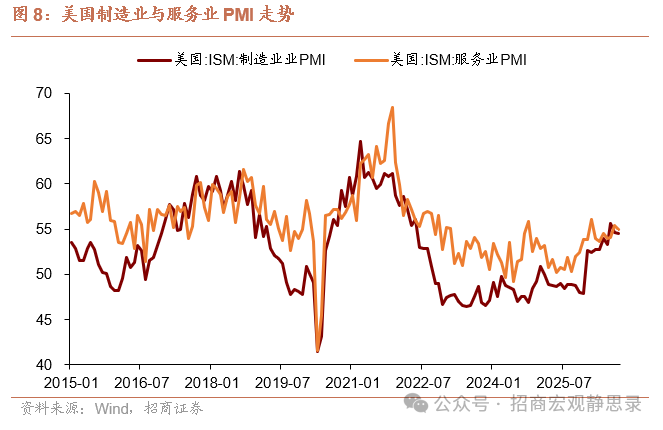
The US manufacturing PMI and service sector PMI were both significantly higher than the boom and bust line in April and September
In September 2026, the US manufacturing and service sector PMIs were in an expansion range, and continued to be significantly higher than the boom and bust line. The ISM manufacturing PMI recorded 54.5 in September. Although it is a slight decrease of 0.1 percentage points from August, it has been in the expansion range for nine consecutive months. The ISM service sector PMI recorded 54.9 in September, and has been in the expansion range for 27 consecutive months. Both PMIs are significantly above the boom and bust line, indicating that the US economy continues to expand in both manufacturing and service sectors.
In terms of price indices, both manufacturing and service industries have clearly rebounded. In September, the ISM manufacturing price index rose sharply from 71.1 in August to 77.9, up 6.8 percentage points, the highest level since June this year. It is also the 24th month in a row that raw material prices have risen. The ISM service industry price index rose from 72.6 to 74.0 in September, a new high since July 2022. As a leading indicator of CPI, the price index reflects changes in investment costs on the purchasing side of enterprises. Its continued rise indicates that inflationary pressure is building up again and may be further transmitted to the consumer side in the future.
In terms of the employment index, the manufacturing industry rose further, and the service sector improved marginally. The ISM manufacturing employment index rose to 52.7 in September from 51.2 in August, and has been in the expansion range for the third month in a row. The service sector employment index rose to 50.1 from 47.8 in August, returning to the expansion range for the first time since June. Judging from the new non-agricultural data added in September, there are clear signs of a recovery in new employment in the manufacturing industry. The reason behind this is the expansion of data center construction and the recovery in manufacturing production driven by AI capital expenditure. However, employment in the service sector is still clearly impacted by AI, and the major trend of employment contraction in the two major industries of technology and finance has not yet been reversed. There was also feedback from companies in the ISM survey, and personnel structure adjustments are being made due to efficiency improvements brought about by AI tools.
II. Dynamics of overseas central banks
1. Federal Reserve: Cold data and official changes in pigeons have temporarily cooled expectations of interest rate hikes
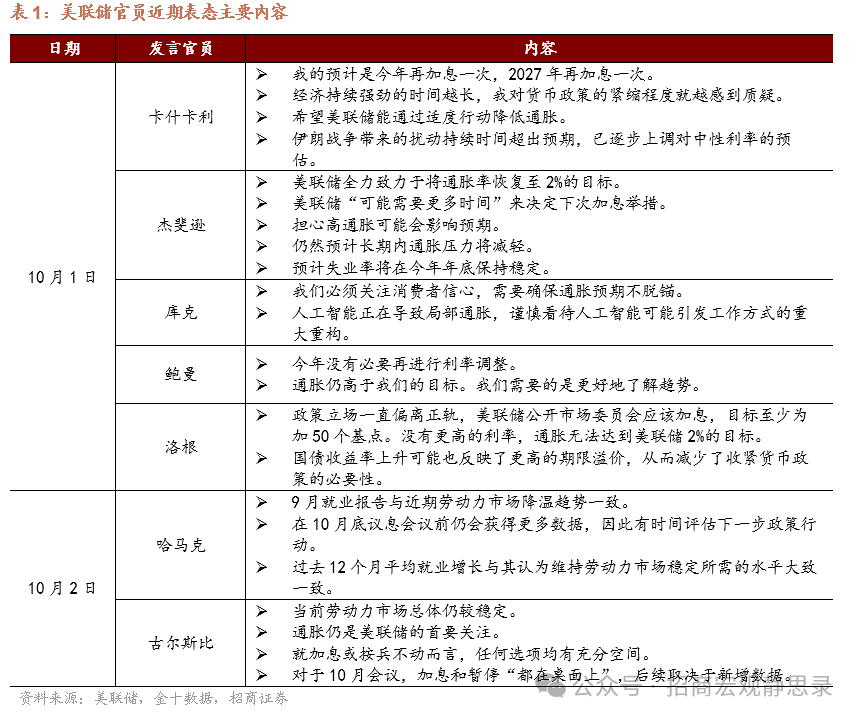
Non-agricultural data and statements from some officials have cooled expectations of interest rate hikes in October. The number of non-agricultural workers employed in September was 29,000, and the previous value was 133,000. At the same time, the July-August data was revised down to about 30,000; the unemployment rate recorded 4.2%, the forecast was 4.1%, and the previous value was 4.1%. After the data was released, combined with the August PCE data downgraded, the market expected the probability that the FOMC would suspend interest rate hikes in October to rise to 80%. Furthermore, on September 29, New York Federal Reserve Chairman Williams said that given the policy actions we took at the September meeting, there is no need to rush into action; we have time to gather more information. On October 1, Federal Reserve Vice Chairman Jefferson said that the Federal Reserve may need more time to decide on the next rate hike. On the same day, Bowman said there is no need to adjust interest rates again this year, and the rest of the officials also suggested that there will be no need to continue to raise interest rates in October. Therefore, the change in official positions caused the market to cool down the expectations of the October rate hike.
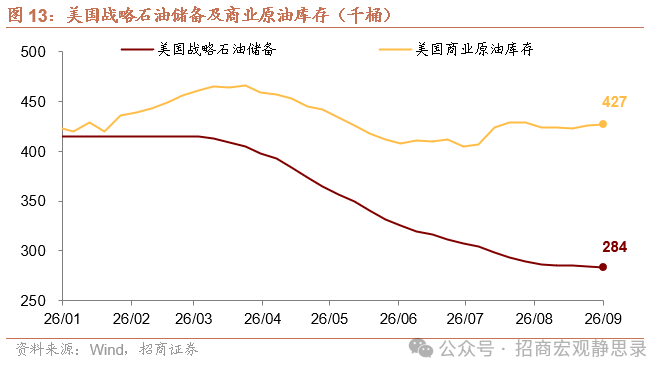
The short-term liquidity recovery scenario we have mentioned many times before is gradually being realized and is providing a temporary boost to risk appetite. However, looking back, the September rate hike did not run out of steam; it was the beginning of the Fed's interest rate hike cycle. Due to factors such as the difficulty of fundamentally easing the US-Iran conflict, the potential risk of spillover from the conflict, and the continued decline in global crude oil reserves, we have determined that liquidity will continue to decline even after maintaining a brief recovery.
2. ECB: Expectations of interest rate hikes have cooled down
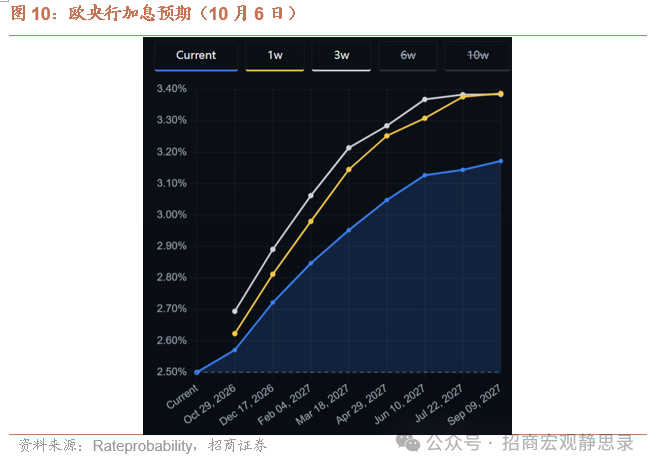
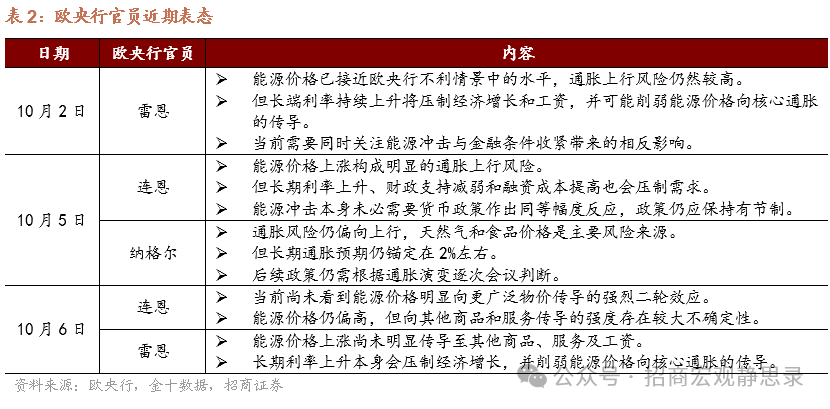
Recently, ECB officials have stated that the overall risk of rising inflation is still high, but some officials also pointed out that rising interest rates and weakening financial support are dragging down the economy, so expectations for the October rate hike have also cooled down. Eurozone CPI rose 3.3% year on year in August, up from 2.9% in July, the highest level since September 2023, and has also been higher than the ECB's 2% target for many consecutive months. After excluding food and energy, the core inflation rate fell slightly to 2.4%, indicating that current inflationary pressure is still mainly focused on energy supply shocks rather than overall overheating of demand. The ECB raised interest rates by 25BP in September. Considering the weak momentum of economic recovery, it is possible to raise interest rates by another 25BP before January next year.
3. Bank of Japan: Still in the interest rate hike channel
The Japanese economy remains resilient. Although the situation in the Middle East and high oil prices have dragged down the economy, there is still support for exports, industrial production, and corporate investment. Private consumption remains resilient, and the real wage growth rate has been corrected. Japan's output gap in the first quarter of this year was 0.5%, a significant improvement from 0.1% in the 1st quarter of '24, and has stabilized above 0.5% for 4 consecutive quarters. Currently, the economy is in a moderate recovery channel.
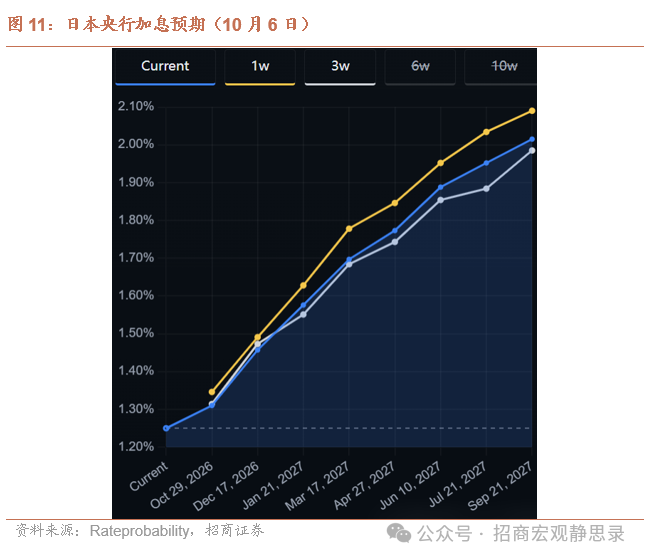
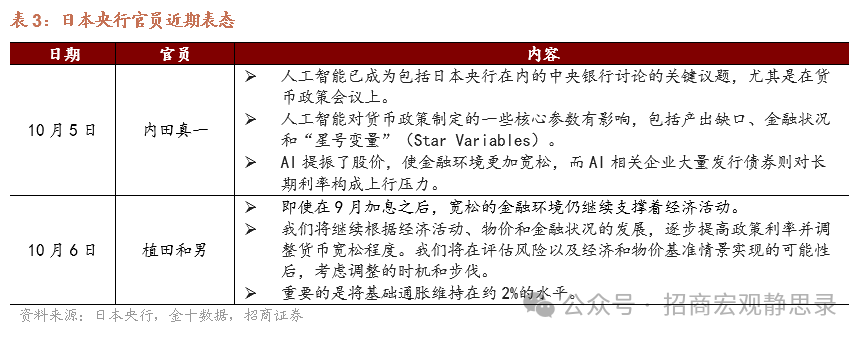
Ueda Kazuo clearly gave a signal to continue raising interest rates. On October 6, Kazuo Ueda said that we will continue to gradually raise policy interest rates and adjust the level of monetary easing according to developments in economic activity, prices, and financial conditions. Currently, the Bank of Japan's model estimates the natural interest rate range to be -0.9% to 0.5%. If the 2% inflation target estimates the nominal interest rate in the 1.1% to 2.5% range, it corresponds to a median expected value of around 1.8%. Kazuo Ueda also said that 2.5% may be the upper limit of the current estimated neutral range, and we expect the Bank of Japan to raise interest rates at least 2 more times.
III. Overseas current affairs highlights
1. The Middle East conflict has escalated, while oil prices have cooled down
The situation in the Middle East has once again escalated, and the conflict has further spilled over to the Red Sea and Saudi energy facilities. The differences between the US and Iran over navigation through the Strait of Hormuz and Iran's crude oil exports are still unresolved, and the military conflict in the Red Sea direction has further intensified. On October 5, Saudi-backed Yemeni government forces launched a new offensive against the Houthis, supported by large-scale Saudi air raids, to recapture some coastal areas near the Strait of Mande and advance towards the strategic port of Mocha. In response, the Houthis claimed to have attacked key facilities such as Saudi Riyadh King Khalid International Airport, Rabigh Saudi Arabian Refinery, and Abha Airport. The related attacks and losses have yet to be verified. Previously, Saudi Arabia's east-west oil pipeline had already been affected by attacks, and the suspension of Red Sea shipping also restricted crude oil exports from Yanbu Port. Overall, the Middle East conflict is being constrained by crude oil transportation in the Strait of Hormuz, further spreading to Red Sea shipping and Saudi energy infrastructure. The risks facing the regional energy supply chain are still high.
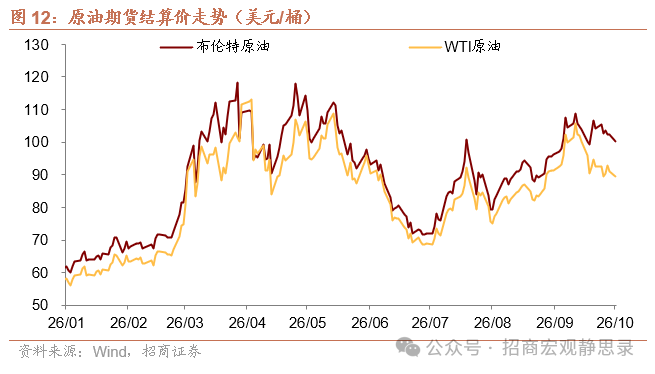
However, oil prices did not continue to rise unilaterally during the 11th holiday period; on the contrary, there was a certain cooling. The core reason may be the expectation that the market will start trading “repair supply faster than the conflict escalates faster.” The US Department of Energy announced on September 29 that it will once again launch the exchange of up to 40 million barrels of SPR crude oil, continuing the release schedule of 172 million barrels previously announced; on October 2, the G7 further agreed to release 100 million barrels of crude oil and diesel strategic reserves that have not been implemented in the previous commitments within the next 4 months, and prioritize diesel, while promising to avoid implementing energy export restrictions. Meanwhile, on October 5, Trump signed an executive order temporarily allowing duty-free dyed diesel originally used in agriculture, construction, etc. for road transportation, and deferred the relevant federal diesel tax payment obligations until the end of the year in order to reduce truck transportation and agricultural production costs. In terms of prices, as of October 5, the average weekly prices of Brent and WTI dropped from $103.53 per barrel and $90.42 per barrel on September 30 to $100.32 per barrel and $89.43 per barrel, respectively.
Looking back, as the US midterm elections approach, the Trump administration has strong policy demands to stabilize energy prices and ease the pressure on residents' living costs. It is expected that in the short term, it will still actively take measures to curb the excessive rise in oil prices. However, strategic reserves mainly relieve phased supply pressure. If the policy inventory buffer weakens after the election, compounded by the continuation of the Middle East conflict and the blocking of key waterways again, oil prices still face the risk of rising again.
2. Accelerate the reshaping of the European political landscape
Britain is rediscussing its long-term relationship with the EU, and the relationship between Britain and Europe is expected to improve further. On September 30, British Prime Minister Burnham said that Britain should re-evaluate its relationship with Europe after Brexit and include plans to maintain the status quo, join the customs union, return to the European single market, and even rejoin the EU in long-term policy discussions. He believes that the negative impact of Brexit on the British economy exceeds the benefits, and that the existing cooperation arrangements need to be further adjusted. Compared to previous cooperation, which mainly revolved around specific trade and regulatory rules, the British government now clearly included re-entry into the Union as a policy option for the first time, which means that the improvement of the relationship between Britain and Europe is beginning to extend from technical cooperation to deeper institutional relationship discussions. French President Emmanuel Macron welcomed the possibility of Britain re-entering the Union, but emphasized that Britain cannot selectively enjoy the benefits of EU membership. Recently, the two sides have promoted cooperation in areas such as agricultural trade rules, carbon emissions trading system docking, and youth exchanges, and are planning to hold a summit between Britain and Europe in November. Looking ahead, economic and institutional ties between Britain and Europe are expected to be further strengthened, but re-joining the single market or the EU still involves multiple restrictions such as regulatory autonomy and free movement of people, and actual progress in the short term will still focus on cooperation in specific fields.
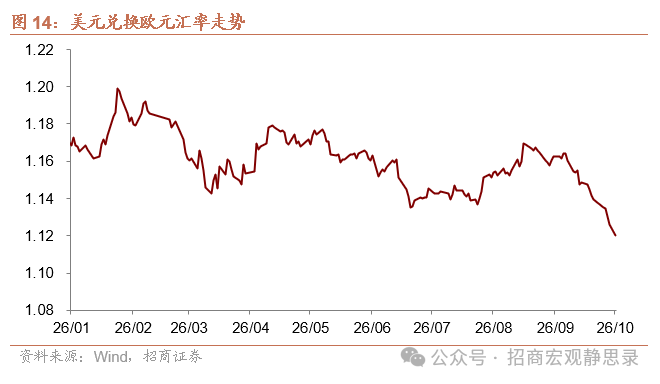
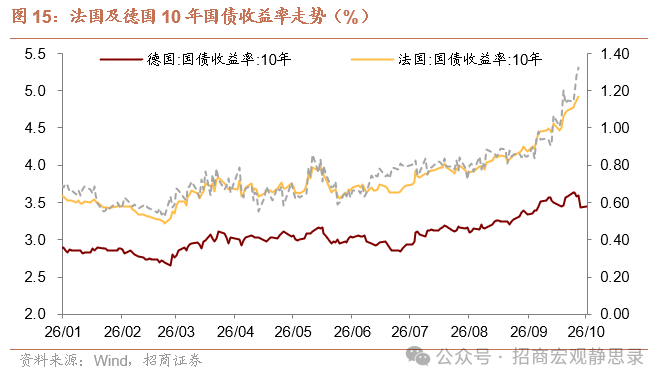
Meanwhile, the EU's internal political and financial risks are rising, and France's financial difficulties and Spain's early general election have heightened market concerns. On October 1, the French government announced the draft 2027 budget. It plans to achieve fiscal savings of about 54 billion euros through measures such as freezing wages and pensions in the public sector and reducing local government and medical expenses, reducing the fiscal deficit rate from 5.4% in 2026 to 5.0% in 2027. However, the size of France's public debt is close to 119% of GDP. Combined with the 2027 presidential election approaching and the large political differences in parliament, the implementation of the budget is still facing strong resistance. Market concerns about France's fiscal sustainability have further heated up. The interest spread on 10-year French and German bonds once widened to about 150 BP, a new high since the European debt crisis in 2011. On October 5, Spanish Prime Minister Sanchez announced that the 2027 general election will be brought forward to November 29 this year. The main background is that housing reforms have been blocked, insufficient support from the ruling coalition parliament, and ongoing domestic housing protests. Due to the combination of multiple political risks, the exchange rate of the euro against the US dollar fell to a low level of 1.12 on October 5. Looking back, there is still uncertainty about France's fiscal consolidation and the Spanish election results, which may continue to push up Europe's sovereign risk premium and increase volatility in the euro and European bond markets.
3. The Takaichi government faces the double constraints of fiscal and monetary policies
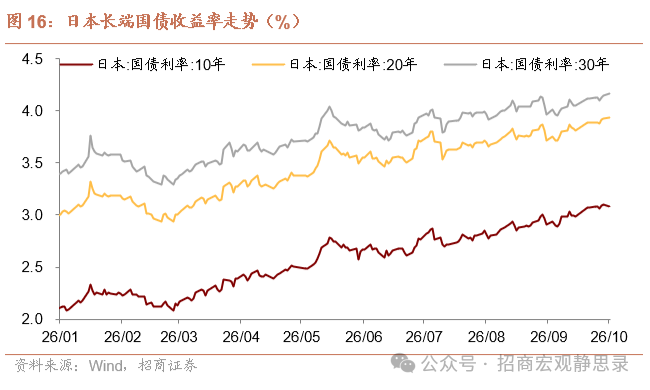
The conflict between the Takaichi government's active finance and the Bank of Japan's monetary tightening has further become apparent, and the Japanese bond market is under pressure. According to a summary of opinions from the Bank of Japan's September interest rate meeting released on October 1, some members believe that potential inflation is close to or above the 2% target and that it is necessary to further push forward interest rate hikes, but government representatives emphasized that the cumulative impact of previous interest rate hikes on the economy should be carefully assessed. On October 5, Sanae Takaichi reiterated her “responsible and active fiscal policy” in her policy address to the National Assembly. She plans to support economic growth through measures such as food consumption tax relief and strategic investment, while also promising to control the scale of treasury bond issuance and maintain fiscal sustainability. However, market concerns about fiscal expansion and debt burdens are still strong, and the yield on Japan's 30-year treasury bonds rose to an all-time high of 4.166%.
On October 6, Bank of Japan Governor Kazuo Ueda further emphasized the importance of anchoring potential inflation stability at around 2%, and the Bank of Japan's concern about inflation risks continues to rise. On the same day, it was reported that the Bank of Japan may confirm in the subsequent economic outlook that potential inflation has reached the 2% target, thereby further strengthening the market's expectations for continued interest rate hikes during the year. Looking back, the difficulty of coordination between the fiscal expansion of the Takaichi government and the normalization of the Bank of Japan's monetary policy has increased. Combined with high energy prices and weak yen, Japan's long-term treasury bond yields are still facing some upward pressure, and fluctuations in the yen and Japanese risk assets are likely to increase.
4. Summary of other overseas information
1) On September 30, Russia launched a new round of large-scale air raids on Ukraine's energy infrastructure. The Russian military used missiles and drones to attack energy facilities in Kyiv and other regions of Ukraine, which affected electricity supply in some regions. As winter approaches, Russia and Ukraine continue to upgrade their attacks and defenses over energy infrastructure, and Ukraine's electricity supply and energy security are under further pressure.
2) On October 1, Trump stepped up his efforts to support the election in the middle election to stand up for the Republican Party candidate. Trump went to Texas and Oklahoma on the same day to participate in the election campaign, officially starting an intensive campaign support program about a month before being elected, and plans to go to key states such as Ohio and Nebraska later. Currently, issues such as the cost of living, energy prices, and immigration are still the focus of voters' attention. The midterm election results will determine congressional control over the next two years and affect the Trump administration's energy and tariff policy space.
3) On October 2, Russia further relieved the pressure on war spending through unconventional fiscal measures. According to Reuters, since 2026, wealthy Russian individuals have contributed about 471 billion rubles (about 5.6 billion US dollars) to the government through so-called “voluntary donations,” which is equivalent to more than 1% of the annual federal budget; at the same time, the Russian government also plans to raise financial resources by selling confiscated assets, raising taxes, and increasing government loans. After entering the fifth year of the Russian-Ukrainian conflict, military and security-related expenditure still accounts for a high proportion of Russia's fiscal expenditure, and fiscal financing pressure continues to rise.
4) On October 3, Ukraine announced that it would step up its crackdown on Russian refining facilities. Ukrainian President Zelensky said that in response to Russia's recent new round of air raids on Ukrainian cities and critical infrastructure, Ukraine will further attack Russian oil refineries and other energy facilities. The US has previously asked Ukraine to carefully attack Russian oil facilities to avoid further boosting global energy prices. As mutual attacks on energy infrastructure between the two sides intensify, the spillover effects of the Russian-Ukrainian conflict on Russian refined oil supply and the global energy market deserve continued attention.
5) On October 4, Brazil held the first round of voting in the presidential election. Flavio Bosonaro was ahead of current President Lula in winning votes. According to the results of the first round of voting, right-wing senator Flavio Bosonaro, the son of former President Bossonaro, received about 47% of the valid votes, and Lula received about 45%. Neither of them reached the majority required for direct election. The second round of voting will be held on October 25. Flavio's first round performance exceeded expectations in most previous polls, and his Liberal Party also expanded its seat in the National Assembly election.
6) On October 5, the European Union accused Russia of carrying out mixed attacks against European countries. EU High Representative for Foreign Affairs and Security Policy Callas said that Russia recently threatened European security through drone crossings, sabotage activities, and other mixed attacks. Earlier, on September 30, the Moldovan side reported that 3 drones had entered its airspace. The EU side believes that related incidents have heightened security risks in the European region, and concerns that the Russian-Ukrainian conflict will spill over into neighboring countries have further heated up.
IV. Overseas asset price trends
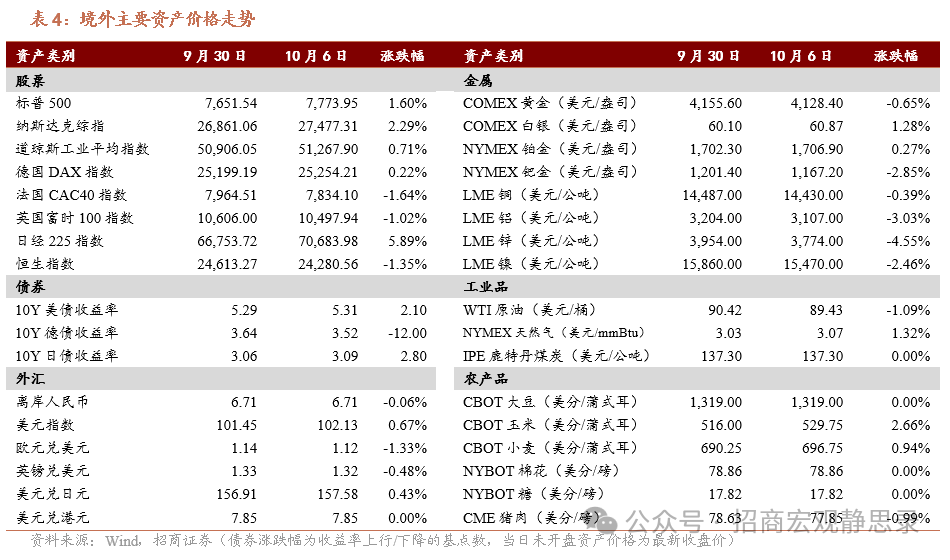
The performance of foreign assets from September 30 to October 6, 2026 is shown in the table below:
Overseas stock markets generally rose: US stocks rose 1.60%, the NASDAQ Composite Index rose 2.29%, and the Dow rose 0.71%; Germany's DAX rose 0.22%, France's CAC fell 1.64%, the UK FTSE 100 fell 1.02%, and Nikkei 225 rose 5.89%.
International bonds: The yield on 10-year US bonds rose by 2.1 BP to 5.31%, while 10-year German and Japanese bond yields changed by -12.0 BP and 2.8 BP, respectively.
Foreign exchange market: The US dollar index rose 0.67%, the euro, pound, and yuan depreciated, and the yen appreciated.
The commodity market generally declined: most metal prices fell, and COMEX gold, silver, platinum and palladium prices changed by -0.65%, 1.28%, 0.27%, and -2.85%, respectively. LME copper, aluminum, zinc and nickel decreased by 0.39%, 3.03%, 4.55%, and 2.46%, respectively. In terms of industrial products, WTI crude oil prices fell 1.09%, and NYMEX natural gas rose 1.32%. In terms of agricultural products, corn and wheat rose by 2.66% and 0.94% respectively, while pork decreased by 0.99%.